

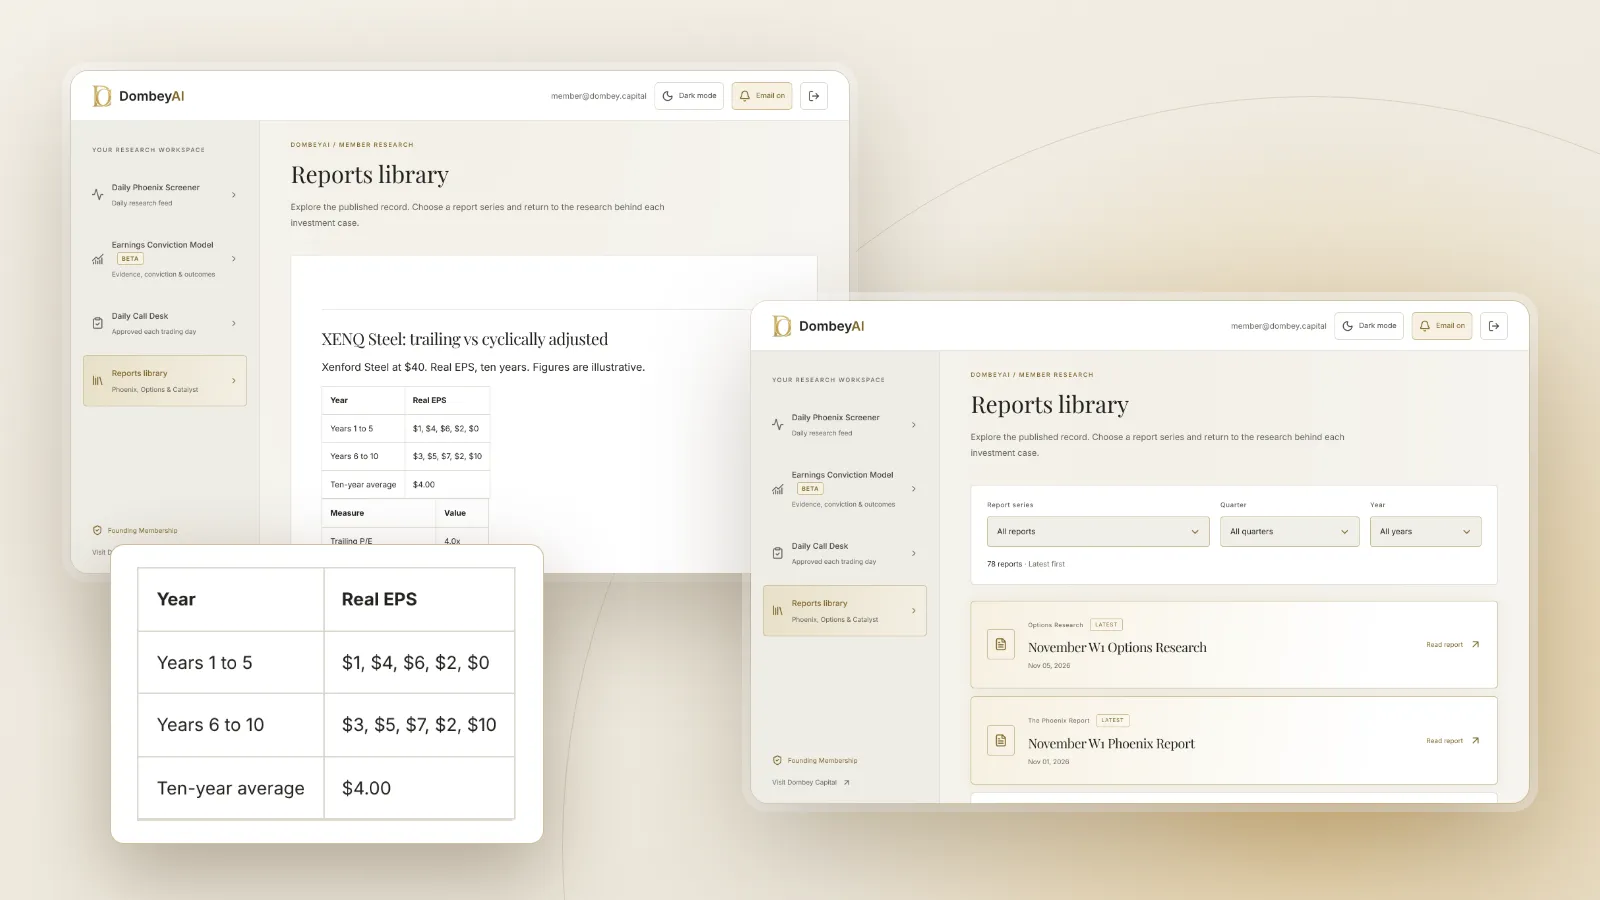
How the CAPE ratio is calculated
The formula has three steps:
- Take earnings per share for each of the last ten years.
- Convert each year into today's dollars using the Consumer Price Index.
- Divide today's price by the average of those ten real earnings figures.
| Input | Regular trailing P/E | CAPE ratio |
|---|---|---|
| Earnings period | Last 12 months | Last 10 years, averaged |
| Inflation adjustment | None | Each year restated with CPI |
| Response to a recession | Earnings fall, P/E jumps | Small change in the average |
| Response to a real change in earning power | Immediate | Slow, over several years |
| Typical use | Single stocks and markets | Mainly broad markets |
The trailing P/E and its forward-looking cousin are compared in forward P/E vs trailing P/E. CAPE sits at the other end: it looks back further than either.
Why ten years
A decade usually covers at least one full business cycle. In a recession, earnings collapse and the one-year P/E can look absurdly high just when prices are low. In a boom, earnings swell and the P/E looks cheap just when prices are high. Averaging across the cycle removes most of that distortion. It is the same logic behind normalized earnings for a single company: value a business on what it earns in an ordinary year.
How to read it
The ratio is easiest to read against its own history. Over the long run of US data, the S&P 500's CAPE has averaged in the mid-teens, with peaks around 1929 and above 40 in late 1999. Very high readings have tended to come before weak ten-year returns, and low readings before strong ones.
Two cautions apply.
First, the relation is loose. The ratio explains part of the spread in ten-year returns, but a given reading has been followed by a wide range of outcomes.
Second, the horizon is long. CAPE has said little about the next one or two years. A market that looks expensive can get more expensive for a long time.
Example: CAPE for a cyclical company
That gap is the main use of the idea at the company level. Cyclical stocks often look cheapest on trailing earnings at the top of the cycle, a common route into a value trap.
How to calculate it yourself
You can rebuild the figure for an index or a single company with public data and a spreadsheet.
- Collect annual earnings per share for the last ten fiscal years from the 10-K filings or the index provider. Use reported earnings, not adjusted figures, so the series is consistent.
- Collect the Consumer Price Index for each year from the Bureau of Labor Statistics.
- Restate each year's earnings in today's dollars: multiply by today's CPI and divide by that year's CPI.
- Average the ten restated figures.
- Divide the current price by that average.
Two choices change the answer more than most people expect. The first is whether to use reported or operating earnings: operating figures exclude write-downs and lift the average, which lowers the ratio. The second is whether to adjust for share count changes. A company that has bought back a large part of its stock will show faster growth in earnings per share than in total earnings, and a ten-year average of per-share figures will lag. Note both choices next to the result so you compare like with like over time.
Where this goes wrong
CAPE has well-known weaknesses, and most of them push the ratio higher today than a like-for-like comparison would.
- Accounting changes. Rules on goodwill write-downs changed in the early 2000s, and large one-time impairments in recessions now drag on reported earnings more than they once did. That depresses the ten-year average and lifts CAPE.
- Payout policy. Companies now return more cash through buybacks and less through dividends, which can make earnings per share grow faster than in the past. A ten-year average then lags current earning power by more than it used to.
- Sector mix. The index today holds more software and fewer railroads and steel mills. Businesses with higher returns on capital can justify higher multiples, so the long-run average may not be the right anchor.
- Interest rates. Low real yields support higher valuations across assets. Comparing CAPE with a period of high real yields ignores that.
- Structural change in one company. For a single stock, earnings from ten years ago may describe a different business, before an acquisition, a spin-off or a collapse in demand.
The useful response is not to drop the measure but to use base rates with care: compare with more recent decades as well as the full history, and check whether the earnings series is distorted by one-time items.
How investors use it
- If you are deciding how much to expect from a broad index over a decade, CAPE is a reasonable starting point.
- If you are timing an entry or exit over the next year, it is a poor tool, and other evidence should decide.
- If you are valuing a cyclical company, a CAPE-style ten-year average is a sensible cross-check on trailing earnings.
- If a company's business has changed, use normalized earnings for the current business instead.
| Situation | How useful CAPE is | Better companion measure |
|---|---|---|
| Ten-year market return expectations | Useful | Earnings yield vs real bond yield |
| Short-term market timing | Weak | None reliable |
| Cyclical single stock | Useful | Normalized earnings, margin of safety |
| Fast-changing single stock | Weak | Forward estimates, discounted cash flow |
| Special situations with a dated event | Weak | Event-specific valuation |
For special situations, where value depends on a spin-off, a sale or a court ruling, a market-wide multiple adds little. Those cases need event-specific work, the kind Dombey publishes in its research archive. For the tools that make the underlying data easy to pull, see the best stock research tools for individual investors.
The bottom line
The CAPE ratio compares price with ten years of average real earnings, which removes most of the business cycle from the P/E. It has a loose historical link with long-run market returns and almost none with short-term moves. Accounting rules, buybacks, sector mix and interest rates all shift the ratio, so compare it with recent decades as well as the full history. At the company level, the same averaging is a good check on cyclical earnings and a poor one for businesses that have changed.