

The formula
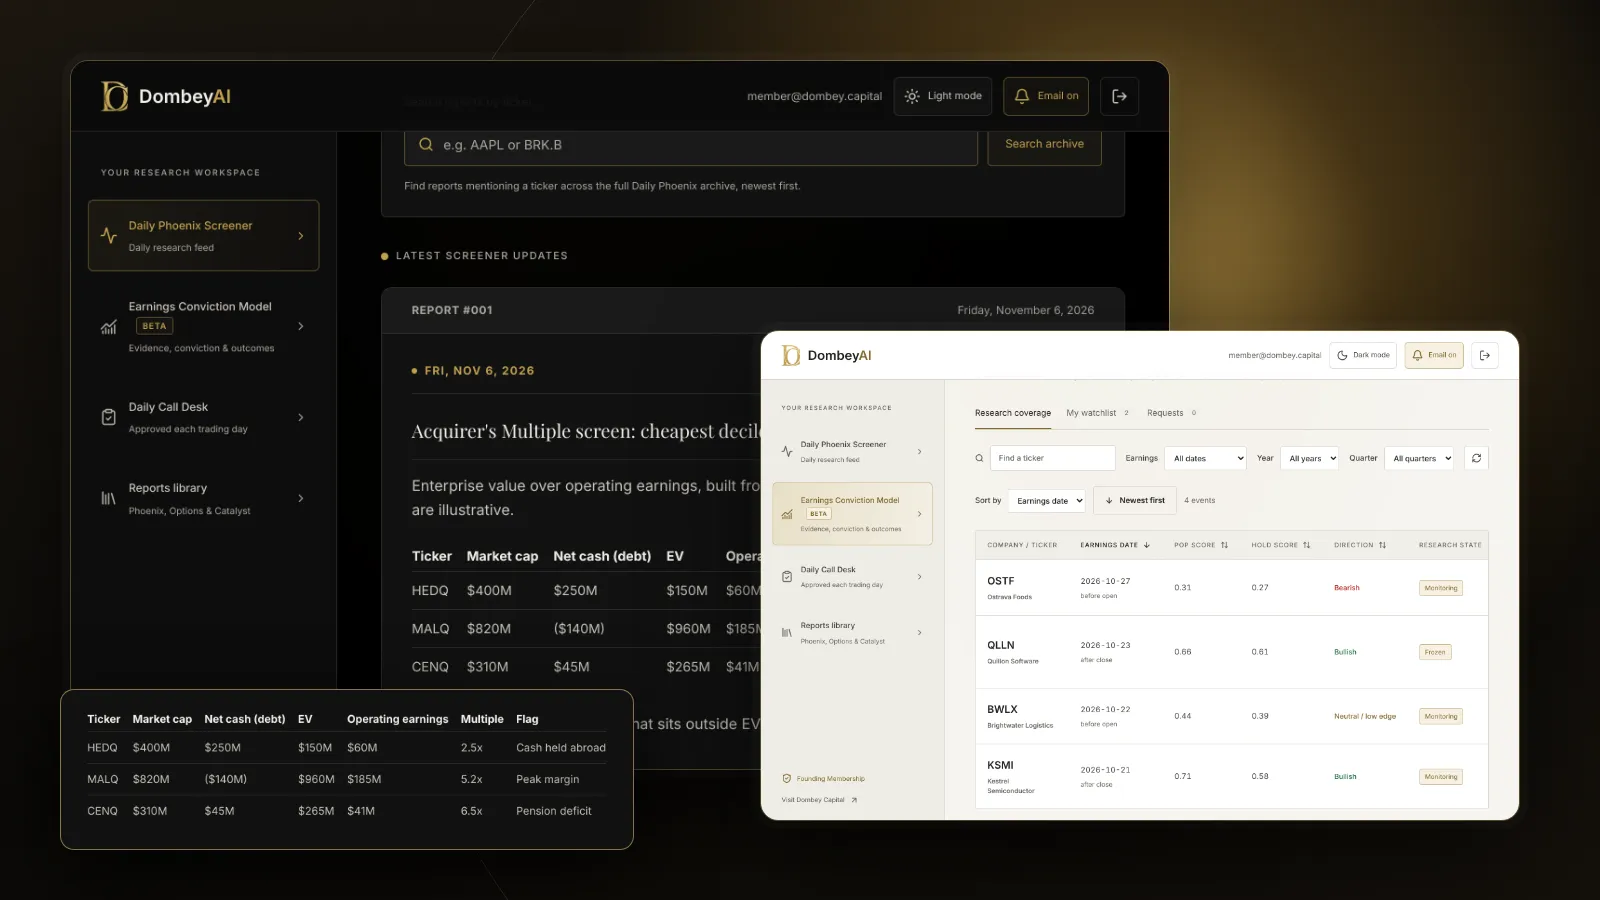
Acquirer's Multiple = enterprise value / operating earnings
Enterprise value is the price of the whole business:
- Market capitalization
- plus debt
- plus preferred stock
- plus minority interests
- less cash and short-term investments
Our explainer on enterprise value covers each item and the common mistakes.
Operating earnings are built from the top of the income statement:
- Revenue
- less cost of goods sold
- less selling, general and administrative expense
- less depreciation and amortization
Building earnings this way, rather than taking the reported operating income line, keeps out items that companies sometimes put inside operating income: gains on asset sales, impairments, litigation settlements and restructuring charges. The aim is a cleaner view of recurring operating profit. Our guide on reading an income statement shows where each line sits.
Quick reference: how it compares
| Ratio | Numerator | Denominator | Captures capital structure | Includes a quality test |
|---|---|---|---|---|
| P/E | Share price | Earnings per share | No | No |
| EV/EBITDA | Enterprise value | EBITDA | Yes | No |
| EV/EBIT | Enterprise value | Reported operating income | Yes | No |
| Acquirer's Multiple | Enterprise value | Operating earnings built from revenue down | Yes | No |
| Magic Formula | Ranks EBIT/EV and return on capital | Yes | Yes, return on capital |
Against EV/EBITDA, the Acquirer's Multiple subtracts depreciation and amortization, which matters for capital-heavy businesses where those charges reflect real spending. Our explainer on EV/EBITDA covers that blind spot. Against the P/E ratio, it treats a company with net cash and one with heavy debt differently, which a share price alone cannot do.
Why leave out quality
The Magic Formula ranks companies on both cheapness and return on capital. Carlisle's argument for dropping the second rank rests on mean reversion: businesses earning unusually high returns tend to attract competition, and those returns tend to fall, while businesses earning unusually low returns tend to cut costs, shed weak divisions or get bought, and their returns tend to rise.
If that is right, a quality filter can push a screen toward companies whose best years are behind them and away from depressed companies with recovery ahead. The cheapest stocks by the Acquirer's Multiple are often companies with bad recent results, unpopular industries or large cash piles that the market discounts.
Worked example
| Item | Company A | Company B |
|---|---|---|
| Market capitalization | 400 | 400 |
| Debt | 0 | 300 |
| Cash | 250 | 20 |
| Enterprise value | 150 | 680 |
| Revenue | 900 | 900 |
| Cost of goods sold | 600 | 600 |
| SG&A | 200 | 200 |
| Depreciation and amortization | 40 | 40 |
| Operating earnings | 60 | 60 |
| Acquirer's Multiple | 2.5x | 11.3x |
Both companies have the same market value and the same operating earnings, so they have the same price to operating earnings. The Acquirer's Multiple separates them. Company A's net cash of $250 million means a buyer pays $150 million for the business itself. Company B's net debt means a buyer takes on $280 million of obligations on top of the equity.
Company A is the kind of name the screen surfaces. The next questions are whether the cash is really available to shareholders, whether the operating earnings are stable, and whether management will spend the cash well. Our explainer on net cash per share covers the first question, and the one on negative enterprise value stocks covers the extreme case where cash exceeds the market value.
Why the acquirer's view matters
The name comes from the way a buyer of a whole company thinks. A private equity firm or a strategic buyer does not buy a share; it buys the business, takes on its debt and gets its cash. What it pays for operating profit is the number that decides whether the deal works.
That view has three consequences for a public market investor:
- Cash counts. A company with a large cash balance is cheaper to a buyer than its market capitalization suggests. The ratio captures that, where the P/E ratio does not.
- Debt counts. A company with heavy borrowing is more expensive to a buyer than its share price suggests. The ratio captures that too.
- Takeover appeal. Companies that look cheap on this basis are the ones a buyer could pay a premium for and still earn a reasonable return. A low multiple does not mean a bid will come, but it is one reason a company can become a target. Our explainer on the takeover premium covers how buyers price that premium.
The same arithmetic shows why a buyer's view and a minority holder's view can differ. A buyer can redeploy the cash, cut costs and change management. A minority holder depends on the existing board to do those things. A low multiple with no route to change can stay low for a long time.
Using it in a screen
The multiple is usually used to rank, not to test against a threshold:
- Set the universe. Most versions use a minimum market capitalization and exclude financial companies, where debt is part of operations and enterprise value is not meaningful.
- Compute the multiple for every company with positive operating earnings.
- Rank from lowest to highest.
- Review the cheapest names one by one before drawing any conclusion.
Carlisle's own site, acquirersmultiple.com, publishes a screen. Many of the best stock screeners for value investors let you build a similar one from EV and operating income fields, though their definitions of each may differ from Carlisle's.
Where this goes wrong
Peak earnings. A cyclical company at the top of its cycle has high operating earnings and a low multiple just before profits fall. Compare current margins with a long history, or use normalized earnings.
Declining businesses. A company losing customers can look cheap every year as earnings and price fall together. Check revenue trends and market share before reading a low multiple as a bargain. Our list of value trap warning signs covers the usual signals.
Missing claims in enterprise value. Operating leases, underfunded pensions, environmental liabilities and contingent payments can be large. A screen built from a data feed often misses them, and the multiple then looks lower than it is.
Trapped cash. Cash held overseas, in a regulated subsidiary or needed for working capital is not fully available to a buyer. Treating all of it as surplus understates enterprise value.
Adjusted figures. Some data sources add back stock-based compensation or other items. The multiple is only as good as the operating earnings behind it; compare the figure you use with the company's reported statements and any adjusted EBITDA reconciliations.
The bottom line
The Acquirer's Multiple divides enterprise value by operating earnings to show what a buyer of the whole company would pay for its operating profit. It differs from EV/EBIT mainly in building earnings from revenue down, and from the Magic Formula in leaving out quality on the view that high returns fade. The ranks it produces are a list of disliked, cheap companies, and each one needs a check of the cycle, the trend and the liabilities outside enterprise value. For tools that help with that follow-up work, see our guide to the best stock research tools for individual investors.