

The formula
Earnings yield = earnings per share / share price
Use diluted earnings per share for the last twelve months for a trailing yield, or a forecast for a forward yield. Our explainer on forward and trailing P/E covers which to use when.
| P/E ratio | Earnings yield |
|---|---|
| 8 | 12.5% |
| 10 | 10.0% |
| 12.5 | 8.0% |
| 15 | 6.7% |
| 20 | 5.0% |
| 25 | 4.0% |
| 40 | 2.5% |
The yield form has two practical advantages. It handles low or near-zero earnings better than a P/E, which becomes very large or meaningless as earnings approach zero. And it averages sensibly: the average earnings yield of a group of stocks is more meaningful than the average of their P/E ratios.
Earnings yield against bond yields
The most common use is comparing a stock or the market with government bond yields. The 10-year Treasury yield, published daily by the Federal Reserve in its H.15 release, is the usual benchmark.
The gap between the two is a rough measure of the extra return investors expect for owning stocks, often called the equity risk premium. A wide gap suggests stocks are priced for a healthy premium. A narrow gap suggests investors are counting on earnings growth to make up the difference.
The same logic works for a single stock. Compare its earnings yield with the yield on its own bonds. If the bonds yield more than the stock's earnings yield, shareholders are accepting a lower current return than creditors who rank ahead of them, which only makes sense if earnings are expected to grow. If that growth looks unlikely, the stock may be expensive relative to its own debt.
Why the comparison is imperfect
| Feature | Bond yield | Earnings yield |
|---|---|---|
| Cash received | Coupon paid in full | Only the dividend is paid out |
| Growth | None; the coupon is fixed | Earnings can grow or shrink |
| Inflation | Nominal; inflation erodes it | Earnings partly adjust with prices |
| Certainty | Contractual, subject to default | No contractual claim |
| Rank in the capital structure | Ahead of equity | Last |
Two points stand out. First, retained earnings are not wasted: they fund growth, buybacks or debt repayment, and their value depends on what the company earns on them. Our explainer on ROIC covers that link. Second, the inflation mismatch cuts both ways. A company with pricing power can raise earnings with inflation; one with fixed-price contracts cannot.
For a fairer comparison with bonds, some investors adjust the earnings yield for expected growth. In a steady-state company, the expected return on the stock is roughly the earnings yield adjusted for how much is reinvested and at what return, which is the logic behind a discounted cash flow model.
The enterprise version: EBIT to EV
Net earnings per share depend on how much debt a company carries. Two companies with identical businesses can have very different P/E ratios if one is financed with debt.
The enterprise earnings yield removes that effect:
EBIT yield = EBIT / enterprise value
Enterprise value is market capitalization plus debt and other claims, minus cash. Operating profit before interest and tax is the profit available to all capital providers. The result is a yield on the whole business, which makes companies with different balance sheets comparable. It is the version used in several well-known value screens.
For companies with large cash balances, the EBIT yield can be much higher than the P/E suggests. Our explainer on net cash per share shows how cash changes the picture.
Trailing, forward and normalized yields
Which earnings go on top of the fraction changes the answer:
| Version | Earnings used | Strength | Weakness |
|---|---|---|---|
| Trailing | Last twelve months, reported | Based on actual results | Backward looking |
| Forward | Next twelve months, consensus | Reflects expected change | Depends on estimates |
| Normalized | Average across a cycle, adjusted | Removes peaks and troughs | Requires judgment |
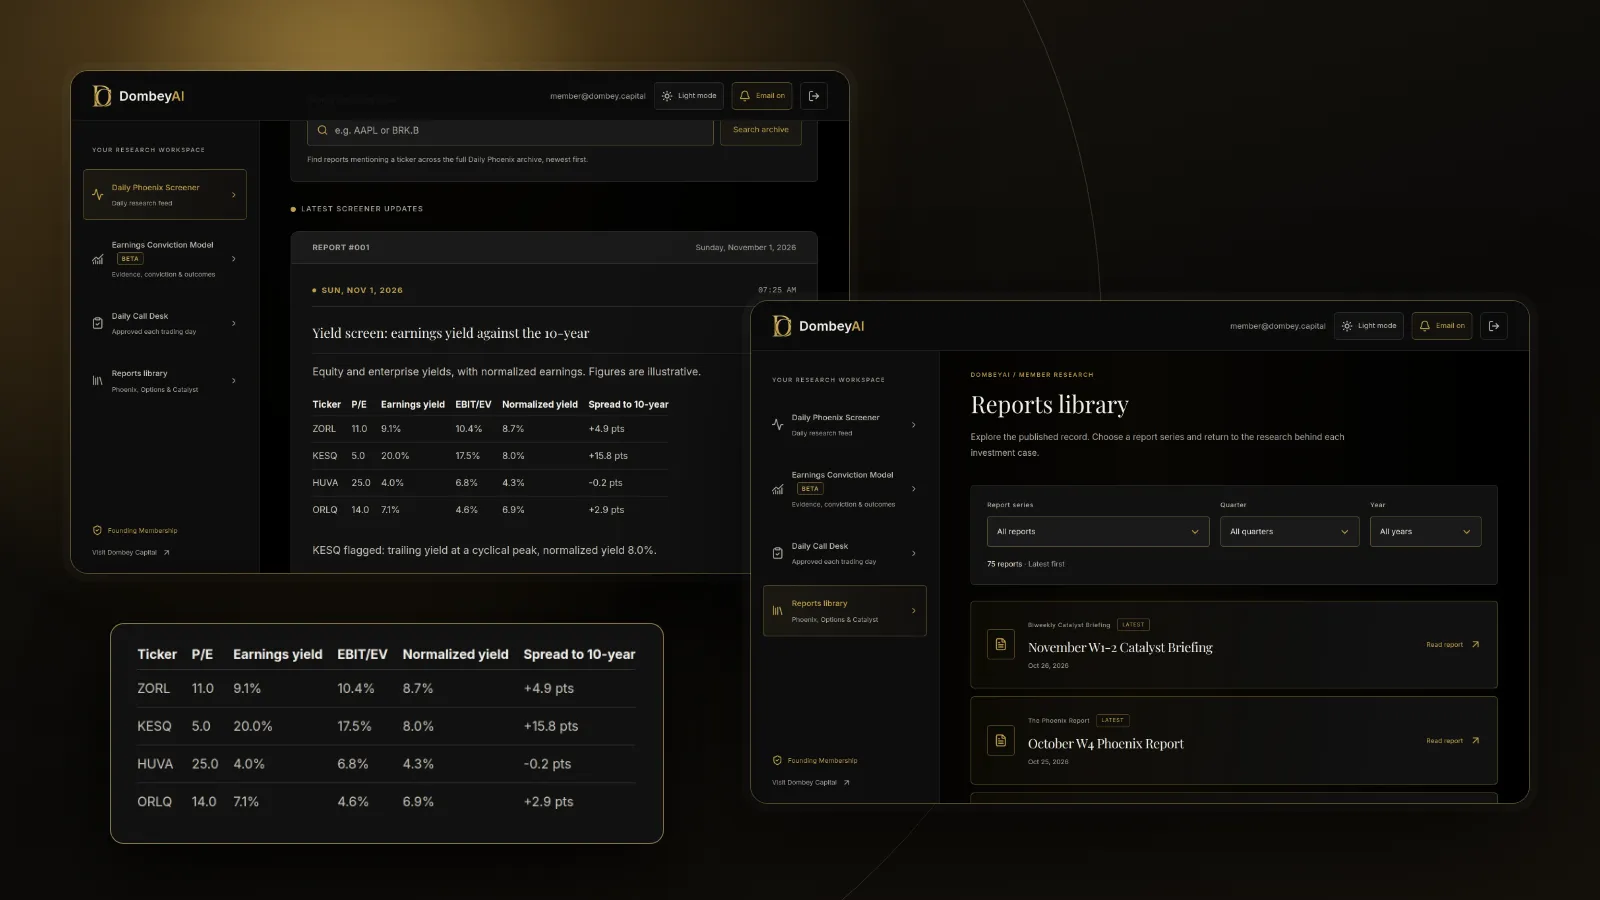
For a stable company the three are close. For a cyclical company they can differ widely: a steelmaker at the top of the cycle may show a trailing earnings yield of 20% and a normalized yield of 8%. The normalized figure is usually the better guide to value, and the gap between trailing and normalized is a measure of how much of the current yield is temporary.
Related yields
- Free cash flow yield uses free cash flow instead of earnings, which avoids accrual accounting effects. See free cash flow yield.
- Dividend yield counts only cash paid out.
- Shareholder yield adds net buybacks to dividends.
Each answers a different question. Earnings yield measures what the business earns for each dollar of price; the cash-based yields measure what reaches owners.
How to use earnings yield in research
- If the earnings yield is high, check whether earnings are at a cyclical peak. Use normalized earnings across a cycle.
- If the earnings yield is far above the EBIT yield, check for low-tax years or one-off gains.
- If the EBIT yield is high but the earnings yield is low, debt and interest costs are absorbing operating profit.
- If the market's earnings yield is close to bond yields, stocks are relying on growth, and disappointments cost more.
Most data platforms in our list of the best stock research tools for individual investors show earnings yield or let you build it as a screen. Dombey's published research reports valuation on both an equity and an enterprise basis; see the research archive.
Where this goes wrong
- Peak earnings. A cyclical company at the top of its cycle shows its highest earnings yield just before earnings fall. That is the value trap pattern.
- Adjusted earnings. Yields built on adjusted figures can exclude recurring costs.
- Losses. Negative earnings make the yield useless for ranking.
- Comparing across sectors. Banks, utilities and software companies have very different normal yields because of growth, leverage and capital needs.
- Treating the bond comparison as a signal. Market-level earnings yields and bond yields can stay apart for long periods.
The bottom line
Earnings yield is earnings per share divided by price, the inverse of the P/E ratio, and it puts stocks on the same footing as bonds. The gap over the Treasury yield is a rough measure of the equity risk premium, but earnings differ from coupons in payout, growth and inflation. Use EBIT to enterprise value to compare companies with different balance sheets. Check that the earnings are normal, recurring and unadjusted before relying on the yield.