

Why reported earnings mislead for cyclical companies
Take a steelmaker, a homebuilder or a chemical producer. When demand is strong, prices rise, factories run full and margins expand. Earnings jump. When demand falls, the same fixed costs are spread over less output, and earnings collapse or turn into losses.
The price-to-earnings ratio then works backwards. At the peak, earnings are high and the P/E looks low, just before profits fall. At the trough, earnings are depressed and the P/E looks high or meaningless, just before profits recover. An investor screening for low P/E ratios will tend to find cyclical stocks near their peak. Our comparison of forward and trailing P/E shows how the same problem affects both measures.
Normalized earnings replace one year's figure with an estimate of typical earnings, so the multiple reflects the whole cycle rather than one point on it.
Three ways to normalize
| Method | How it works | Best for | Weakness |
|---|---|---|---|
| Average earnings | Average earnings per share over 7 to 10 years | Stable businesses with long histories | Misses growth and changes in the business |
| Average margin | Apply the cycle-average margin to current or mid-cycle sales | Companies that grew over the period | Assumes margins revert to the old range |
| Adjusted current earnings | Remove one-off items from the latest year | Companies with clear one-off events | Relies on judgment about what recurs |
Average earnings
Benjamin Graham suggested valuing a company on its average earnings over seven to ten years, long enough to include good and bad years. The same idea sits behind the cyclically adjusted P/E, popularized by Robert Shiller, which divides an index's price by ten years of average inflation-adjusted earnings.
Averaging is simple and hard to manipulate. Its weakness is that it treats the past as a guide to the future. A company that has doubled in size over the decade will look expensive on its average earnings.
Average margin
To allow for growth, take the average operating or net margin over the cycle and apply it to current sales, or to an estimate of mid-cycle sales if current sales are themselves inflated or depressed.
Adjusted current earnings
The third method takes the latest year and removes items that will not recur: a gain on an asset sale, a legal settlement, an impairment charge, a large insurance recovery. This is closest to what companies present as adjusted EBITDA or adjusted earnings, and that is its risk. Management decides what to exclude, and costs that recur every year are often labeled one-off.
What to adjust beyond the cycle
The cycle is the big adjustment, but several others often matter:
- Tax rate. A year with a low tax rate from a one-off benefit overstates earnings. Use a normal rate.
- Interest costs. If debt is about to refinance at a higher rate, current interest expense understates the normal cost; see the debt maturity wall.
- Share count. Use the diluted count, including likely issuance.
- Depreciation against capital spending. If capital spending has run well below depreciation, current earnings may be flattered by under-investment. Our article on owner earnings covers this adjustment.
- Stock-based compensation. Treat it as a real cost, as discussed in is stock-based compensation a real expense.
How normalized earnings feed into valuation
Once you have a normalized figure, you can apply a multiple suited to typical conditions, or use it as the starting point for a discounted cash flow model. Normalized earnings also help with margin of safety: if the stock is cheap on normalized earnings and not just on peak earnings, the discount is more likely to be real.
The same thinking applies to return on capital. A company's ROIC at the peak of a cycle overstates what its capital normally earns, so normalize the numerator before comparing it with the cost of capital.
For special situations, normalized earnings help when an event lands at an unusual point in the cycle. A spin-off completed at a peak, an IPO priced on a record year, or a company emerging from restructuring on depressed earnings all need a view of typical earnings to judge the price. Dombey's published research uses a mid-cycle earnings view when a catalyst lands on a cyclical company; see the research archive.
Where this goes wrong
- The business has changed. A company that sold its best division, lost a major customer or faces a new competitor will not return to its old average. Normalizing assumes the past is representative.
- The cycle is longer than your data. Ten years of history may cover only the up phase of a long commodity cycle. Check where the industry sits relative to its own long-run history; base rates and the outside view helps here.
- Margins have structurally shifted. An industry that has consolidated may sustain higher margins than before; one facing new supply may not reach its old ones.
- One-off items keep recurring. Accepting management's exclusions without checking past years inflates normalized earnings.
- False precision. A normalized figure is a range, not a point. Show the result under two or three assumptions.
A short worked comparison
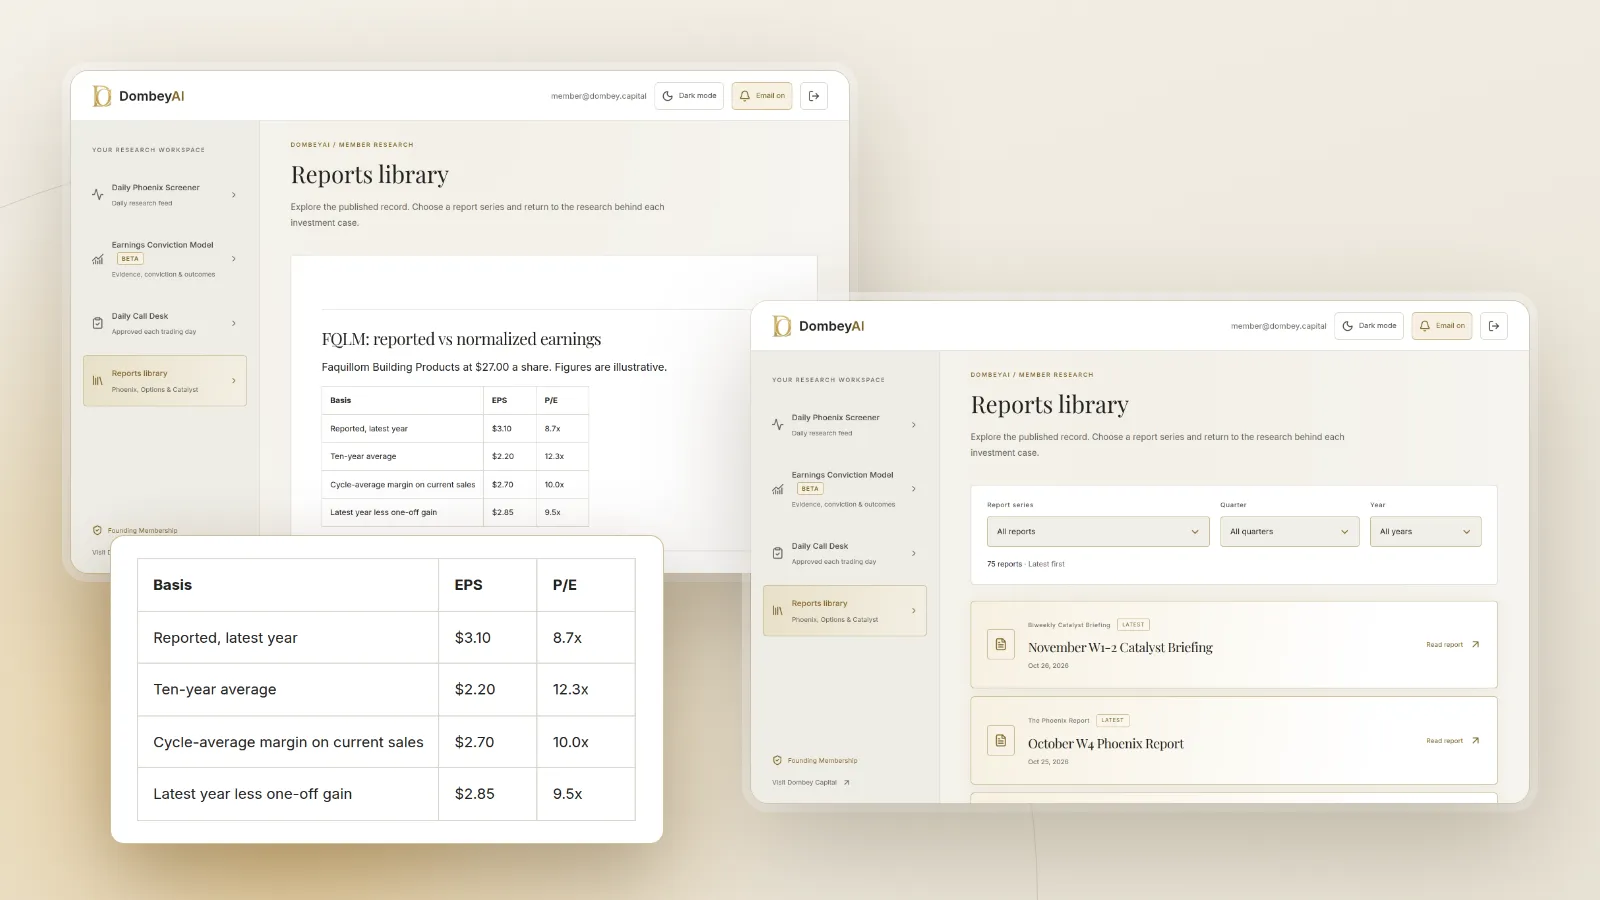
Comparing the three methods on one company shows why a range is more honest than a single figure.
The spread between 9.5 and 12.3 times is the honest answer. Which end you lean toward depends on whether the growth over the decade is durable and whether this year's margin is a peak.
Tools that help
You need ten years of income statements, margins and share counts, ideally adjusted for acquisitions. Several platforms in the 12 best stock research tools for individual investors provide long financial histories. Check any vendor history against the 10-K, especially around restatements and acquisitions.
The bottom line
Normalized earnings estimate what a company earns in a typical year, removing the cycle and one-off items. They matter most for cyclical companies, whose P/E ratios look cheapest at the peak and most expensive at the trough. Average earnings, average margins and adjusted current earnings each have uses, and comparing them gives a better range than any one alone. The method fails when the business has changed for good, so pair the numbers with a view of whether the past still describes the company.