

What you need
- The last three 10-K filings and the latest 10-Q, from EDGAR or the company's investor site.
- The loss reserve development table in the 10-K, which shows how reserve estimates for each accident year changed over time.
- The investment portfolio note: holdings by type, credit quality, duration and unrealized gains or losses.
- The latest investor presentation, for segment data and management's targets.
- A spreadsheet with ten years of book value per share, return on equity, combined ratio and dividends, if the filings go back that far.
Insurers are financial companies, so the tools in our bank stock valuation guide carry over: book value, return on equity and capital. The difference is that an insurer's largest liability is an estimate.
Step 1: Understand what the insurer writes
Read the business section and segment note. Property lines such as homeowners and commercial property are short-tail: claims are reported and paid within a year or two, but catastrophes cause large swings. Casualty lines such as workers' compensation, general liability and medical malpractice are long-tail: claims can take a decade to settle, so reserves are larger and less certain. Reinsurers take on risk from other insurers and are exposed to catastrophes. Life insurers and annuity writers carry liabilities that last decades and earn mainly on investment spreads.
Write down the mix. It sets the normal combined ratio, the reserve risk and the investment strategy for everything that follows.
Step 2: Start from book value
Take shareholders' equity and divide by shares outstanding. Then compute tangible book value by subtracting goodwill and intangibles; our guide to tangible book value covers the arithmetic. For insurers that have grown by acquisition, the gap can be large, and goodwill impairments can cut book value suddenly.
Also note accumulated other comprehensive income, which holds unrealized gains and losses on bonds. When rates rise, bond prices fall and book value drops even though the insurer may hold the bonds to maturity. Many analysts track book value both with and without it.
Step 3: Measure underwriting with the combined ratio
The combined ratio is losses and loss adjustment expenses plus underwriting expenses, divided by earned premium. Below 100% means underwriting is profitable before any investment income.
| Measure | Formula | What it tells you |
|---|---|---|
| Loss ratio | Losses and loss adjustment expenses / earned premium | Cost of claims |
| Expense ratio | Underwriting expenses / earned premium | Cost of acquiring and running the business |
| Combined ratio | Loss ratio + expense ratio | Underwriting profit or loss |
| Catastrophe load | Catastrophe losses / earned premium | How much one bad year can add |
| Prior-year development | Change in prior-year reserves / earned premium | How much the year's result came from old estimates |
Look at ten years, not one. Strip out catastrophe losses and prior-year development to see the underlying current accident year ratio, then add back a normal catastrophe load.
Step 4: Test the reserves
Loss reserves are the insurer's estimate of what it will pay on claims already incurred. If they are too low, past earnings and today's book value are overstated.
The 10-K's development table shows, for each accident year, the original estimate and how it changed. Read it for direction and size:
- Consistent favorable development suggests conservative reserving, which supports book value.
- Consistent adverse development, especially in long-tail lines, suggests book value is too high and earnings will be hit again.
- A sudden switch from favorable to adverse often marks the start of a reserve problem.
Compare reserves with premiums and with claims paid. A falling ratio of reserves to earned premium while the business mix is stable deserves a question. The footnotes guide covers how to compare the reserve note across years.
Step 5: Value the float and the investment portfolio
Float is the money held between collecting premiums and paying claims. The insurer invests it, and investment income is often the larger part of earnings.
Check three things in the investment note. First, the yield: is it rising as older bonds mature into higher rates, or falling? Second, the risk: the share in below-investment-grade bonds, private credit, equities and real estate. Third, duration against the liabilities: a long-tail insurer can hold longer bonds than a property insurer. A high yield from risky assets is not the same as a high yield from good underwriting.
Step 6: Estimate a sustainable return on equity
Return on equity for an insurer comes from underwriting profit plus investment income, less taxes, divided by equity. Build it from normalized parts: a normal combined ratio from Step 3, a forward investment yield from Step 5, a normal tax rate and the current premium-to-equity ratio. Compare the result with the reported ten-year average. If your normalized figure is far above the history, find the reason or lower it.
Step 7: Set a justified price-to-book multiple
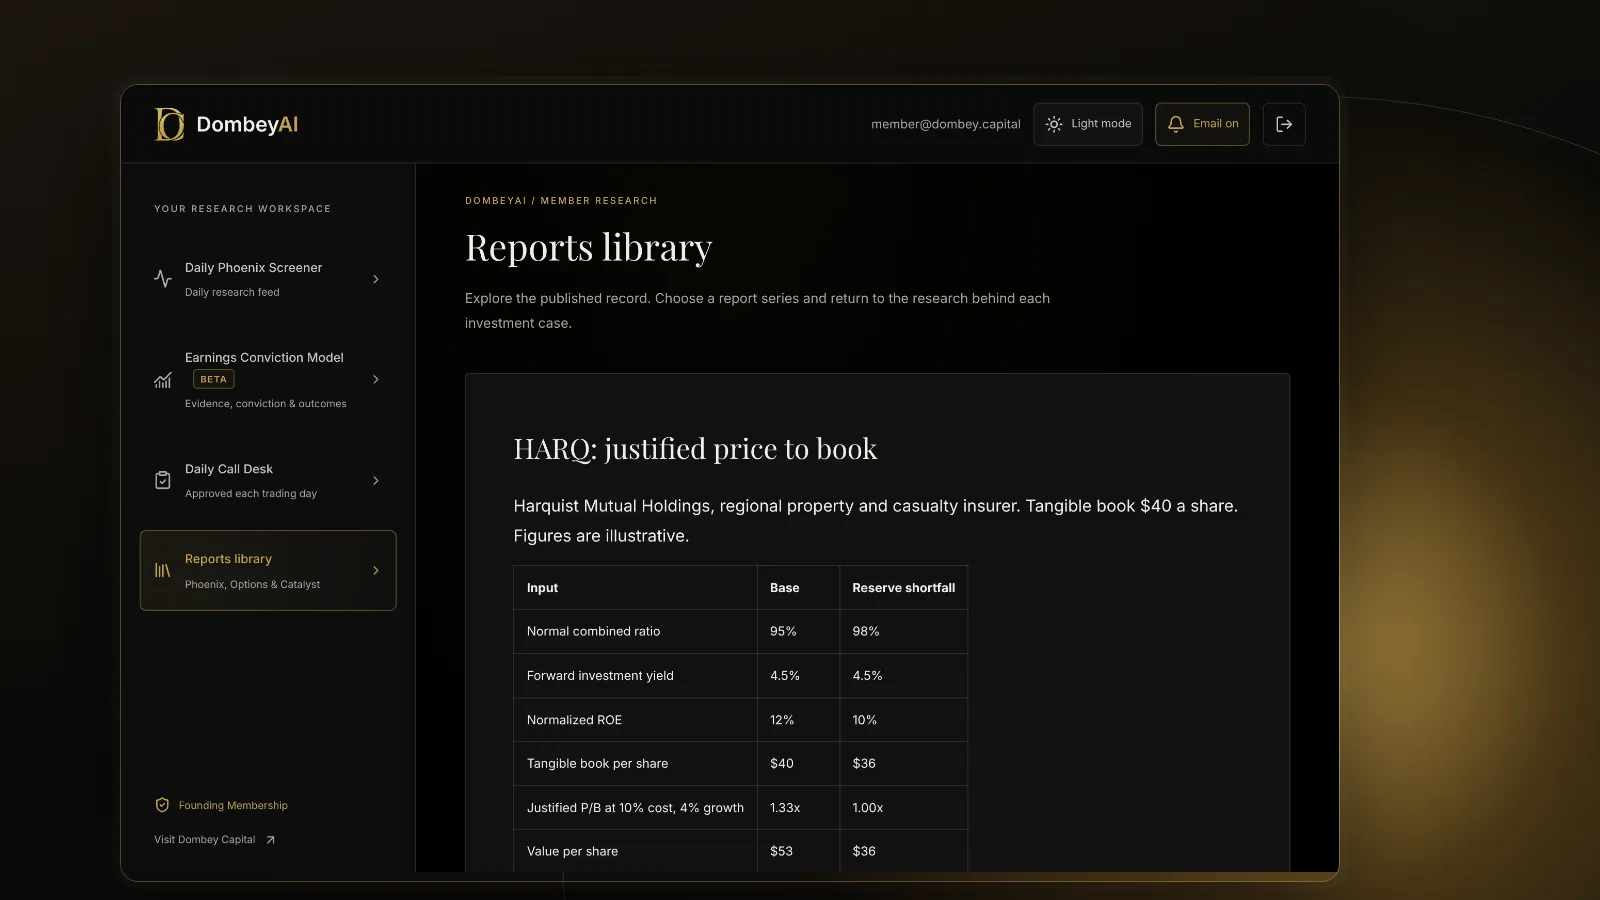
The justified price-to-book ratio links returns to value: (ROE minus growth) divided by (cost of equity minus growth).
The example shows why reserves matter twice: they reduce book value and they reduce the return on what is left.
Step 8: Cross-check capital, earnings and payouts
Check capital last. US insurance subsidiaries report risk-based capital to state regulators, and companies often disclose their ratios or targets. Thin capital limits growth and dividends and can force a capital raise. Then cross-check the valuation with a price-to-earnings multiple on normalized earnings and with the history of dividends and buybacks. An insurer that has grown book value per share plus dividends steadily for a decade has usually earned its returns.
A simple test ties these steps together: growth in book value per share plus dividends paid, measured over ten years, against the return on equity the company reported. If reported returns were 12% a year but book value plus dividends grew at 7%, something in between, such as reserve charges, investment losses or buybacks above book, absorbed the difference. Find it before relying on the reported figure.
For life insurers and mutual companies converting to stock form, see also our explainer on demutualizations, which often create insurers that trade below book at listing.
Common mistakes
- Reading one year's combined ratio. A light catastrophe year or a large reserve release can make a weak insurer look strong. Use normalized ratios.
- Taking book value at face value. Book value is only as good as the reserves behind it. Read the development table first.
- Counting investment risk as skill. A high portfolio yield from lower-quality credit adds return and risk together.
- Ignoring unrealized bond losses. They can cut book value sharply when rates rise. Know whether your book figure includes them.
- Applying bank or industrial multiples. Insurers have different capital rules and earnings drivers. Compare insurers with insurers writing similar lines.
The bottom line
Value an insurer on book value and the return it can sustain on it. Test the book with reserve development and the investment note, build a normalized return on equity from the combined ratio and investment yield, and convert it to a justified price-to-book multiple. Most valuation errors in insurance come from trusting reserves that later prove too low. For data sources that speed up this work, see our list of stock research tools for individual investors; Dombey's published valuation work is in the research archive.