

The formula
Rule of 40 score = revenue growth (%) + profit margin (%)
| Input | Common choices | Notes |
|---|---|---|
| Revenue growth | Year-over-year, trailing twelve months or latest quarter | Remove acquired revenue where possible |
| Profit margin | Free cash flow margin, adjusted EBITDA margin, operating margin | Use one measure consistently |
| Stock-based compensation | Excluded in most adjusted figures | A stricter version subtracts it |
| Period | Trailing or forward | Forward figures rely on guidance |
The logic is that a young software company can rationally spend heavily to grow, accepting losses, while a mature one should earn strong margins on slower growth. Adding the two treats a point of growth and a point of margin as roughly equal.
Worked examples
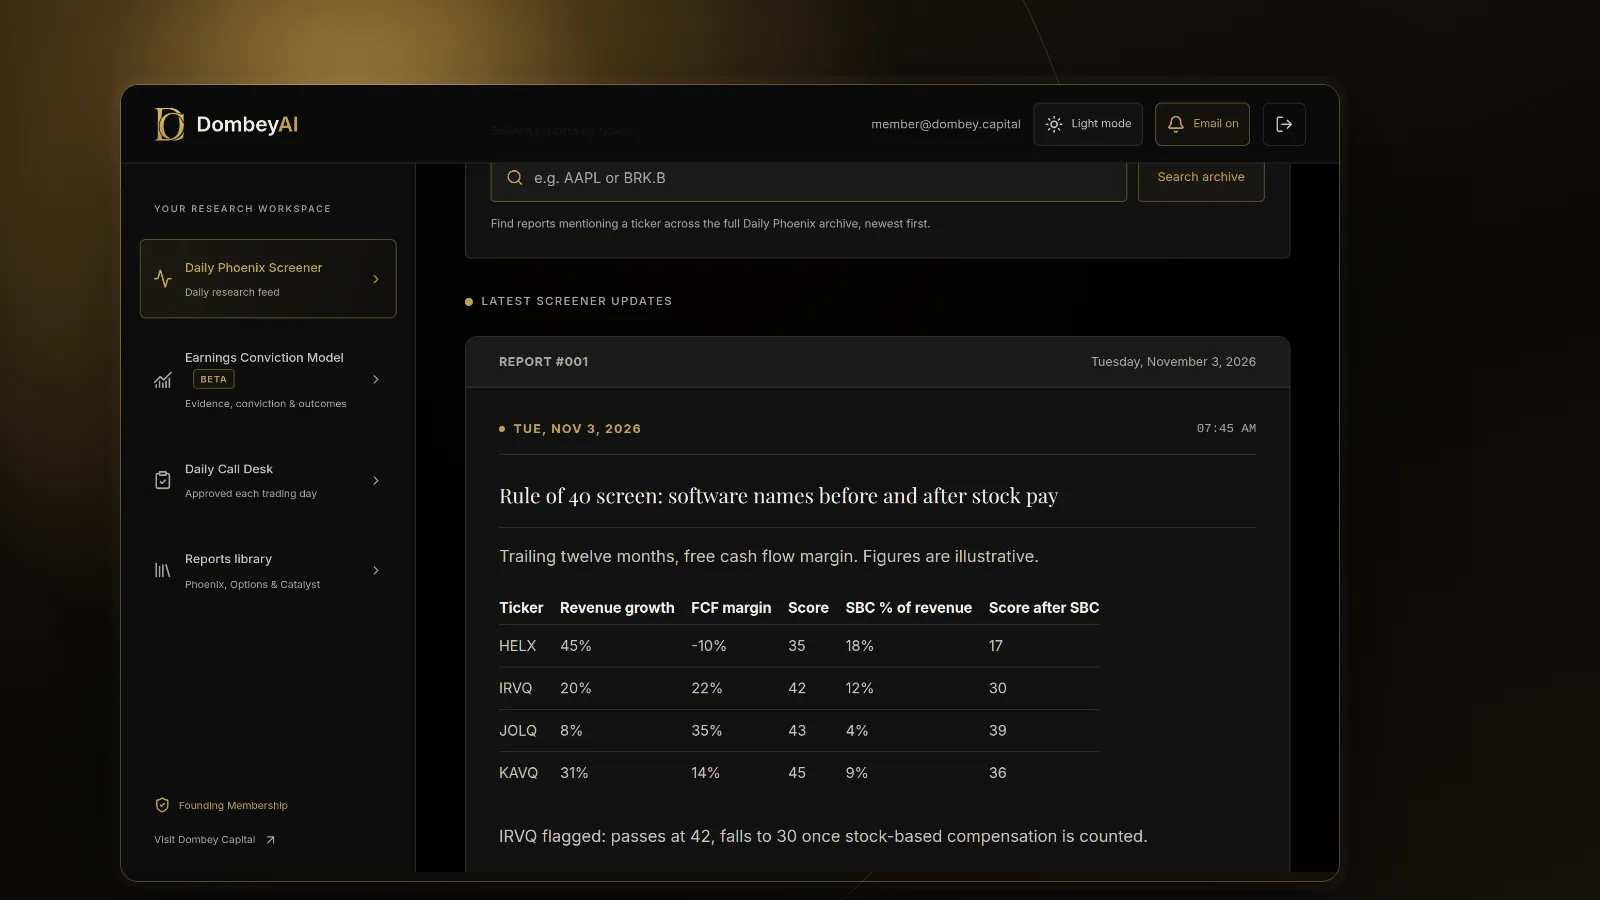
Now apply a stricter test. Suppose stock-based compensation is 18% of revenue at Company A, 12% at Company B and 4% at Company C. Subtracting it from the margin:
| Company | Growth | FCF margin | SBC % of revenue | Score | Score after SBC |
|---|---|---|---|---|---|
| A | 45% | -10% | 18% | 35 | 17 |
| B | 20% | 22% | 12% | 42 | 30 |
| C | 8% | 35% | 4% | 43 | 39 |
The ranking does not change, but the gap widens and only C comes close to 40 once the cost of share issuance is counted. Our explainer on whether stock-based compensation is a real expense covers the argument for subtracting it.
Which margin to use
Each choice has trade-offs.
- Free cash flow margin. Closest to cash the business generates. It can swing with billing terms: annual upfront billing pulls cash forward and flatters the margin in growth years.
- Adjusted EBITDA margin. Smoother, but it excludes items management chooses to exclude, often including stock-based compensation and capitalized software costs. Our explainer on adjusted EBITDA covers what usually gets removed.
- GAAP operating margin. The strictest and most comparable, and the hardest for loss-making growth companies to pass.
Tracking one company over time
The score is more useful as a trend than as a single reading. Here is how one company's profile might change as it matures.
| Year | Revenue growth | FCF margin | Score | What changed |
|---|---|---|---|---|
| Year 1 | 52% | -14% | 38 | Heavy sales hiring ahead of demand |
| Year 2 | 41% | -2% | 39 | Hiring slowed, renewals strong |
| Year 3 | 30% | 9% | 39 | Price increase, lower churn |
| Year 4 | 21% | 18% | 39 | Shift from growth to profit |
| Year 5 | 14% | 20% | 34 | Growth slows faster than margins rise |
The useful question each year is which half of the score is doing the work and whether the other half is improving fast enough to replace it.
How the Rule of 40 links to valuation
Software companies are often valued on revenue multiples, such as enterprise value to sales, because many have little profit. Investors have used the Rule of 40 score to explain why some companies earn higher multiples than others: a business that combines growth and margins generates more value per dollar of revenue.
A practical way to use it is in a comparable company analysis: plot each peer's enterprise value to revenue against its Rule of 40 score. Companies well below the line for their score may be cheap; those well above it may already price in a lot. As with any comparison, the result depends on the peers being priced sensibly.
When the score changes
The score is most useful as a trend. Watch how it moves around events:
- If growth slows and margins do not rise, the score falls and the multiple usually follows.
- If a company cuts costs after a growth slowdown, the score can hold steady while the business shifts from growth to profit.
- If an acquisition lifts growth, check organic growth before crediting the score.
- If guidance changes, a forward score shows where management expects the business to go. Our explainer on guidance changes covers how the market reacts.
For loss-making companies with low scores, the more pressing question may be funding. Our guide on how to estimate cash runway shows how long the cash lasts at the current burn.
How to read a score
- If the score is above 40 with GAAP operating margin, the business is strong on the strictest measure, and the remaining question is price.
- If the score passes only on adjusted EBITDA, recompute it with free cash flow and stock-based compensation before relying on it.
- If the score is below 40 but rising each year, the company may be on track, so check whether growth or margin is driving the gain.
- If the score is falling while the company calls itself profitable, growth is slowing faster than costs are being cut.
- If revenue growth includes a large acquisition, rebuild the score on organic growth before comparing it with peers.
What the Rule of 40 leaves out
- Quality of growth. Growth bought with heavy discounts, long free trials or high customer churn counts the same as durable growth.
- Customer acquisition cost. Two companies can grow at the same rate with very different sales and marketing spending per dollar of new revenue.
- Gross margin. A company with a 60% gross margin and one with 85% can score the same while having very different long-term profit potential.
- Dilution. Share issuance lowers per-share value even when the company-level score looks strong.
- Balance sheet. Net cash or net debt does not enter the formula.
- Price. The score says nothing about what the market already expects. Compare it with free cash flow yield and the revenue multiple.
Where this goes wrong
- Mixing definitions across companies. Comparing one company's EBITDA-based score with another's free cash flow score is meaningless.
- Using a single quarter. Seasonal billing can swing quarterly free cash flow; use trailing twelve months.
- Treating 40 as a hard line. A score of 38 and one of 42 describe similar businesses.
- Applying it outside software. Low-gross-margin businesses rarely fit the framework.
- Forgetting the price. A high score at a high multiple can still be a poor investment.
For tools that calculate these inputs, see our list of the best stock research tools for individual investors. Dombey's research looks at the score alongside the balance sheet and valuation when software companies come up in coverage; see the research archive.
The bottom line
The Rule of 40 adds a software company's revenue growth rate and profit margin and treats 40% as the mark of a healthy balance between the two. It is useful for comparing companies at different stages and for explaining why some trade at higher revenue multiples. The score depends heavily on which margin you use and whether you count stock-based compensation, so define it consistently. Use it to describe the business, then judge the price separately.