

The formulas
There are three common versions.
Earnings payout ratio = dividends per share ÷ earnings per share or total dividends ÷ net income
Cash flow payout ratio = total dividends ÷ free cash flow where free cash flow is operating cash flow minus capital spending
Retention ratio = 1 − earnings payout ratio the share of profit kept in the business
Use trailing twelve-month figures for both the dividend and the earnings or cash flow. If the company has just raised its dividend, use the new annual rate against forward earnings as well, since the trailing ratio will understate what it now pays.
What the ratio tells you
The payout ratio answers two questions at once: how much room the dividend has to absorb a bad year, and how much profit is left to fund growth.
| Payout ratio | Usual reading | Common in |
|---|---|---|
| 0% | No dividend | Growth companies, companies preferring buybacks |
| 1% to 30% | Low; large cushion and reinvestment | Technology, early dividend payers, cyclicals at peak |
| 30% to 60% | Moderate; room for bad years | Many industrial, healthcare and consumer companies |
| 60% to 80% | High; little cushion | Utilities, telecoms, mature consumer staples |
| 80% to 100% | Very high; vulnerable to an earnings dip | Mature or declining businesses, companies after an earnings drop |
| Above 100% | Paying more than earned | Temporary earnings dips, or a dividend under pressure |
These are rough bands, not rules. A regulated utility with predictable earnings can sustain a 70% payout. A steel maker at 50% of peak earnings may have to cut when the cycle turns, because its earnings can fall by more than half.
Why the cash flow version matters
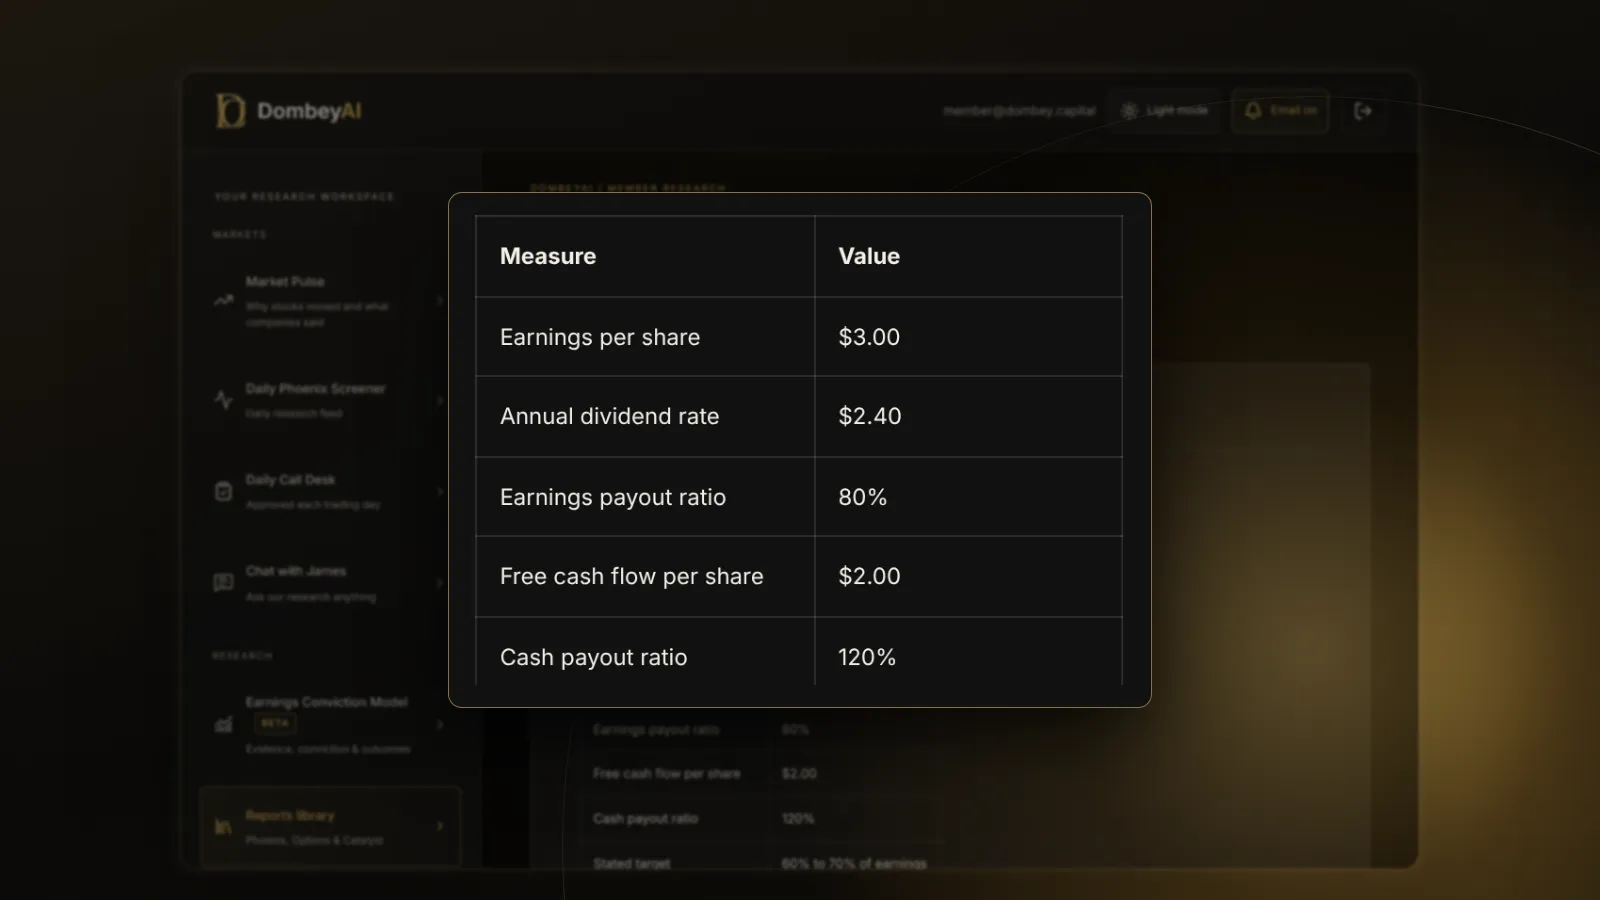
Earnings are an accounting figure. They include non-cash charges such as depreciation, amortization and impairments, and they ignore capital spending and changes in working capital. A company can report solid earnings and still not generate the cash to pay its dividend, or the reverse.
On earnings alone, Company B looks stretched and Company A looks safe. The cash flow figures say the opposite. Our explainer on free cash flow yield shows how to build the free cash flow figure.
Dividends, buybacks and total payout
Many companies return cash through buybacks as well as dividends. A company with a 25% dividend payout ratio and buybacks equal to 50% of earnings returns 75% of its profit to shareholders.
The total payout ratio, dividends plus net buybacks divided by earnings, captures this. It ties to shareholder yield, which measures the same return against market value. Buybacks are more flexible than dividends: companies cut them quietly in a bad year, while a dividend cut is announced and usually punished by the market.
Payout ratio and growth
The retention ratio links the dividend to growth. A common shortcut is:
Sustainable growth rate ≈ return on equity × retention ratio
A company with a 15% return on equity that retains 60% of earnings can, in principle, grow earnings about 9% a year without new capital or more leverage. One that pays out 90% can grow only about 1.5% on the same return. This is the logic behind the dividend discount model: a higher payout today means slower growth in future dividends, unless returns on reinvested capital are low.
A high payout ratio is not a flaw for a business with few good places to reinvest. It is a problem only when the payout is high and the business needs capital to stay competitive.
Special cases: REITs, MLPs and banks
Some business types need their own measures.
- REITs. Depreciation on property depresses net income, and US REITs must distribute at least 90% of taxable income to keep their tax status. Payout ratios on net income often exceed 100%. Investors use funds from operations (FFO) or adjusted FFO instead.
- MLPs and other partnerships. Distributions are measured against distributable cash flow, and the inverse, coverage, is quoted: 1.2x coverage means the partnership earned 1.2 times its distribution.
- Banks and insurers. Regulators set capital requirements that limit payouts, and stress test results can change how much a bank may distribute.
- Holding companies. Dividends may depend on what subsidiaries can pass up, not on consolidated earnings.
Payout ratios as catalysts
Changes in dividend policy are dated events. An initiation, covered in dividend initiations, often follows a period of rising free cash flow and a falling payout ratio on a hypothetical dividend. A cut, covered in what dividend cuts signal, usually follows a long stretch with the payout ratio above 100% on both earnings and cash. A special dividend often follows an asset sale or a year of unusually high cash.
How to check a payout ratio in practice
A quick routine covers most cases:
- Take the current annual dividend rate, not last year's total, if the dividend was just raised or cut.
- Divide it by trailing earnings per share, then by consensus forward earnings per share.
- Divide total dividends paid, from the cash flow statement, by free cash flow for the same period.
- Repeat steps 2 and 3 for the last five years to see the trend across good and bad years.
- Read the earnings release or investor presentation for a stated payout target, such as "40% to 60% of adjusted earnings".
- Check net debt over the same five years to see whether borrowing has been filling the gap.
If the earnings and cash ratios agree and sit inside the company's own target, the dividend is usually on solid footing. If they diverge, the explanation is in the cash flow statement.
Where this goes wrong
The payout ratio is easy to compute and easy to misread.
- One-off earnings. An impairment or a gain on sale distorts net income for a year. Use adjusted or normalized earnings alongside the reported figure.
- Cyclical peaks. A low payout on peak earnings can turn into a high payout on trough earnings. Check the ratio across a full cycle.
- Ignoring capital needs. A business that underinvests to keep paying the dividend can look safe until competitors pull ahead.
- Debt-funded dividends. A stable ratio can hide rising borrowing. Watch net debt alongside the payout.
- Wrong measure for the structure. Using net income for a REIT or an MLP makes almost every dividend look unsustainable.
- Currency and tax effects. For foreign companies, dividends and earnings may be in different currencies or subject to withholding tax, which changes what reaches the shareholder.
The bottom line
The dividend payout ratio is dividends divided by earnings, and it shows how much of profit a company pays out and how much it keeps. Check it against free cash flow as well as earnings, since cash is what pays the dividend. A sustainable level depends on how steady the business is and how much it needs to reinvest, and pass-through structures need their own measures. Most of the platforms in our list of the best stock research tools for individual investors show payout ratios, and the best dividend stock research tools add history and coverage data.