

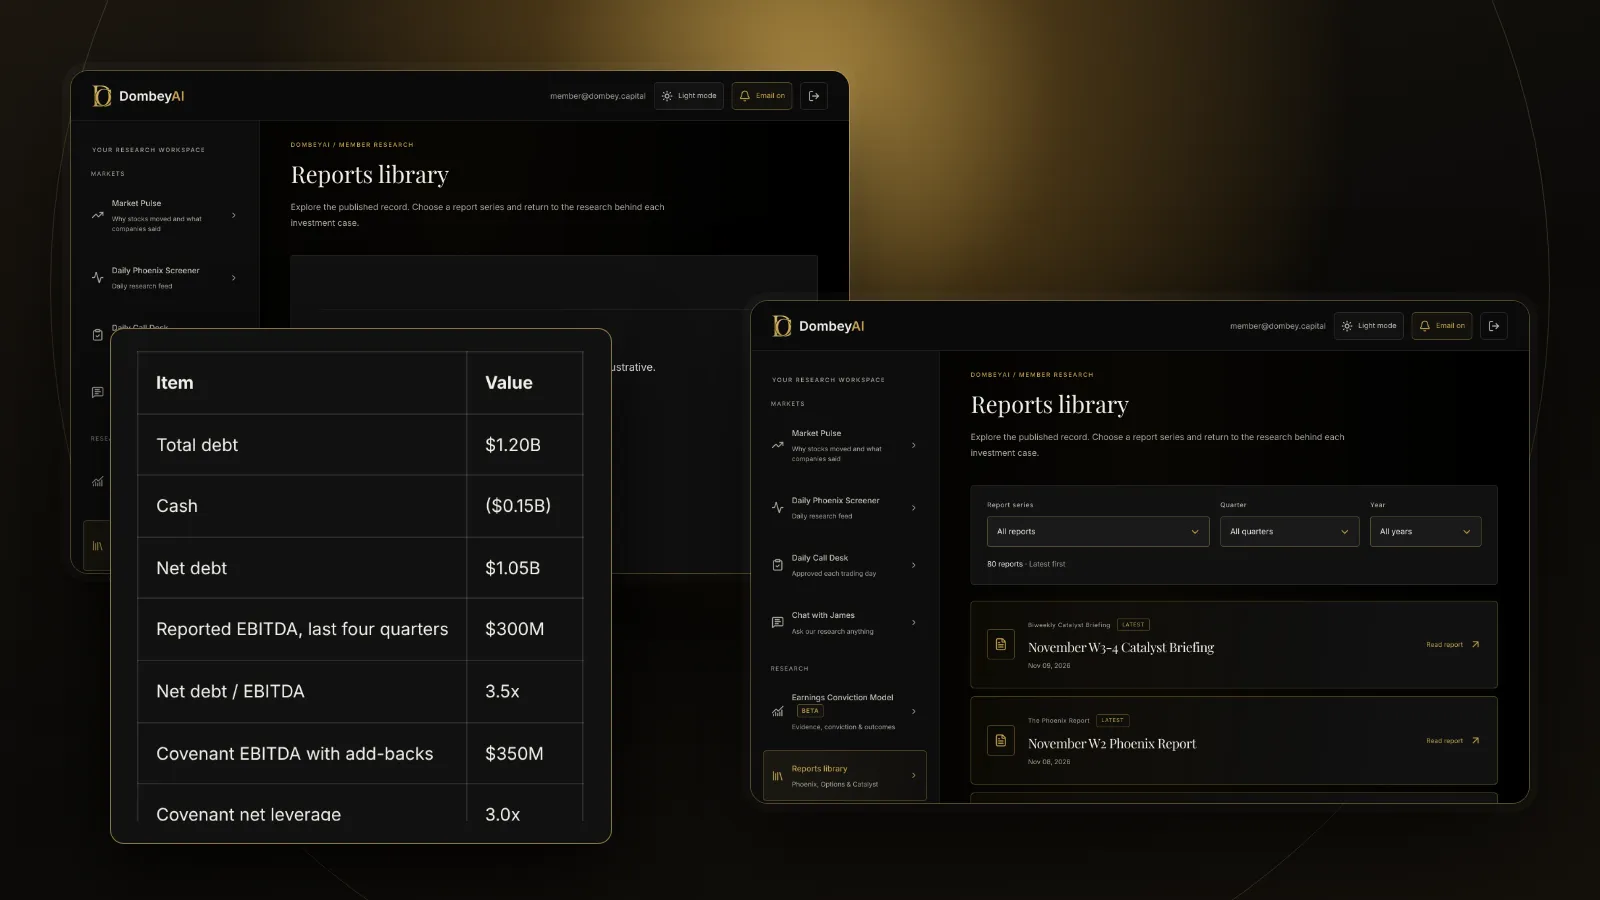
The formula
The calculation has two parts.
Net debt = short-term debt + current portion of long-term debt + long-term debt − cash and cash equivalents
Net debt to EBITDA = net debt ÷ trailing twelve-month EBITDA
EBITDA is operating income plus depreciation and amortization. Use the last four quarters added together rather than the last full fiscal year if the year ended some months ago, and take the debt and cash from the same balance sheet date.
Some analysts also subtract short-term investments that are as liquid as cash. Others add lease liabilities, preferred stock or underfunded pensions to debt. There is no single standard, which is why two sources can show different ratios for the same company. Whatever you choose, apply it the same way across the companies you compare.
How to read the result
The ratio is a quick gauge of how much a company owes relative to what it earns before interest, taxes and capital spending. As a rough guide:
| Net debt to EBITDA | Usual reading | Typical context |
|---|---|---|
| Below 0x (net cash) | No net leverage | Cash-rich companies, see net cash per share |
| 0x to 1x | Low | Conservative balance sheets, cyclical companies at peak |
| 1x to 3x | Moderate | Many steady industrial, consumer and healthcare companies |
| 3x to 4x | Elevated | Companies after an acquisition, stable businesses with long contracts |
| 4x to 6x | High | Leveraged buyouts, high-yield issuers, towers and utilities with stable cash |
| Above 6x | Very high | Distressed or heavily structured balance sheets |
These ranges are a starting point. A water utility with regulated returns can carry 5x safely. A semiconductor company at 3x can be in trouble if a downturn halves its EBITDA. The question is always how far EBITDA could fall and whether the debt comes due before it recovers.
A worked example
The example shows why the ratio matters most when earnings fall. Debt stays fixed while EBITDA moves, so leverage rises fastest for the companies that already carry the most.
Where the ratio fits among other measures
Net debt to EBITDA is one of several ways to look at leverage, and each answers a different question.
- Interest coverage asks whether earnings cover interest payments this year. Our guide to the interest coverage ratio explains the calculation.
- Debt to equity compares debt with book equity, which can be distorted by buybacks or write-downs. See debt to equity explained.
- EV to EBITDA uses net debt as part of enterprise value to price the whole business. The EV/EBITDA explainer covers how leverage changes that multiple.
- Maturity profile shows when the debt is due, which matters as much as how much there is. A company at 3x with everything due next year is riskier than one at 4x with maturities spread over a decade, as covered in what a debt maturity wall is.
Read them together. A company with low net debt to EBITDA but weak interest coverage may be paying a high rate, and a company with moderate leverage but a large maturity next year faces refinancing risk.
The covenant version is different
Most bank loans and many bond indentures include a leverage test, often called the total net leverage ratio. The idea is the same, but the definitions are set by the credit agreement, not by accounting rules.
Covenant EBITDA, often called Consolidated EBITDA, usually allows add-backs that reported EBITDA does not: restructuring charges, expected cost savings from acquisitions, stock-based compensation and other items. Some agreements allow pro forma savings that have not happened yet. The result can be a covenant leverage ratio well below the figure you calculate from the income statement.
This matters in two ways. First, a company can report covenant compliance while its reported leverage looks high, so do not assume a default is near because your calculation exceeds the limit. Second, when even covenant leverage is near the limit, the company may need an amendment, an equity raise or an asset sale. Those are dated events, and they often appear first in an 8-K or the debt footnote of a 10-Q. Our guide to adjusted EBITDA shows how add-backs build up.
Where this goes wrong
Net debt to EBITDA is simple, which is its strength and its weakness.
- Falling EBITDA. The ratio uses trailing earnings. If EBITDA is declining, today's 3x can be next year's 5x with no new borrowing.
- Trapped or restricted cash. Cash held overseas, in a regulated subsidiary or as collateral may not be available to repay debt. Subtracting it understates leverage.
- Debt left out. Leases, pensions, preferred stock, guarantees and off-balance-sheet obligations can be large. The ratio ignores anything you leave out of the numerator.
- EBITDA is not cash. A company with heavy capital spending, rising working capital or large cash taxes may convert little of its EBITDA into cash that can repay debt.
- Seasonal balance sheets. Retailers and others borrow and repay through the year. A quarter-end snapshot can flatter or exaggerate leverage.
- Mismatched dates. Using debt from after an acquisition with EBITDA from before it, or the reverse, distorts the ratio in either direction.
How investors use it in special situations
In event-driven work, net debt to EBITDA often signals where the next event will come from. A company above its covenant limit may need a waiver. A company near investment-grade thresholds may face a downgrade, the path described in what a fallen angel is. A company that has just sold a division may fall from 4x to 1x overnight, which can free it to buy back stock or pay a special dividend.
The useful habit is to track the ratio over time and against the company's own target, which many management teams state in earnings releases and investor presentations. A company that says it targets 2x to 2.5x and sits at 3.5x is telling you what it plans to do with its cash.
Most of the data platforms in our list of the best stock research tools for individual investors show net debt and EBITDA, though their definitions differ. Check their figures against the filing before relying on them.
The bottom line
Net debt to EBITDA divides debt minus cash by a year of EBITDA, and reads as years of earnings needed to repay net borrowings. It is a fast first check on leverage, best used alongside interest coverage, the maturity schedule and the covenant definition in the credit agreement. The ratio says the most when EBITDA is under pressure, because that is when leverage rises without any new debt. Always check what was included in debt and EBITDA before comparing one company's figure with another's.