

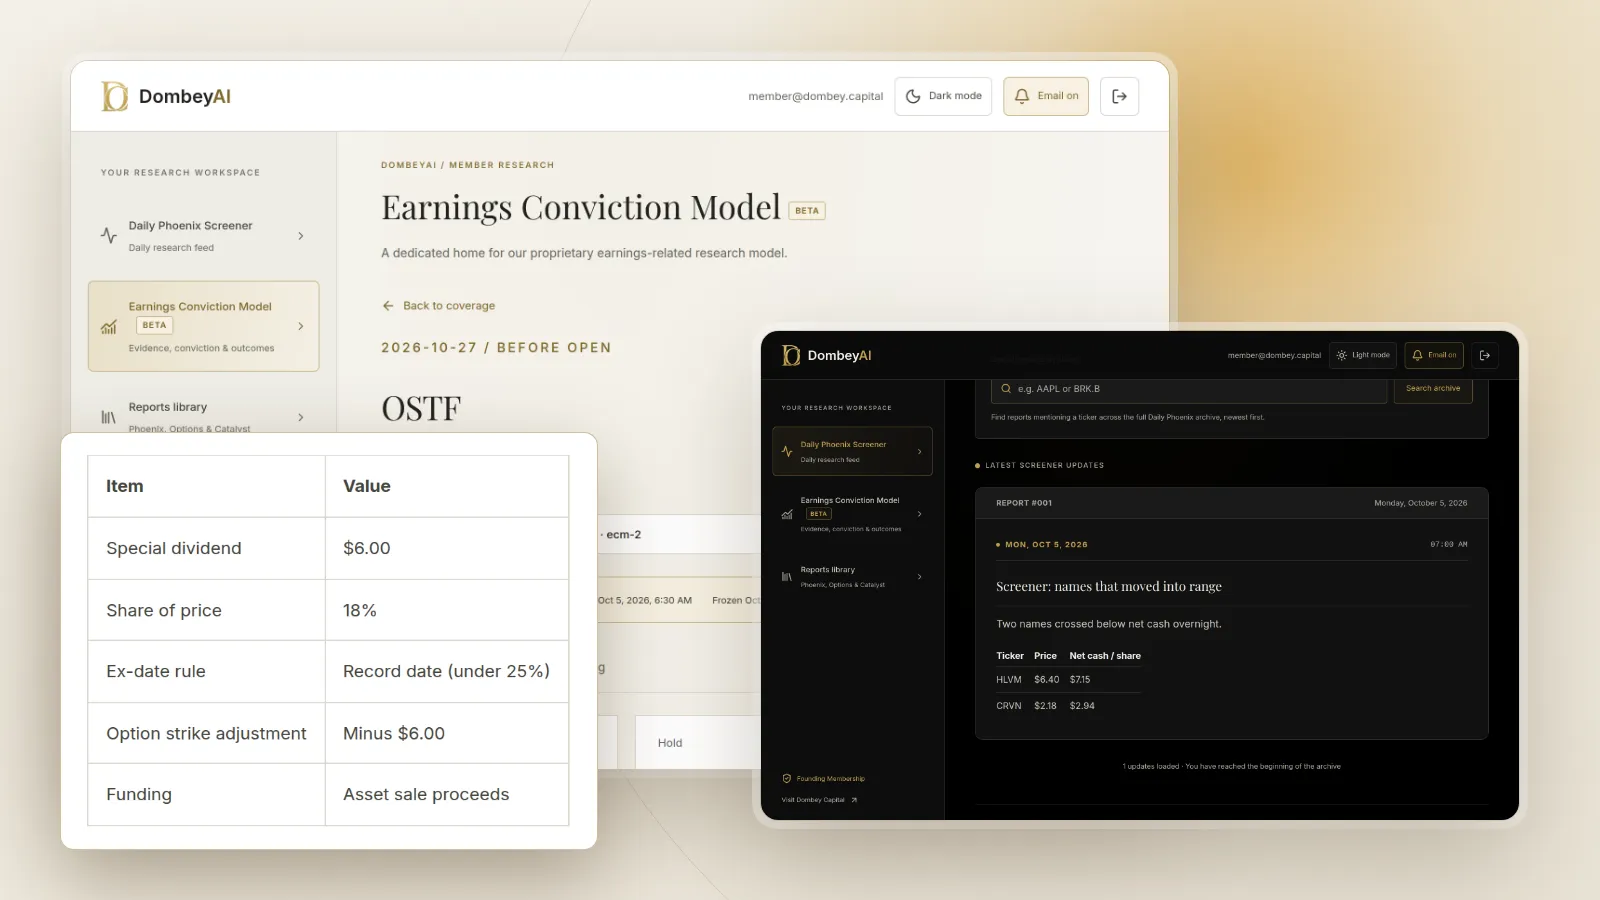
How a special dividend differs from a regular one
A regular dividend is paid on a schedule under a stated policy, often quarterly. The market expects it and prices it in. A special dividend is declared once, for a stated amount, and the board makes no promise to repeat it. Companies sometimes label it "special," "extra" or "one-time" so investors do not treat it as a new run rate.
Common sources of the cash:
- An asset sale. A company sells a division and returns the proceeds.
- Excess cash build-up. Years of profits accumulate beyond what the business needs.
- A recapitalization. The company borrows and pays the proceeds out, raising leverage.
- The end of a wind-down. A company selling its assets pays out cash in stages, which overlaps with the liquidation play.
For event-driven investors, a declared special dividend is one of the clearer catalysts. The amount is fixed, the dates are set, and the board has committed. The earlier piece on hard vs soft catalysts puts a declared special dividend with a record date on the hard side for that reason.
The four dates that matter
| Date | What it means | Who sets it |
|---|---|---|
| Declaration date | The board announces the amount, record date and payable date | The board |
| Record date | Holders on the company's books on this date are entitled to the payment | The board |
| Ex-dividend date | First day the stock trades without the right to the payment | Exchange and FINRA rules |
| Payable date | The cash is paid | The board |
For most dividends, FINRA Rule 11140 sets the ex-dividend date as the record date, when the record date is a business day. With trades settling one business day after the trade date, a buyer on the record date would not settle in time to be on the books, so the stock trades ex-dividend that day.
Large distributions work differently. When a cash dividend, stock dividend or split is worth 25% or more of the value of the stock, Rule 11140 sets the ex-dividend date as the first business day after the payable date. Until then, the right to the payment travels with the shares. A holder who sells after the record date but before the ex-date has to pass the dividend on to the buyer, usually through a due bill handled by the brokers.
What happens to the share price
On the ex-dividend date, the stock opens without the right to the cash, so the price adjusts down by roughly the dividend. If nothing else changed, a holder has the same total value before and after: part of it now sits in a brokerage account as cash.
The adjustment is rarely exact, because other news and trading move the price on the same day. But the starting point is clear, and it means a special dividend does not create value on its own. It moves value from the company's balance sheet to the holders' accounts.
Where value can change is in what the market thinks of the remaining company:
- If the cash was idle and earning little, paying it out can narrow a discount the market applied to it. This is the case for companies trading near net cash per share or with negative enterprise value.
- If the dividend is funded with new debt, the remaining equity is more leveraged and more sensitive to bad results.
- If the payout signals that management has no better use for the cash, the market may lower the multiple it pays for growth.
Enterprise value falls by the cash paid out when the dividend comes from the balance sheet. Ratios that use the share price, such as price to book, change on the ex-date even though the business has not. For how the cash line feeds into those measures, see what enterprise value is.
How a special dividend is taxed
For a U.S. individual holder, the special label makes no difference to the tax rules. The payment is treated like any other corporate distribution, in three layers.
- Dividend, to the extent of earnings and profits. IRS Publication 550 says ordinary dividends are paid out of earnings and profits and are ordinary income. Earnings and profits is a tax measure, not the same as retained earnings on the balance sheet.
- Return of basis, for any excess. The part of the distribution above earnings and profits is a nondividend distribution. It is not taxed when received. It reduces your cost basis in the shares instead.
- Capital gain, once basis reaches zero. After basis is fully recovered, any further nondividend distribution is reported as a capital gain.
The company reports the split on Form 1099-DIV: box 1a for total ordinary dividends, box 1b for the qualified portion, and box 3 for nondividend distributions. The split is often not known when the dividend is paid, because it depends on the company's earnings and profits for the full tax year.
Qualified or ordinary
The dividend portion is taxed at the lower long-term capital gain rates, 0%, 15% or 20% depending on taxable income, only if it is qualified. One test is the holding period: you must have held the shares for more than 60 days during the 121-day period that begins 60 days before the ex-dividend date. You count the day you sold but not the day you bought. Fail the test and the dividend is taxed at ordinary income rates. Individuals with significant investment income may also owe the net investment income tax.
This is general information, not tax advice. Corporate holders, foreign holders and tax-advantaged accounts follow different rules.
Worked example
Change one input and the dates shift. If Company A had declared $12 per share, 30% of the price, the ex-date would move to the first business day after the 28th. The stock would keep trading with the dividend attached for two more weeks, and the price drop would come after the cash was paid.
A second investor bought 1,000 shares of Company A ten days before the ex-date and sold them 20 days after it. Held about 30 days, the shares fail the 61-day test. The $5 per share dividend portion is taxed as ordinary income. The sale near $32 against a $40 cost, adjusted down by the $3 basis reduction, produces a short-term capital loss of about $5 per share. The pre-tax result is close to zero; the after-tax result depends on how those two items offset on the investor's return.
What happens to options
Option holders do not receive dividends, so a large payout would cut the value of calls and raise the value of puts if contracts were left alone. The Options Clearing Corporation handles this through its adjustment rules in Article VI, Section 11A of its By-Laws.
- Ordinary dividends are generally not adjusted for. A dividend paid under a regular quarterly or similar policy is treated as ordinary, and option prices already reflect it.
- Small special dividends are generally not adjusted for. A cash dividend below $0.125 per share, or $12.50 per contract for contracts originally listed with a larger unit, is generally left alone.
- Larger non-ordinary dividends generally lead to an adjustment. The usual method is to reduce the strike price by the dividend per share. The OCC can instead add the cash to the contract's deliverable.
In the example above, a Company A call with a $40 strike would generally become a $32 strike call on the ex-date. Check the OCC information memo for the actual terms, because the OCC decides each case and nonstandard contracts can be treated differently. A position that looks like a gain or a loss on the ex-date may simply reflect the adjustment. The option chain guide explains how adjusted series appear, and the covered call piece covers how short calls behave around events.
Where this goes wrong
Treating the dividend as a gain. The cash comes out of the share price. A holder who sees $8 arrive and the stock still at $40 should look for another reason the price held, not count the dividend as profit.
Using the record date for a large payout. For distributions of 25% or more of the price, the ex-date follows the payable date. Selling between the record date and the ex-date passes the cash to the buyer.
Assuming it is all a dividend. Part of the payment may be a nondividend distribution. If you ignore box 3 and keep your old basis, you will overstate your basis and understate your gain when you sell.
Assuming it is qualified. Short holding periods around the ex-date are the common way to lose the lower rate.
Missing the leverage. A special dividend funded by new borrowing leaves a smaller, more indebted equity. Check the debt terms and the maturity schedule before treating the payout as good news.
Expecting a repeat. A one-time payment does not set a yield. Screens that annualize the last dividend will show a yield that will not recur.
How to check a declared special dividend
| Step | What to check | Where to find it |
|---|---|---|
| 1 | Amount, record date, payable date | Press release or 8-K; see how to read an 8-K |
| 2 | Size as a share of the price, under or over 25% | Amount divided by the current price |
| 3 | Ex-dividend date | Broker or exchange notice |
| 4 | Funding source: cash, asset sale or new debt | 8-K, latest 10-Q balance sheet and debt note |
| 5 | Expected dividend versus return-of-capital split | Company tax statements, then the 1099-DIV |
| 6 | Option adjustment terms | OCC information memo |
Dombey's published research tracks declared cash returns as dated catalysts where they form part of a thesis; see the research archive.
The bottom line
A special dividend is a one-time cash payment that moves value from the company to its holders, and the share price falls by roughly the payout on the ex-date. For payments of 25% or more of the share price, the ex-date comes after the payable date, which changes who keeps the cash. The payment is taxed as a dividend only up to the company's earnings and profits, and it is qualified only if the holding period is met; the rest reduces basis. Options are generally adjusted for larger non-ordinary payouts, usually by lowering the strike. Check the dates, the funding and the 1099-DIV split before you count the cash.