

Nov 11, 2026: a 12% drop on a per-share miss
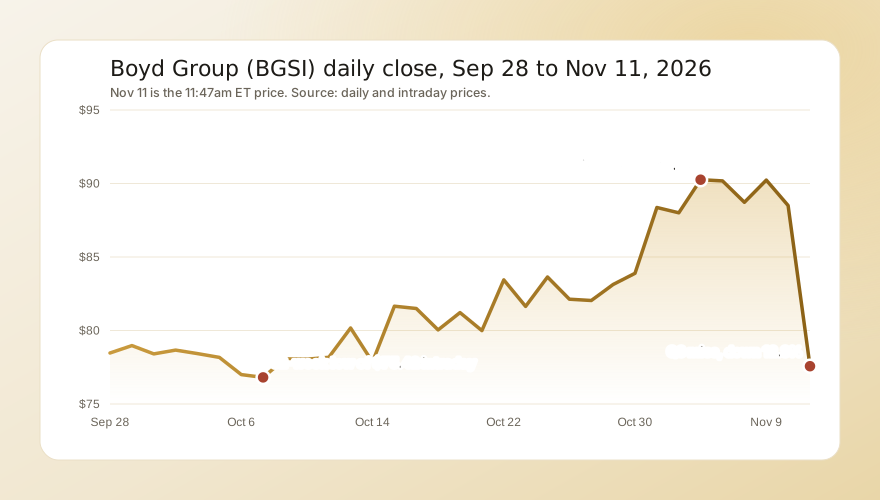
Boyd closed Nov 10 at $88.50, near the top of the range it had climbed through since its Oct 7 low, after a run from $78.17 on Oct 5 to a $90.26 close on Nov 4. The release came at 6am. The only premarket trades were at $84.00 to $84.50 around 9:10am. The stock opened at $78.50, already 11.3% lower, set its low of $76.32 at 10am and traded at $77.57 at 11:47am, down 12.3%. The New York line is thin: about 65,000 shares had traded by then, and Boyd's main listing is in Toronto.
What pushed it down:
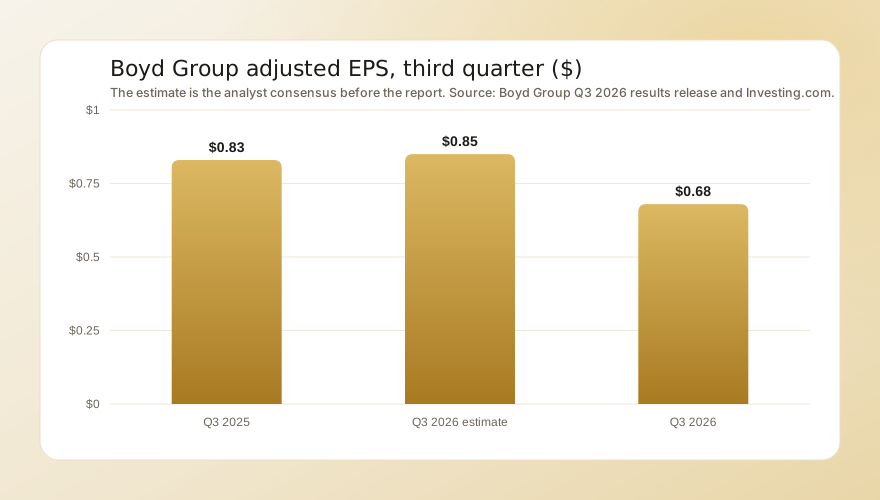
- Earnings per share missed. Adjusted EPS of $0.68 compared with about $0.85 expected, Investing.com reported, and with $0.83 a year earlier. Net earnings were $0.1 million, against $10.8 million a year earlier, after $7.0 million of acquisition and transformation costs.
- Costs below EBITDA rose faster than profit. Finance costs were $32.3 million, up from $18.8 million. Depreciation of property, right-of-use assets and intangibles came to about $88.5 million, up from $61.4 million. The weighted average share count rose to 27.8 million from 21.5 million.
- The industry is shrinking. Boyd estimates repairable claims volumes fell about 1% to 3% from a year earlier. Chief executive Brian Kaner tied much of the decline to fewer miles driven over the summer, and said total losses, cars written off rather than repaired, have not yet declined.
- A slower margin path. Management kept the 14% adjusted EBITDA margin target but said progress toward it would be more gradual.
Peers fell far less. At 11:47am:
| Stock or fund | Change from Nov 10 close |
|---|---|
| Boyd Group (BGSI) | -12.3% |
| LKQ (LKQ) | -2.8% |
| Driven Brands (DRVN) | -2.4% |
| Copart (CPRT) | -1.4% |
| iShares Russell 2000 ETF (IWM) | +0.8% |
| SPDR S&P 500 ETF (SPY) | +1.2% |
LKQ sells replacement parts to collision shops and Copart auctions written-off cars, so both depend on the same claim counts. Their small declines say the market read the miss as Boyd's own. Our earlier page on why LKQ fell covers the parts side of the same industry, and the rest of the session's movers are in today's biggest stock moves.
After the drop, RSI(14) stood at 38, the shares sat 6% below their 50-day average and 30% below their 200-day average, and the stock was 58% below its 52-week high of $183.10, set on Feb 11.
The numbers
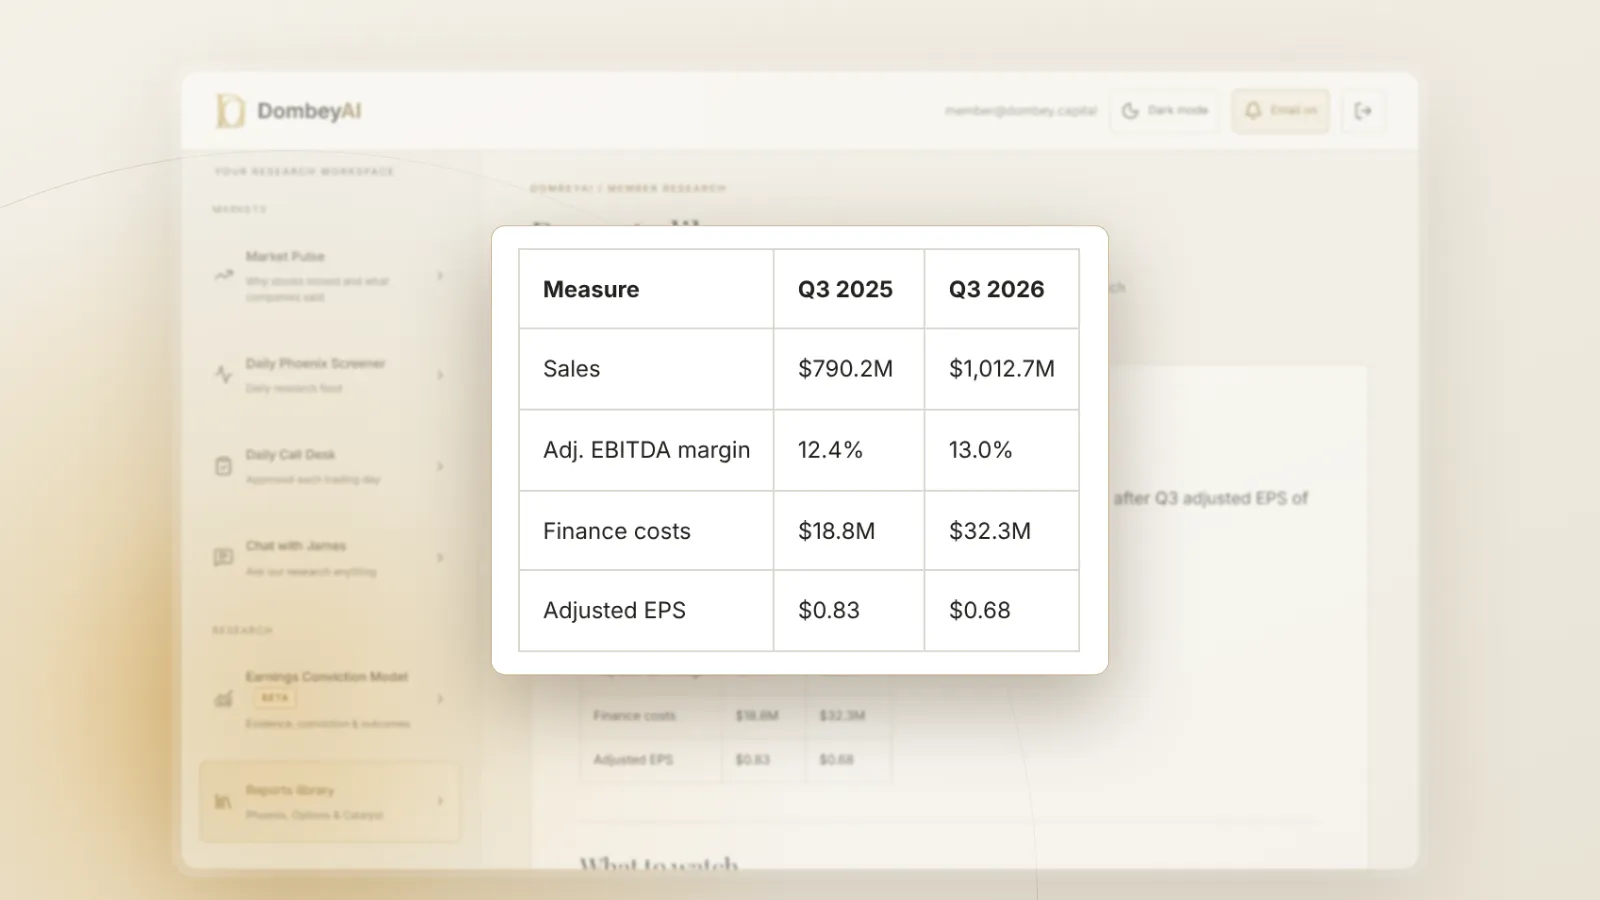
The quarter, which ended Sept. 30, in U.S. dollars:
| Measure | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Sales | $790.2M | $1,012.7M | Up 28.2% |
| Same-store sales, excluding currency | Up 2.2% | ||
| Adjusted EBITDA | $98.4M | $132.1M | Up 34% |
| Adjusted EBITDA margin | 12.4% | 13.0% | Up 0.6 points |
| Finance costs | $18.8M | $32.3M | Up 72% |
| Adjusted net earnings | $17.8M | $19.0M | Up 6% |
| Adjusted EPS | $0.83 | $0.68 | Down 18% |
| Collision locations | 1,014 | 1,329 | Up 31% |
Joe Hudson's locations contributed about $170 million of sales in the quarter, and management said that business improved against the prior year as the quarter went on. Adjusted net earnings rose 6%, but per-share earnings fell because there are 30% more shares. Our explainer on dilution and share count changes covers why a larger company can still earn less per share, and what adjusted EBITDA leaves out covers the gap between the 34% and the minus 18%.
The bull case
Boyd is winning share in a shrinking market. Same-store sales grew 2.2% while claims fell, and gross margin rose to 46.7% from 46.3%. Its Project 360 cost program, together with savings from integrating acquired shops, delivered $50 million this year through September and is set to add $15 million more in the fourth quarter, with $35 million still to come between 2027 and 2029. The company plans 34 new start-up locations over the next 12 months, 11 of them in the fourth quarter. Leverage is falling, and the buyback gives the company a way to use cash at a price 58% below the February high. At about 10 times trailing EBITDA on an enterprise value near $4.2 billion, the stock is priced for little growth.
The risks
- Estimates may fall further. A miss this size usually brings estimate cuts, and our guide to why estimate revisions move stocks covers why the cuts can matter more than the miss.
- Fewer claims. If miles driven stay low and more damaged cars are written off, the pool of repairable claims keeps shrinking. Boyd can gain share for a while, but not forever against a falling total.
- Debt costs. Finance costs are now about $32 million a quarter. Our explainer on net debt to EBITDA covers how to read the 2.9 times leverage figure.
- Integration. Joe Hudson's still has to reach Boyd's margins, and management named client scores and staffing as the work left to do.
What comes next
- Fourth-quarter results, which we expect around March 18, 2027. Watch same-store sales against the 2.2% of the third quarter, the margin against 13.0%, and whether finance costs level off.
- Claims data. Any sign that repairable claims stop falling would be the clearest support for the bull case.
- Buybacks. The size of repurchases in the fourth quarter will show how much management backs the stock at these prices.
Our guide to reading an earnings release covers how to work through a report like this one, and how to analyze an earnings call transcript covers the call.