

Why expensing R&D distorts the numbers
When a manufacturer builds a plant, the cost goes on the balance sheet and is depreciated over many years. When a software company spends the same amount writing code that will earn revenue for years, the cost is expensed immediately. Two companies investing the same amount in future growth report very different earnings and very different invested capital.
The distortion runs in a predictable direction:
- Growing R&D understates earnings. This year's spending, which mostly benefits future years, is charged in full today.
- Invested capital is understated. The balance sheet carries none of the accumulated research asset, so return on capital is overstated for companies whose R&D has stopped growing.
- Margins are not comparable. A company that cuts R&D looks more profitable immediately, even if it is damaging its future.
Our explainers on return on invested capital and economic value added show why invested capital matters as much as earnings.
What the accounting rules allow
Under US GAAP, research and development costs are generally expensed as incurred. Exceptions include some software development costs and R&D assets acquired in a business combination, which is why an acquirer can carry intangibles that the target never recorded.
Under IFRS, IAS 38 requires research costs to be expensed but development costs to be capitalized once specific criteria are met, including technical feasibility and probable future benefits. The judgment involved means two IFRS companies with similar spending can capitalize very different shares of it.
How to capitalize R&D step by step
- Choose a useful life. Pick the number of years over which R&D produces benefits. Typical choices are around three years for consumer software, five for technology hardware and many industrials, and ten for pharmaceuticals.
- Collect past R&D. Gather R&D expense for as many past years as the useful life, from the 10-K income statements.
- Build the research asset. For straight-line amortization, each past year's spending is partly amortized. The unamortized portion of all past years is the research asset.
- Compute this year's amortization. Sum the amortization of each past year's spending that falls in the current year.
- Adjust operating income. Add back this year's R&D expense and subtract the amortization.
- Adjust invested capital. Add the research asset to invested capital.
- Adjust taxes if needed. R&D is generally deductible for tax as the tax rules allow, so many analysts keep the tax line as reported rather than recomputing it.
| Item | Reported | Adjusted |
|---|---|---|
| Operating income | After full R&D expense | Plus R&D, minus amortization |
| Invested capital | Excludes research asset | Plus unamortized R&D |
| Reinvestment | Capital spending only | Plus R&D, minus amortization |
| Free cash flow | Unchanged | Unchanged |
| Return on capital | Can be overstated or understated | Reflects the research asset |
A worked example
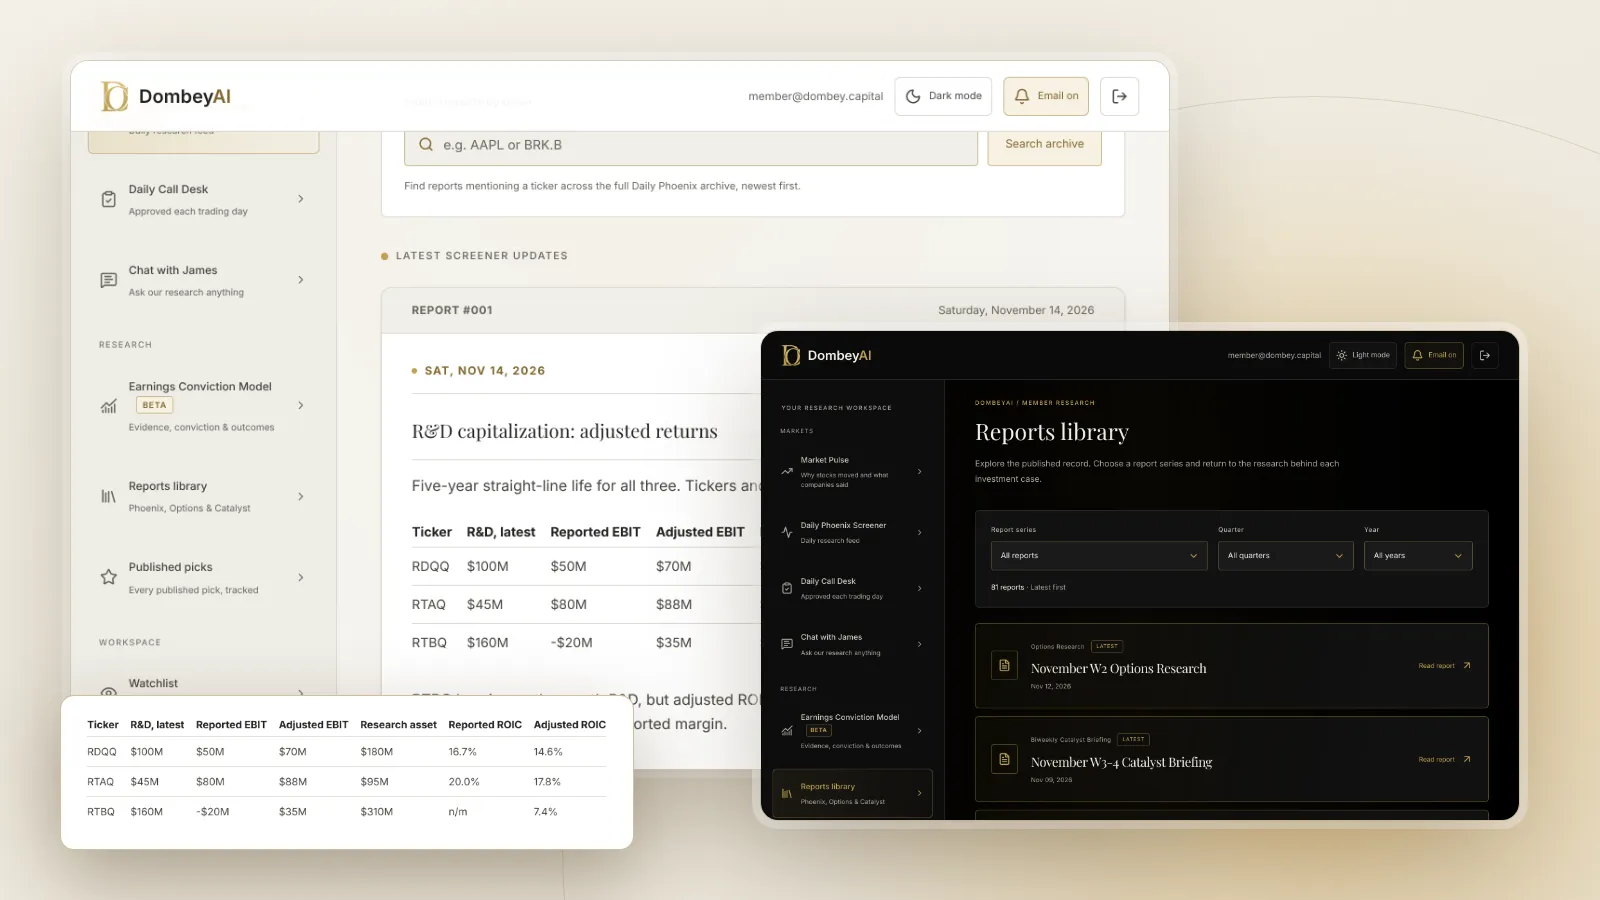
The direction of the return change depends on the company. A business with very productive R&D, such as one whose products earn high margins for years, can show a high adjusted return. One spending heavily for little result sees its adjusted return fall well below the reported figure.
Choosing a useful life
The useful life should reflect how long a dollar of R&D keeps producing revenue. A few signals help:
| Signal | Shorter life | Longer life |
|---|---|---|
| Product cycle | Annual releases, frequent rewrites | Products sold for a decade or more |
| Development time | Months | Years, with regulatory approval |
| Protection | Little beyond speed to market | Patents and long approval processes |
| Typical industries | Consumer software, internet services | Pharmaceuticals, aerospace, industrial equipment |
A practical approach is to calculate adjusted figures at two or three lives, for example three, five and ten years, and see whether the conclusion changes. If adjusted return on capital is high under every assumption, the business is likely earning good returns on its research. If the conclusion flips with the life chosen, the adjustment is telling you the answer depends on a judgment you cannot verify, which is useful in itself.
Use the same life for every company in a comparison. Comparing one company at three years with a peer at ten years builds the conclusion into the inputs.
Where the adjustment helps most
- Comparing peers with different investment types. A software company and a hardware company become more comparable.
- Companies in heavy investment phases. Reported losses can hide an operating business that earns money before growth spending; our piece on normalized earnings covers the wider adjustment.
- Judging cuts to R&D. If a company cuts R&D to hit a target, capitalizing shows that earnings were flattered at the expense of the research asset.
- Valuation. In a discounted cash flow, treating R&D as reinvestment ties growth to how much is being invested and what it earns. Our guide to discounted cash flow explains the link between reinvestment and growth.
It also helps when a product franchise is running out of protection. Our piece on patent cliffs shows why pharmaceutical R&D is often amortized over a longer life.
Where this goes wrong
- The useful life is a guess. A three-year and a ten-year life produce very different assets and returns. Test a range.
- Not all R&D is investment. Some spending sustains existing products and behaves more like an operating cost.
- Failed projects stay in the asset. Straight-line amortization assumes every dollar produces value; failures are not written off.
- Acquired R&D is treated differently. Acquisitions bring capitalized intangibles onto the balance sheet, while internal R&D does not, so adjust consistently.
- Stock compensation inside R&D. Much R&D expense is stock-based pay. Our piece on whether stock compensation is a real expense explains why it should stay in the cost.
- It does not predict returns. The adjustment improves comparability; it does not show whether future R&D will pay off.
How it fits a research process
Use capitalized R&D as a second view alongside reported figures. Build the research asset in a spreadsheet, test two or three useful lives, and look at how adjusted margins and returns compare with peers and with the company's own history. For data tools that make the multi-year R&D history easy to pull, see the best stock research tools for individual investors, and our piece on owner earnings covers a related adjustment for maintenance spending.
The bottom line
Expensing R&D treats long-lived investment as a cost of the current year, which distorts earnings, invested capital and returns for companies that invest in intangibles. Capitalizing it, with a sensible useful life, puts those companies on a footing closer to businesses that invest in plant and equipment. The adjustment rests on judgment about useful life and the quality of the spending, so test a range and use it as a lens, not a verdict.