

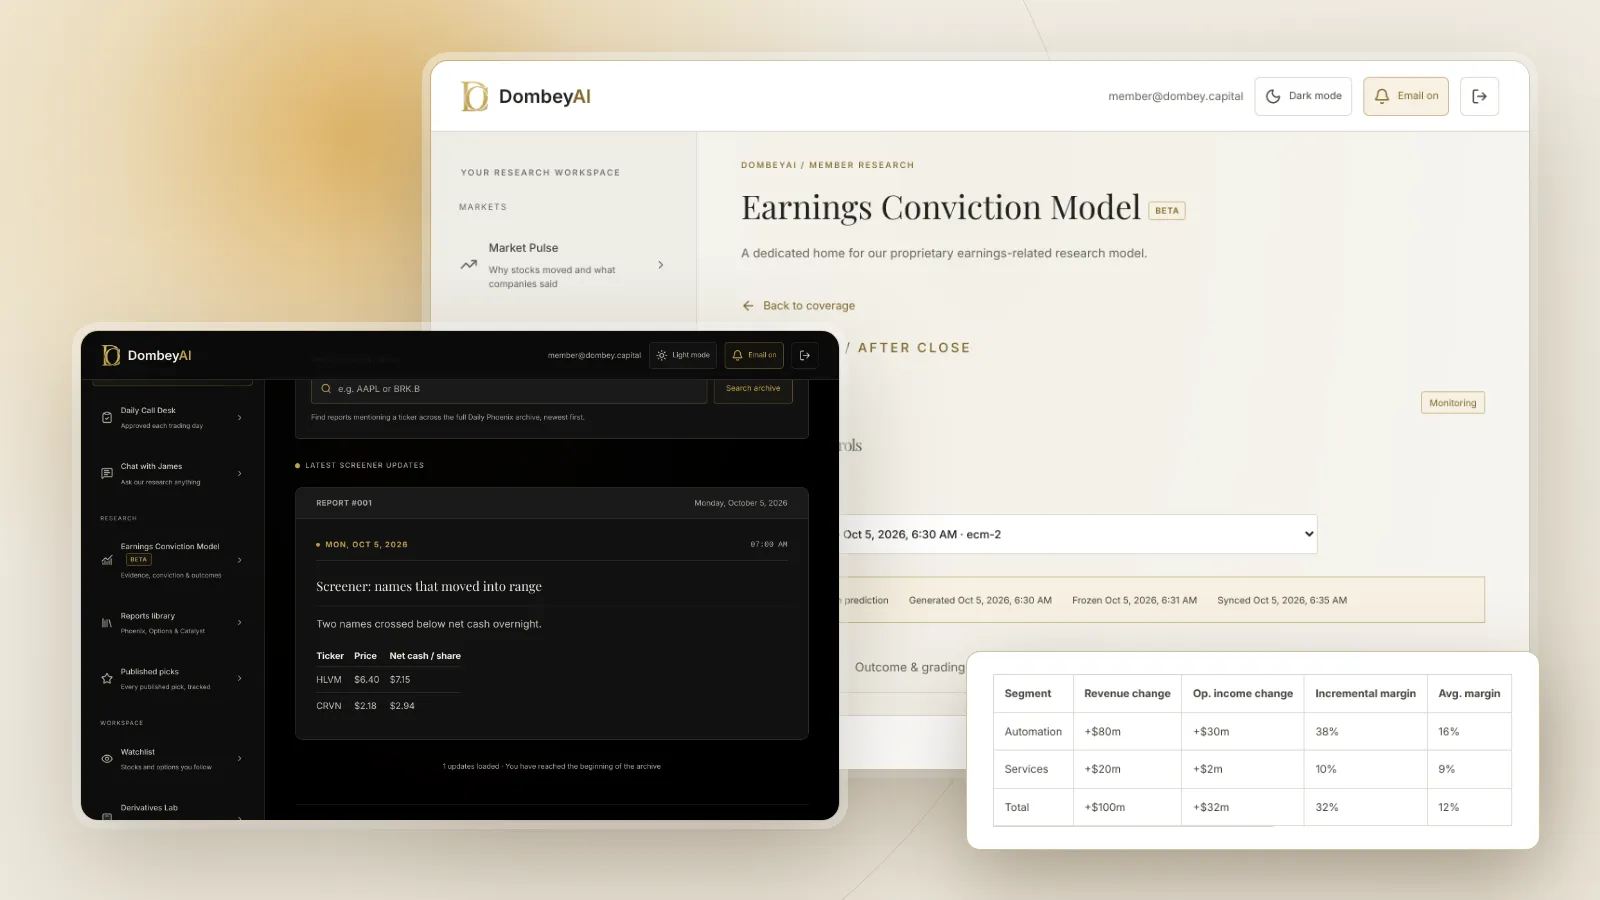
The formula
Incremental margin = (profit this period minus profit last period) / (revenue this period minus revenue last period)
The usual profit measure is operating income or EBITDA, and the usual comparison is year over year, to avoid seasonal swings. Some analysts use gross profit to isolate pricing and production costs.
How to read it
The number matters most next to the company's average margin.
| Incremental margin compared with average margin | What it means |
|---|---|
| Well above | Margins are expanding: fixed costs are being spread over more sales |
| About equal | The business is growing at its existing margin |
| Below, but positive | Profit is growing, but margins are shrinking |
| Negative | Profit fell even though revenue rose |
| Above 100% | Profit rose more than revenue, usually from cost cuts or a one-off |
A company with a 15% operating margin that adds revenue at a 40% incremental margin is in a very different position from one adding revenue at 10%. Both report profit growth. Only the first is scaling.
Why it matters
It shows operating leverage in practice. Operating leverage describes how fixed costs amplify changes in revenue. Incremental margin is the observed result. A company with high fixed costs should show high incremental margins in growth and high decremental margins in decline.
It tests guidance. When management guides to revenue growth and margin expansion, the implied incremental margin can be checked against history. If the guide needs 50% incremental margins and the company has never exceeded 25%, the forecast is ambitious. Our explainer on guidance changes covers how outlooks move stocks.
It helps value turnarounds and cyclicals. A company coming off a trough often has idle capacity. Its incremental margins on recovering volume can be far above its average, which is why earnings can rebound faster than revenue. Our guide on how to value a cyclical stock uses this logic.
It shows the cost of growth. If incremental margins fall as growth accelerates, the company may be buying revenue with discounts, marketing or new capacity.
Incremental margins by type of business
Cost structure decides how high incremental margins can run. The table gives rough patterns, not targets.
| Business type | Typical cost structure | Incremental margins in growth |
|---|---|---|
| Software and data | High fixed cost, low cost per extra customer | Often well above the average margin |
| Semiconductors and capital equipment | Heavy fixed plant, high utilization swings | High in upturns, with steep decrementals in downturns |
| Airlines and hotels | High fixed cost per seat or room | High when occupancy rises, painful when it falls |
| Retail and distribution | Mostly variable costs | Close to the average margin |
| Contractors and services | Labor-heavy, cost rises with revenue | Close to or below the average margin |
The pattern explains why two companies reporting the same revenue growth can report very different profit growth. It also explains why markets pay close attention to utilization in capital-heavy industries: the last few points of capacity carry the highest incremental margins.
Decremental margins
When revenue falls, run the same formula. A drop of $100 million in revenue with a drop of $45 million in operating income is a 45% decremental margin.
Decremental margins are a quick stress test. Before a downturn, estimate what a 10% or 20% revenue decline would do to operating income at the company's historical decremental margin. A business with a 12% margin and a 45% decremental margin loses most of its profit on a 20% sales decline. That matters most for companies with debt, where the interest coverage ratio can fall quickly.
| Revenue change | Operating income at a 30% decremental | At a 50% decremental |
|---|---|---|
| Starting point: $1.0B revenue, $120M operating income | $120M | $120M |
| minus 10% | $90M | $70M |
| minus 20% | $60M | $20M |
The figures are illustrative.
How to calculate it well
Use the same basis. Compare reported to reported, or adjusted to adjusted. Mixing GAAP operating income in one year with adjusted figures in the other produces nonsense.
Strip out one-off items. Restructuring charges, impairments, litigation settlements and gains on asset sales distort both periods. Our explainer on normalized earnings covers what to remove.
Remove acquisitions. If revenue grew because of a purchase, the incremental margin mixes organic growth with the acquired company's margin. Use organic revenue where the company discloses it.
Check currency. Foreign exchange moves can shift revenue and costs differently, especially for exporters.
Work by segment. A consolidated figure can hide one segment scaling and another shrinking. Our guide on reading segment disclosures shows where segment profit is reported.
Use several periods. One quarter's incremental margin on a small revenue change can swing wildly. Look at trailing twelve months and multi-year changes.
Incremental margin and returns on capital
High incremental margins are not the whole story. A business may need large investment to add revenue, so the incremental return on the capital invested matters too. Compare the change in operating income with the change in invested capital over the same period. Our explainer on return on invested capital covers the measure, and our piece on maintenance capex versus growth capex shows how to split spending.
A business with 40% incremental margins that needs $3 of capital for each $1 of new revenue may create less value than one with 25% incremental margins that needs almost none.
Where to find the numbers
The income statement in the 10-K and 10-Q gives revenue and operating income for the current and prior periods. Segment notes give segment revenue and profit. Earnings releases often include a reconciliation of adjusted operating income or EBITDA. Our guide on how to read an income statement walks through the lines, and our explainer on gross margin covers the line above operating income. Many data platforms compute margins over several years, and our comparison of the best stock research tools for individual investors covers the main ones.
Where this goes wrong
Small denominators. When revenue barely changes, the ratio can show 300% or minus 200%. Those figures describe noise, not the business.
Cost timing. A company can delay hiring or marketing for a few quarters and post high incremental margins that reverse later.
Mix shifts. If a high-margin product grows while a low-margin one shrinks, the incremental margin can look strong without any scaling.
Price versus volume. Revenue growth from price increases tends to carry very high incremental margins, because costs barely change. That can fade once price increases stop.
Extrapolation. A recovering company's early incremental margins come from idle capacity. Once capacity fills, the company must add costs, and incremental margins fall back toward the average.
The bottom line
Incremental margin is the change in profit over the change in revenue, and it shows how much of each new dollar of sales reaches the bottom line. Compare it with the company's average margin to see whether the business is scaling, and run the decremental version to stress test a downturn. Clean out one-off items, acquisitions and currency first, and check several periods by segment. A high figure is most useful when it comes with modest capital needs and a cause you can name.