

Why the split matters
Free cash flow is operating cash flow minus capital spending. But not all capital spending is a cost of running the business. A retailer that opens 50 new stores spends cash that will, if the stores work, earn its own return. Subtracting that spending from this year's cash flow understates what the existing business produces.
Warren Buffett made the point in his 1986 shareholder letter, where he defined owner earnings as reported earnings plus depreciation and other non-cash charges, minus the capital spending needed to maintain the business's competitive position and unit volume. Only the maintenance part comes off.
The split changes valuations a great deal. For a capital-heavy business, maintenance capex can be the difference between a free cash flow yield of 4% and one of 9%.
Definitions
| Type | What it pays for | Could the company stop it and keep its current size? |
|---|---|---|
| Maintenance | Replacing worn equipment, refurbishing stores, safety and regulatory work, IT upkeep | No |
| Growth | New plants, new stores, added capacity, new products, new markets | Yes |
| Grey areas | Upgrades that both replace and improve, efficiency projects, required capacity to keep market share | Partly |
The grey areas are where judgment comes in. A replacement machine that is twice as fast is partly maintenance and partly growth. In a growing market, spending that only holds market share is arguably maintenance, because without it the business would lose position.
Method 1: Depreciation as a proxy
The simplest estimate is that maintenance capex roughly equals depreciation, since depreciation spreads the cost of existing assets over their useful lives.
This works best for a stable business with assets of mixed ages and low inflation. It fails in three common cases:
- Inflation. Depreciation is based on historical cost. Replacing a machine bought ten years ago costs more today, so maintenance capex can run above depreciation.
- Old assets. A company with fully depreciated equipment reports low depreciation but faces a wave of replacement spending.
- Rapid growth. A company that recently built a lot of new capacity reports high depreciation on assets that will not need replacing for years.
Method 2: The asset-to-sales method
This method, set out by Bruce Greenwald and colleagues, estimates growth capex from how many fixed assets the business needs per dollar of sales.
- Compute the ratio of gross or net property, plant and equipment to sales, averaged over several years.
- Multiply that ratio by this year's increase in sales. That is the estimate of growth capex.
- Subtract growth capex from total capex. The remainder is the estimate of maintenance capex.
The method assumes the business keeps the same capital intensity as it grows. It breaks when sales fall (the formula then produces negative growth capex), when the company is building capacity ahead of sales, or when acquisitions add assets that were not bought through capex.
Method 3: Management and segment disclosure
Some companies say what they spend on maintenance. Pipeline partnerships report maintenance capital spending because it enters their distributable cash flow. REITs report recurring capital expenditures. Industrial and retail companies sometimes give a rough split at investor days or on earnings calls.
Treat management's figure as a claim to test. Companies have a reason to call more spending "growth", because it makes the underlying business look more cash-generative. Check the figure against depreciation and against the asset-to-sales estimate. Read the cash flow statement and the capital spending discussion in the 10-K's management discussion section.
Worked example
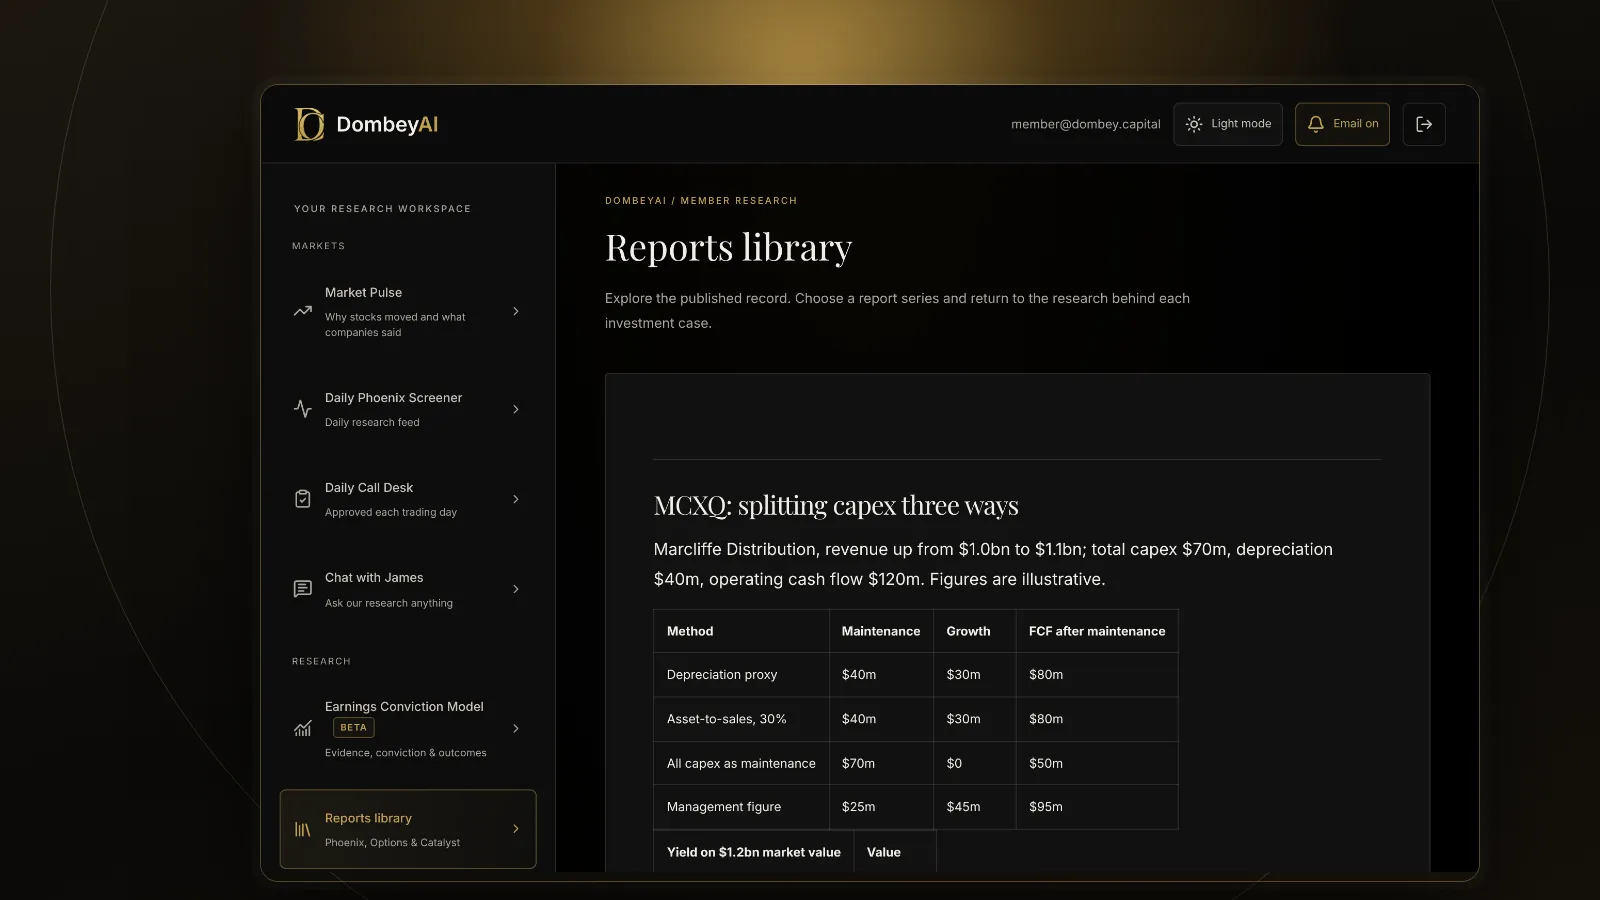
| Method | Maintenance capex | Growth capex | Free cash flow after maintenance only |
|---|---|---|---|
| Depreciation proxy | $40 million | $30 million | $80 million |
| Asset-to-sales | $40 million ($70m less 30% of $100m) | $30 million | $80 million |
| Treat all capex as maintenance | $70 million | $0 | $50 million |
| Management says $25 million | $25 million | $45 million | $95 million |
Here the first two methods agree at about $40 million. Management's $25 million is well below both, which is a reason for caution. The gap between $50 million and $95 million of free cash flow is large: on a $1.2 billion market value it is the difference between a 4% and an 8% yield. A reasonable working figure is the $40 million the two independent methods agree on.
How to use the estimate
Three places where the split feeds directly into a valuation:
- Owner earnings and normalized free cash flow. Subtract maintenance capex only. For cyclical companies, use a cycle-average figure, as in how to value a cyclical stock.
- Return on growth spending. Compare the increase in operating profit with the growth capex that produced it. That is a direct read on whether growth creates value, the same question ROIC answers at the company level.
- DCF models. In a discounted cash flow model, growth capex should be tied to the revenue growth it supports. Projecting high growth with only maintenance capex overstates value.
The data platforms in our list of the best stock research tools for individual investors show total capex and depreciation over long histories, which is what the first two methods need.
Industry patterns
The split varies by business model, and knowing the pattern helps judge whether an estimate is plausible.
| Industry | Maintenance tends to be | Why |
|---|---|---|
| Pipelines and utilities | A large share of total capex, and often disclosed | Long-lived regulated assets that must be kept safe and compliant |
| Retail and restaurants | Store refurbishments on a regular cycle | Growth comes from new units, which are easy to count |
| Manufacturing | Close to or above depreciation in mature plants | Equipment wears out; inflation raises replacement costs |
| Software and services | Small in capex, but large spending sits in operating expense | Development and customer retention costs are expensed |
| Mining and energy production | Sustaining capex is often disclosed separately | Reserves deplete, so spending is needed just to hold output flat |
For mining and energy producers, "sustaining" capital is the usual name for maintenance spending, and many producers report it. That makes those industries a useful place to practice the split, because you can compare your estimate with the company's own figure.
Where this goes wrong
The common errors:
- Ignoring spending booked as expense. Software development, marketing to keep customers and some repairs go through the income statement, not capex. A business can look capital-light while spending heavily to stand still. See capitalizing R&D for one adjustment.
- Ignoring acquisitions. A company that grows by buying businesses may report modest capex while spending heavily on deals.
- Using one year. Capex is lumpy. Use a multi-year average.
- Forgetting leases. Assets obtained under leases do not appear as capex but still need replacing.
- Taking management's split at face value. The incentive points toward calling more spending growth.
The bottom line
Maintenance capex keeps a business at its current size; growth capex expands it. Because companies report only one figure, investors estimate the split using depreciation, the asset-to-sales method and any disclosure management provides, and check the methods against each other. The estimate matters because owner earnings and normalized free cash flow subtract only maintenance spending. Use several years of data, adjust for inflation and acquisitions, and treat a maintenance figure far below depreciation as a question, not an answer.