

The method in one paragraph
Graham's approach had four parts. Find companies priced below NCAV, ideally at two-thirds of it or less. Buy many of them rather than a few. Hold each for a limited time. Sell when the price reaches the asset value or the time runs out. The logic was statistical: some of the companies would fail, some would recover, and the group as a whole was priced for more failure than it was likely to suffer. No single name had to be right.
Modern practice keeps that structure and adds work Graham could not do as cheaply: reading every filing on EDGAR, checking cash burn quarter by quarter and looking for a dated event that could force the value toward holders.
Where net-nets turn up today
Net-nets are rare in large, well-covered markets. When they appear, they cluster in a few places.
Microcaps and nanocaps. Companies with small market values and little or no analyst coverage. Most funds cannot own them, which is one reason the discount can exist.
Over-the-counter listings. Some companies trade over the counter after leaving an exchange or never listing on one. Disclosure can be thinner, quotes wider and trading volume tiny.
After a sharp loss. A failed product, a lost customer or a broad market decline can push a cash-rich company below NCAV for a period. The count of net-nets tends to rise after market declines and fall in strong markets.
Some foreign markets. Markets with many small companies that hold large cash balances and cross-shareholdings have historically produced more net-nets than the U.S. Governance norms, currency and access add risk.
Post-restructuring shells. Companies that sold their operating business and kept the cash. These overlap with liquidation plays, and the question is whether the cash goes to holders or to a new venture.
| Where | Why the discount exists | Main risk | What to check first |
|---|---|---|---|
| U.S. microcaps | No coverage, too small for funds | Cash burn | Last four quarters of operating cash flow |
| Over-the-counter | Thin disclosure, delisting stigma | Stale or missing filings | Date of the latest 10-Q or annual report |
| After a sharp loss | Forced and tax-loss selling | Business keeps shrinking | Guidance, backlog, customer concentration |
| Foreign markets | Cash hoarding norms, low liquidity | Currency, governance | Reporting currency, shareholder base |
| Cash shells | Business sold, plan unclear | Cash spent on a new venture | Proxy and 8-K for stated use of cash |
Checking a net-net: what to read and in what order
A screener produces candidates. It does not produce net-nets, because standardized data misclassifies items, misses preferred stock and uses stale share counts. Every candidate needs a hand check.
- Pull the latest balance sheet. Use the most recent 10-Q or 10-K on EDGAR. A 10-Q is due 40 days after quarter end for large accelerated and accelerated filers and 45 days for all other registrants, so a small company's latest balance sheet can be more than four months old by the time the next one arrives. What is a 10-Q covers where each figure sits.
- Recompute NCAV and a haircut version. Current assets minus all liabilities and preferred stock, then again with receivables and inventory marked down. Use diluted shares from the cover page and the equity note.
- Measure the burn. Take operating cash flow plus capital spending for the last four quarters. How to estimate cash runway sets out the method.
- Read the notes for claims that are not on the balance sheet. Purchase commitments, guarantees, litigation, leases and severance obligations.
- Check for dilution. Warrants, convertibles, an at-the-market program or a shelf registration can fund losses with new shares and lower NCAV per share.
- Find the holders. Insiders, a controlling shareholder or an activist with a Schedule 13D. An initial 13D is now due within five business days of crossing 5%, and amendments within two business days, so a new activist stake shows up quickly. What is a 13D filing explains how to read one.
- Name the path. A buyback, a tender offer, a sale, a liquidation or a return to profit. If none is plausible, record that.
Worked example: a five-stock basket
The companies and numbers below are hypothetical and illustrative.
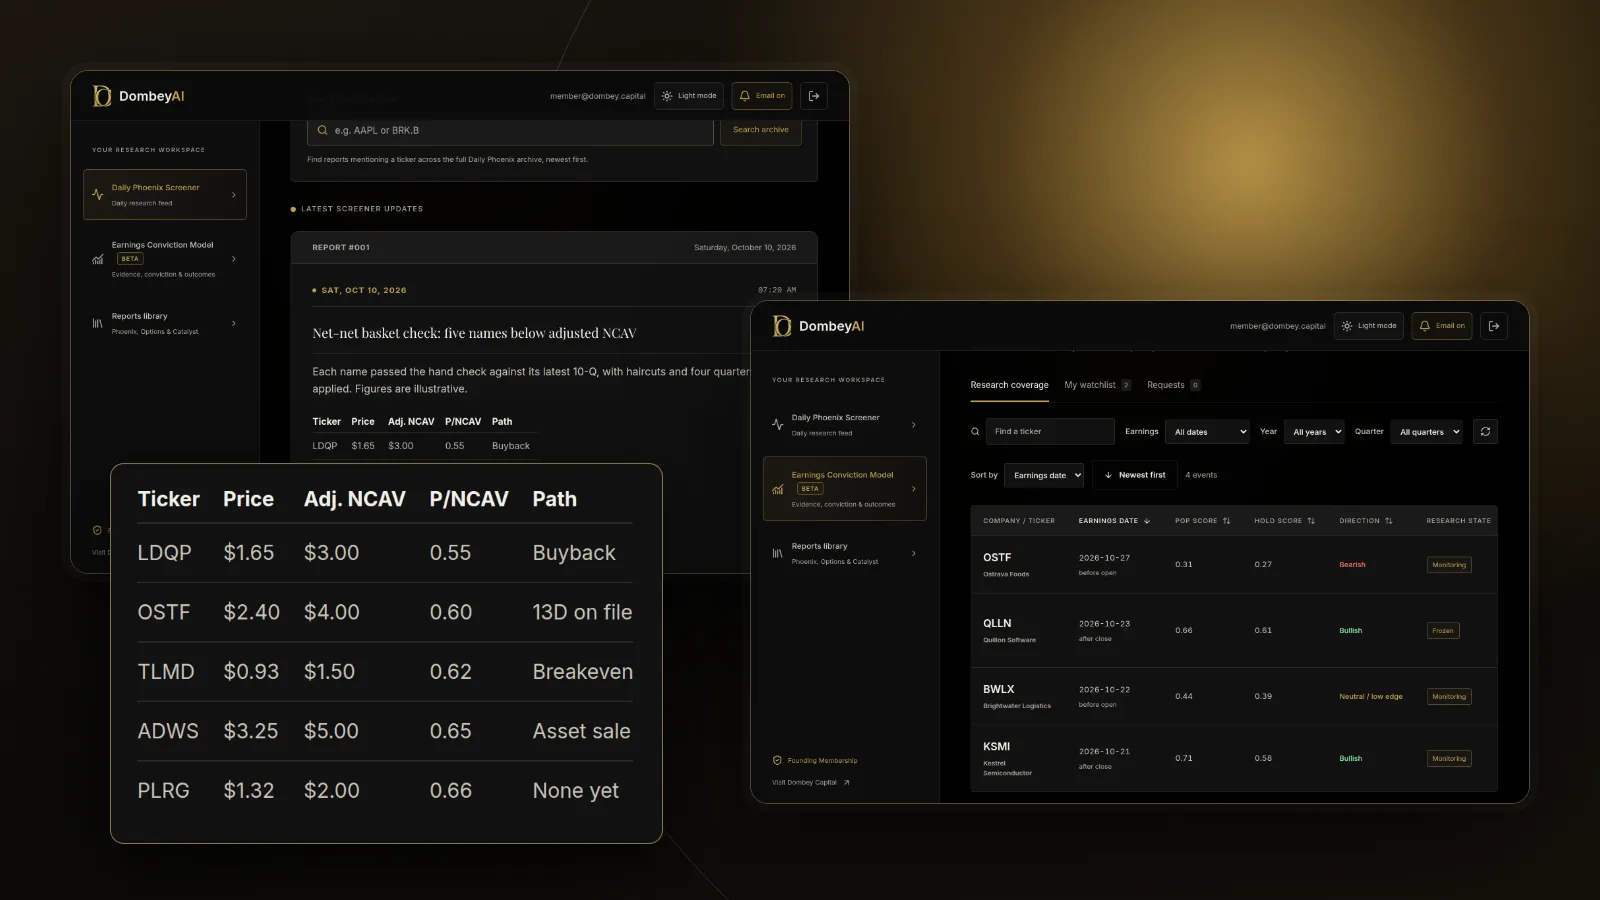
Two years later, suppose the results look like this. Company A bought back stock and the price reached NCAV. Company B was sold to a competitor at a price near NCAV. Company C traded flat. Company D announced a new acquisition with the cash and fell. Company E burned through a third of its current assets and fell further.
That spread of outcomes is the point of the basket. Two of five worked, one did nothing and two lost money. Graham's method does not depend on picking which two. It depends on the group being bought cheaply enough that the winners cover the losers, and on the exit rules being followed for all five. Whether a real basket comes out ahead is not knowable in advance.
Sizing and exit rules
Net-net positions need rules written before the first purchase, because the stocks give few signals afterward.
Position size. Equal weights keep any one company from deciding the result. Many practitioners also cap each position at a share of the stock's average daily dollar volume, so the position can be exited in a reasonable number of trading days.
Entry discipline. Graham's two-thirds of NCAV is a common threshold. Applying it to the haircut figure after burn is stricter and leaves fewer names.
Exit rules. The usual choices:
- If the price reaches NCAV, or a set fraction of it, exit. The asset discount that justified the position is gone.
- If a fixed holding period ends without progress, exit or re-underwrite from scratch. A rule of thumb often attributed to Graham uses a period of about two to three years.
- If the company issues shares to fund losses, exit or re-check, because NCAV per share has changed.
- If management commits the cash to a new venture or acquisition, re-check the thesis, since the asset floor no longer reaches holders.
- If the latest filing shows NCAV falling faster than the plan assumed, re-check the position against the new figure.
Trading costs and liquidity
The discount in a net-net is partly payment for illiquidity. That cost is real and it comes out of the result.
- Wide spreads. A stock quoted at $1.90 bid and $2.10 ask costs about 10% to enter and exit at the quotes. On a position bought at two-thirds of NCAV, that is a large share of the margin of safety.
- Thin volume. Buying with limit orders over days or weeks is normal. Market orders in thin stocks move the price.
- Foreign access. Some foreign net-nets trade in the U.S. only as thin over-the-counter quotes. Buying on the home exchange can mean higher commissions, currency conversion and withholding tax on dividends.
- Small tender offers. Some cash-rich small companies use tender offers to return capital. For small holders, odd-lot tender offers can matter.
Where this goes wrong
Net-net investing fails in recognizable ways.
- The cash never reaches holders. Management or a controlling shareholder keeps the cash indefinitely, pays high salaries or makes acquisitions. The discount is permanent because the value is not really available to the minority.
- Burn outruns the catalyst. A company losing money converts current assets into expenses each quarter. A stock at 0.6 times NCAV with two years of burn ahead may be fairly priced.
- Hidden claims. Off-balance-sheet commitments, litigation, environmental costs and wind-down expenses consume current assets that the formula counted in full.
- Dilution. Small companies often fund losses with new shares. NCAV per share falls even if total NCAV holds steady.
- Concentration. Holding two or three net-nets turns a statistical method into a set of single bets, which is the opposite of how Graham used it.
- Stale or wrong data. Over-the-counter and foreign companies may report late or in another currency. A screener can compare a current price with a balance sheet that is a year old.
- The business matters more than the balance sheet. A company with collapsing sales can be worth less than NCAV, and debt coming due can change the picture fast. What is a debt maturity wall covers that risk.
How it fits with other balance-sheet floors
Net-net investing is one of several asset-based approaches. Net cash per share is stricter, counting only cash less debt. Negative enterprise value stocks are a subset where the market values the business below zero on cash alone. How to find stocks trading below net cash applies the same hand-check process with the cash-only floor. Dombey's published research applies these floors before each dated catalyst; see the research archive.
- If the company holds mostly cash, use net cash, which needs no haircut judgment.
- If receivables and inventory are large and of good quality, NCAV with haircuts is the right floor.
- If the value sits in property or long-lived assets, NCAV will understate it and a tangible book approach fits better.
The bottom line
A net-net stock trades below its current assets minus every liability, and Graham's method was to buy such stocks as a diversified group with fixed rules for entry, size and exit. Today the candidates are mostly microcaps, over-the-counter names and some foreign listings, so data checks, liquidity and trading costs matter as much as the ratio. Check each figure against the latest filing, subtract burn, look for dilution and name a path for the value to reach holders. Treat any single net-net as one entry in a basket, not a thesis on its own.