

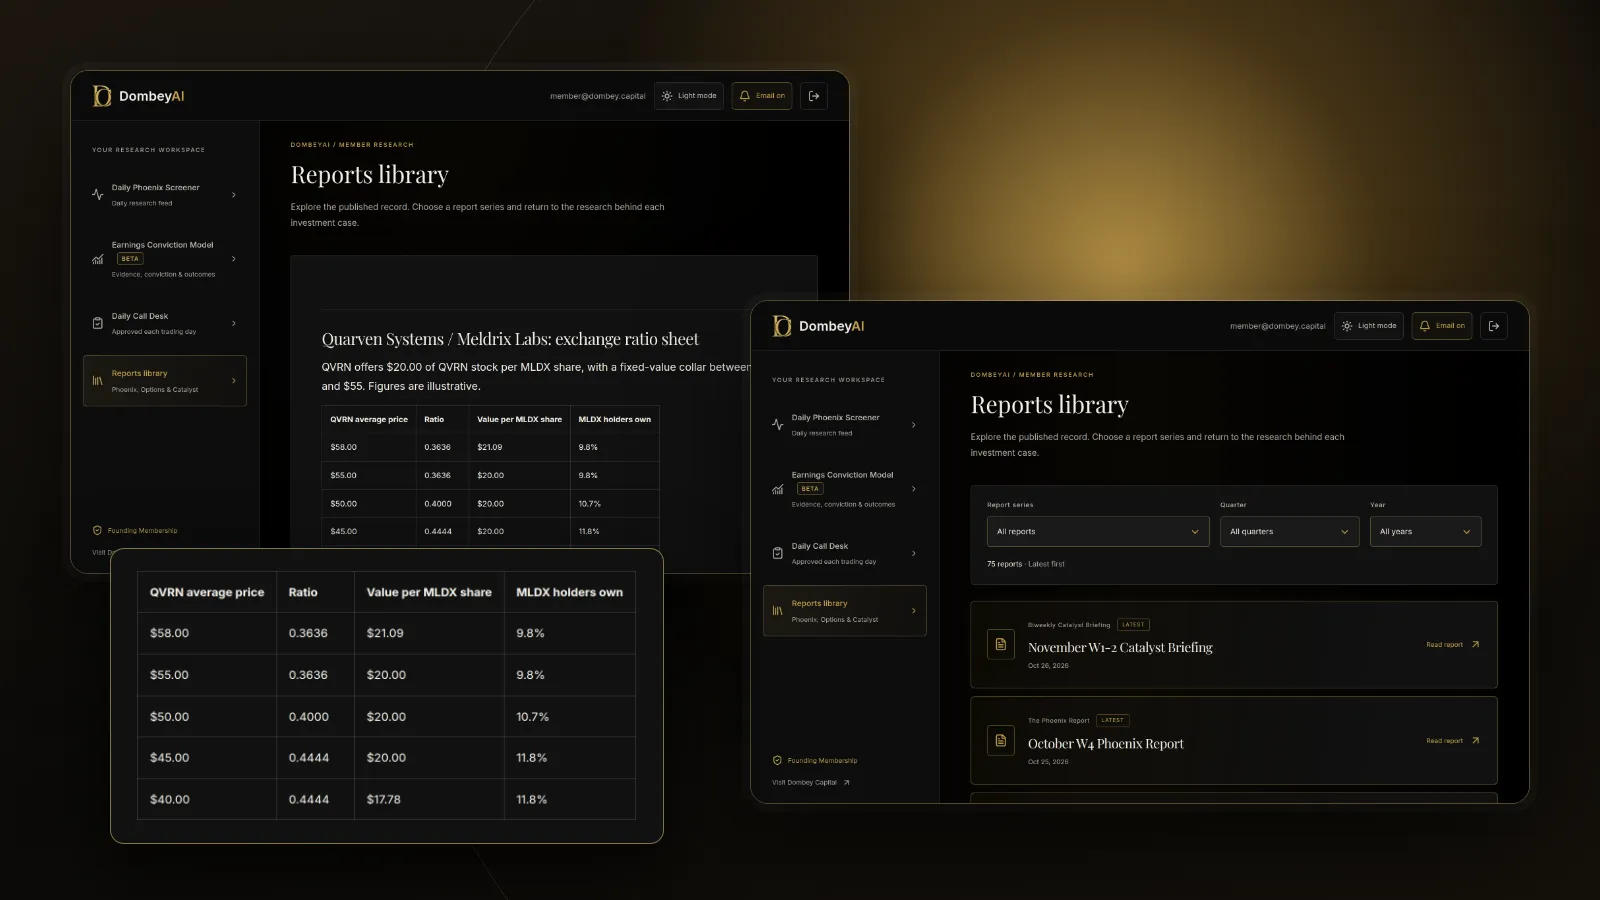
How the exchange ratio is set
In a negotiated deal, the two sides agree on a value per target share and convert it into acquirer shares at the acquirer's price when terms are set. If the acquirer agrees to pay a value of $20 per target share and its own stock trades at $50, the ratio is 20 divided by 50, or 0.40.
Ratios are usually stated to four decimal places, such as 0.4237. Once the merger agreement is signed, the ratio in the agreement is what counts. The headline dollar value in the press release is only the ratio times the acquirer's price on one day.
Boards weigh more than the headline price when they set a ratio. The fairness opinions summarized in the proxy or S-4 registration statement often include a historical exchange ratio analysis, comparing the agreed ratio with the ratio implied by the two stocks' prices over past periods, and a contribution analysis comparing each side's share of revenue, earnings or cash flow with its share of the combined company.
Fixed ratio versus fixed value
There are two basic structures, and they put the price risk on different holders.
Fixed exchange ratio. The number of acquirer shares per target share is set at signing. The acquirer knows exactly how many shares it will issue. Target holders bear the risk that the acquirer's stock falls before closing, and share in any rise. Most large stock-for-stock deals use this structure.
Fixed value, or floating ratio. The agreement sets a dollar value per target share. Near closing, the ratio is calculated by dividing that value by the acquirer's average price over a measurement period, often a volume-weighted average over a set number of trading days ending shortly before closing. Target holders know the value they will receive. The acquirer does not know how many shares it will issue, and its holders bear the dilution risk if its price falls.
Mixed consideration. Many deals pay part cash and part stock, such as $4.00 in cash plus 0.30 acquirer shares. Some let holders elect cash or stock, subject to proration so the total mix stays at a set level. The stock part behaves like any fixed or floating ratio.
| Structure | What is fixed | What moves | Who bears acquirer price risk |
|---|---|---|---|
| Fixed ratio | Shares per target share | Deal value | Target holders |
| Fixed value (floating ratio) | Dollar value per target share | Shares issued | Acquirer holders |
| Fixed ratio with collar | Shares, inside a price band | Value inside the band, shares outside it | Split by the band |
| Fixed value with collar | Value, inside a price band | Shares inside the band, value outside it | Split by the band |
| Cash and stock | Cash amount plus a ratio | Value of the stock part | Target holders, on the stock part |
Collars and walk-away rights
A collar limits how far the deal can move with the acquirer's price.
In a fixed-value collar, the ratio floats so target holders receive the set value as long as the acquirer's average price stays inside a band. Outside the band, the ratio locks at its limit and the value moves with the stock. In a fixed-ratio collar, the ratio is fixed inside the band and adjusts outside it to keep the value from going beyond set limits.
Some agreements add a walk-away right: if the acquirer's price falls below a threshold, the target can terminate unless the acquirer tops up the consideration. These triggers are often tied to both an absolute fall and underperformance against a named index, so a broad market decline alone does not set them off.
The exact formula, the measurement period and the termination thresholds are in the merger agreement. Our guide on how to read a merger agreement shows where each one sits.
What the ratio means for target holders
For a target holder, the ratio turns a dollar offer into a position in another company. Three numbers follow from it.
Implied value per share: ratio times the acquirer's current price. This is what the deal is worth today, not what it was worth when announced.
Implied premium: implied value divided by the target's unaffected price, minus one. In a fixed-ratio deal, the takeover premium shrinks or grows as the acquirer's stock moves.
Pro forma ownership: shares issued to target holders divided by total shares after closing. This tells you what share of the combined business you will own.
Use fully diluted share counts for both sides, including options, restricted stock units and convertible securities, when you calculate ownership. Our article on dilution and share count changes covers what to include.
Other details follow from the ratio. Fractional shares are usually paid in cash. Target stock options and awards are converted using the ratio, as explained in what happens to options when a company is acquired. Agreements typically adjust the ratio for stock splits, stock dividends and reclassifications before closing.
What the ratio means for acquirer holders
For acquirer holders, the ratio is the price of the deal in shares. A higher ratio means more shares issued and a smaller slice of the combined company for existing holders. Whether that is a good trade depends on what the target adds in earnings and cash flow per share issued, not on the headline premium.
A fixed-value structure gives the acquirer less control over dilution. If its stock falls sharply before closing, it issues more shares to deliver the same value. That is the main reason acquirers usually prefer a fixed ratio and targets push for value protection.
How arbitrageurs use the ratio
In a stock deal, the spread is the implied value minus the target's price. If Company A trades at $50 and Company B at $19.20 under a 0.40 ratio, the implied value is $20 and the gross spread is $0.80, about 4.2%.
Because the implied value moves with Company A, arbitrageurs who want to isolate the spread typically buy the target and short the acquirer in proportion to the ratio: for every 1,000 Company B shares, short 400 Company A shares. With a fixed ratio, that hedge holds the dollar spread steady as the acquirer moves. With a fixed-value structure inside its collar, the deal behaves more like a cash deal and needs little or no short. Near the edges of a collar, the right hedge changes quickly.
The full method, including dividends on both legs, borrow costs and annualizing over the expected closing date, is in our guide on how to calculate a merger arbitrage spread. For the broader strategy, see merger arbitrage explained.
Where to find the terms
- The announcement 8-K and press release: headline ratio and implied value on the signing date.
- The merger agreement: the defined merger consideration, collar formula, measurement period, fractional share treatment, adjustment clause and termination rights. It is usually filed as an exhibit to an 8-K.
- The S-4 or joint proxy statement: a plain-language summary, the fairness opinions, pro forma ownership and the tax section.
All three are on EDGAR. For research focused on deals and other corporate events, our list of the best investing newsletters for special situations compares the main options. Dombey's published research works through the deal terms before each merger catalyst; see the research archive.
Where this goes wrong
Common mistakes, each with a simple fix:
- Quoting the announcement value. The press release value is a snapshot. Recalculate with the acquirer's current price.
- Ignoring the collar edges. A fixed-value deal near the edge of its band behaves like a fixed-ratio deal. Check where the acquirer's average price sits against the band.
- Using the wrong price period. Floating ratios use an average over a defined window, not the closing price on one day. Read the definition in the agreement.
- Forgetting dividends. A short acquirer position owes the acquirer's dividends. Some agreements also coordinate dividend dates between the two companies.
- Counting basic shares only. Ownership and dilution change once options, units and convertibles are included.
- Assuming the deal closes. If the deal fails, the target trades on its own value again. Our article on deal breaks covers how to estimate that downside.
The bottom line
An exchange ratio is the number of acquirer shares paid per target share in a stock merger. With a fixed ratio, the share count is set and the value moves with the acquirer's stock; with a fixed value, the dollar amount is set and the share count moves instead. Collars and walk-away rights split that risk within a band. Read the ratio, the formula and the adjustment terms in the merger agreement, then recalculate the implied value, premium and ownership split at today's prices.