

What a BDC is
A BDC is a closed-end investment company that elects to be regulated as a business development company under the Investment Company Act of 1940. Congress created the structure in 1980 to channel capital to smaller private companies. Most BDCs today are lenders: they make senior secured, second-lien and unitranche loans to private, mid-sized US businesses, often owned by private equity firms, and sometimes take small equity stakes.
The rules shape the economics:
- Eligible assets. A BDC must keep at least 70% of its assets in qualifying investments, mainly private or small US companies.
- Leverage. A BDC must keep asset coverage of at least 200%, or 150% if it has approved the lower limit permitted by a 2018 change in the law. At 150%, debt can reach about twice equity.
- Distributions. Most BDCs qualify as regulated investment companies, which lets them avoid corporate income tax if they distribute at least 90% of their investment company taxable income.
- Issuing equity. A BDC generally cannot sell new shares below NAV without shareholder approval and board determinations, because doing so dilutes existing holders.
- Valuation. Holdings are carried at fair value, determined under board-overseen procedures that the SEC's Rule 2a-5 governs. Most are Level 3 assets with no market price.
Many BDCs are externally managed: an outside adviser runs the portfolio for a base fee, often charged on gross assets, plus incentive fees on income and gains. Some are internally managed and pay their staff directly.
Why the market discounts NAV
| Reason for the discount | What investors fear | Where to check |
|---|---|---|
| Stale or generous marks | Loans are worth less than the stated fair value | Fair value hierarchy and valuation notes in the 10-Q |
| Rising non-accruals | Interest has stopped on a growing share of the book | Non-accrual table, often by cost and fair value |
| Payment-in-kind income | Income is accrued, not received in cash | Interest income breakdown, PIK as a share of income |
| Uncovered dividend | The payout exceeds net investment income | Net investment income per share against the dividend |
| Fee drag | The adviser earns fees even when shareholders do not | Advisory agreement, base fee basis, incentive hurdle |
| High leverage | Small losses on assets become large losses on equity | Asset coverage ratio and debt maturities |
| Falling rates | Floating-rate loans earn less | Share of floating-rate assets, rate floors |
NAV is a mark, not a price
A BDC's NAV per share is the fair value of its investments plus cash, minus debt and other liabilities, divided by shares. The fair values are estimates, usually built from discounted cash flow models, comparable yields and third-party valuation firms. They are updated once a quarter.
The market price moves every day. When credit conditions worsen, investors can sell the shares well before the next quarterly marks reflect it. A discount is often the market's estimate of the next write-down.
The return on NAV
A second, separate reason is return. If a BDC earns net investment income equal to 9% of NAV, and investors want 11% from a leveraged credit vehicle, the shares will trade below NAV even if every loan is marked correctly. Fees are the usual cause of a low return, because they come out before shareholders are paid. Our explainer on return on equity shows how leverage and costs shape that figure.
Worked example: what a discount implies
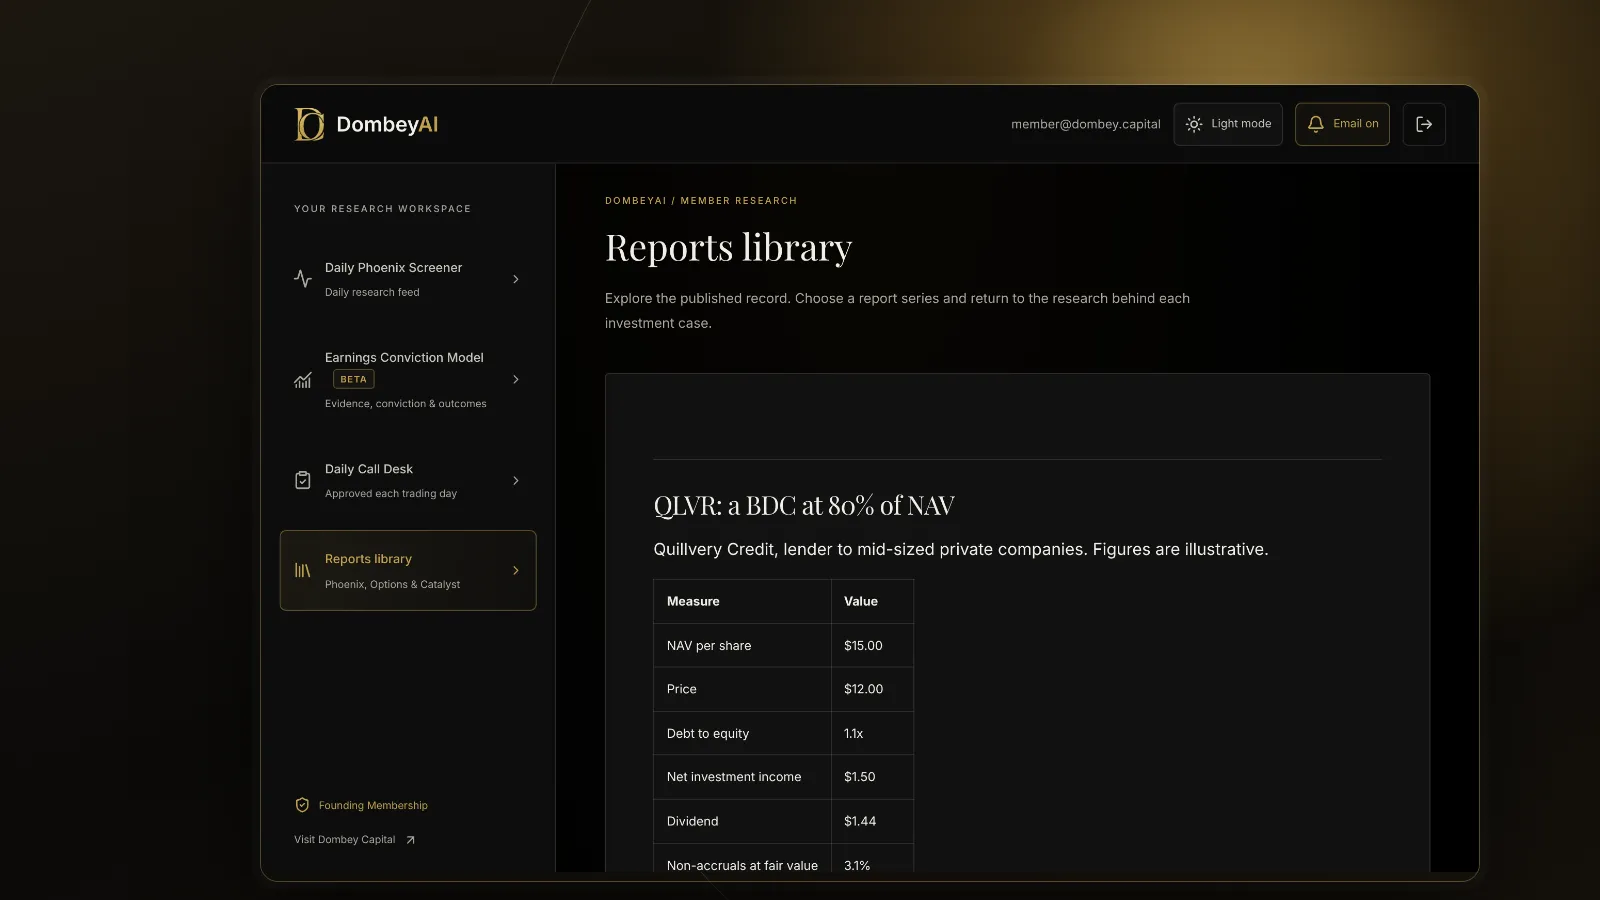
There are two ways to read the $3.00 discount.
As an implied loss. If the whole gap were a credit problem, the portfolio would have to be worth $3.00 a share less than its marks. That is about 9.5% of total assets. For a book of first-lien loans, a loss of that size would require many defaults at low recoveries. For a book with large second-lien and equity positions, it is more plausible.
As an implied return. Suppose net investment income is $1.50 a share, or 10% of NAV, and the dividend is $1.44. At $12.00, the dividend yield is 12%. If investors require 12% from this BDC, the price is consistent with correct marks and a return on NAV that is simply too low for the risk.
In practice the discount is a mix of both. The analyst's job is to decide which part is larger. A cleaner way to frame it:
| Scenario | Write-down to NAV | Adjusted NAV | Price as % of adjusted NAV |
|---|---|---|---|
| Marks are fair | $0.00 | $15.00 | 80% |
| Modest losses | $1.00 | $14.00 | 86% |
| Severe losses | $2.50 | $12.50 | 96% |
If you think losses will be modest and the return on NAV can improve, the discount is wide. If you think losses will be severe, the price is close to fair.
How to read a BDC below NAV
- Read the schedule of investments. It lists every holding with cost, fair value and position in the capital structure. Note where fair value sits well below cost.
- Track non-accruals over several quarters. A rising trend matters more than one quarter's level. Compare non-accruals at cost and at fair value.
- Measure PIK income. Payment-in-kind interest is added to the loan balance rather than paid in cash. A rising share can mean borrowers are struggling.
- Compare net investment income with the dividend. A dividend paid from capital rather than income will be cut eventually; see what dividend cuts signal.
- Read the advisory agreement. Note the base fee, whether it is charged on gross assets including leverage, the incentive fee hurdle and any fee waivers.
- Check leverage and maturities. Asset coverage close to the minimum limits the BDC's room to absorb losses, and debt coming due may need refinancing at higher cost.
- Look at insider and buyback activity. Purchases below NAV by the company or its insiders say something about how management values the book.
Our guide to reading a 10-Q for special situations covers where these items sit in the quarterly report.
What closes the discount
A BDC below NAV is a special situation only if something can close the gap. The routes are:
- Buybacks below NAV. Each share repurchased at a discount adds to NAV per share for remaining holders. It works only if leverage allows and the board uses it.
- Lower fees. A fee cut or waiver raises the return on NAV directly.
- Mergers. BDCs sometimes merge, often within the same adviser's family, with exchange ratios set off NAV. A target trading at a discount can benefit, but terms vary and conflicts of interest are common.
- Tender offers. A tender at or near NAV returns capital to holders who want out. Our explainer on Dutch auction tender offers covers one common format.
- Managed wind-down. A board can stop new lending and return capital as loans are repaid. Holders then receive something close to realized value over time, similar to the dynamics in a liquidation play.
- Activism. An investor with a large stake may push for any of the above, and a Schedule 13D filing is often the first public sign.
- Better credit than feared. A run of quarters with stable marks and falling non-accruals can do the job without any corporate action.
How BDC discounts compare with other discounts
The logic is close to that of a closed-end fund discount, with two differences: BDCs hold private loans rather than quoted securities, so NAV is less certain, and they carry more leverage. It also resembles a holding company discount, where costs and control questions keep a gap open. In all three cases, the discount is persistent unless something forces it to close.
Credit data helps. Tools that track private credit spreads and loan prices give a market reference for how the marks might move; see our comparison of credit data tools for equity investors. For research services that cover discount-to-value situations like this one, see our list of the best investing newsletters for special situations.
Where this goes wrong
Treating NAV as fact. NAV is the manager's estimate. A large discount may simply be the market's more accurate estimate.
Ignoring the cycle. In a credit downturn, defaults and write-downs can continue for several quarters. Buying the first discount can mean watching NAV fall for a year.
Counting on a catalyst that has no reason to happen. An external adviser earns fees on assets. A wind-down or a large buyback shrinks them. Without pressure, the adviser may prefer to keep the discount and the assets.
Missing dilution. If shareholders approve issuance below NAV, new shares can lower NAV per share for everyone.
Focusing on yield. A 12% dividend yield is not a 12% return if the dividend is later cut or NAV keeps falling.
The bottom line
BDCs trade below NAV when investors doubt the marks on their private loans, expect a return on NAV below what they require, or both. The discount can be read as an implied write-down or as an implied required return, and the useful work is deciding which explanation fits. Non-accruals, PIK income, dividend coverage, fees and leverage are the facts that settle it. A discount becomes a special situation only when something, such as buybacks, fee cuts, a merger, a tender or a wind-down, can close it. Dombey's published research reads the schedule of investments before writing on any listed credit vehicle; see the research archive.