

What a holding company discount is
A holding company owns stakes in other businesses, listed or private, and often a little cash and some debt of its own. Its net asset value (NAV) is the value of those holdings plus cash, minus holding company debt. The discount is the share price as a shortfall to NAV per share.
Discount = 1 minus (share price / NAV per share)
A conglomerate is the operating version of the same thing: one company running several unrelated businesses. Its discount is measured against a sum of the parts rather than a portfolio NAV. The causes overlap, so this article treats them together and uses "holding company" for both.
Two features make holding companies easy to misread. First, the parts often include listed stakes with a visible price, so the headline NAV looks precise. Second, many holding companies publish their own NAV figure, which tends to leave out the costs that explain most of the discount.
Why the discount exists
Each cause below is a reason a dollar of assets inside the structure is worth less than a dollar to an outside shareholder.
| Cause | What it costs owners | Where to check | Can an event remove it? |
|---|---|---|---|
| Head office costs | Annual expense that no holding earns back | Segment note reconciliation, unallocated costs | Partly, through a simplification |
| Tax on unrealized gains | Tax due if a stake is sold above its tax basis | Income tax note, deferred tax liabilities | Often not; a tax-free spin-off may avoid it |
| Holding company debt | A claim that ranks ahead of shareholders | Debt note, parent-only financial statements | Yes, through asset sales that repay it |
| Capital allocation risk | Cash from good units funds weak ones or poor deals | Cash flow statement, acquisition history | Only through a change in policy or people |
| Control and governance | Outsiders cannot force a sale or separation | Proxy statement, dual-class share terms | Rarely without the controller's consent |
| Complexity | Fewer analysts and investors cover the stock | Number of segments, cross-holdings | Yes, if the structure is simplified |
| Trapped or minority stakes | Value the holding company cannot pull out | Equity-method note, shareholder agreements | Sometimes, through a buyout of minorities |
Some of these are permanent features of the structure. Head office costs and tax on gains are cash that shareholders would never receive even in an orderly break-up. Others, such as complexity and capital allocation risk, are about confidence and behavior, and those are the parts an event can change.
The proxy statement is where control shows up: voting rights, related-party dealings, and how management is paid. A structure where the controlling holder is paid on the size of the group rather than value per share has little reason to shrink.
How to measure the discount honestly
Measure the discount twice. The first figure uses the headline NAV, the way the company or a data screen would show it. The second subtracts the costs that are real but usually left out.
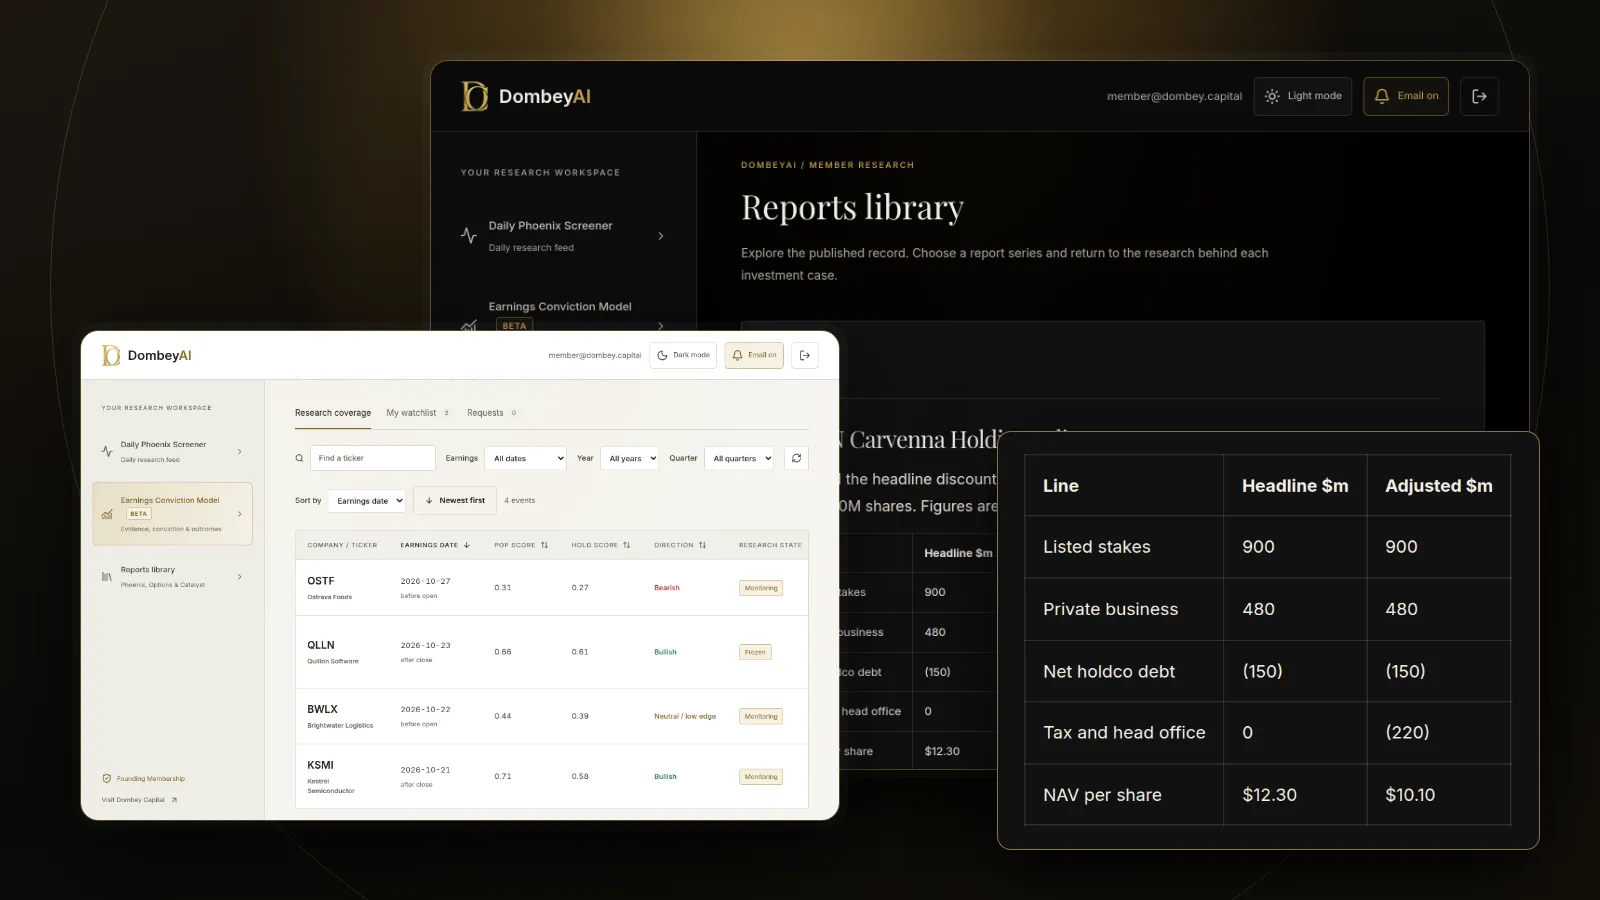
| Line | Headline NAV ($m) | Adjusted NAV ($m) |
|---|---|---|
| Stake in Company B | 600 | 600 |
| Stake in Company C | 300 | 300 |
| Private distribution business | 480 | 480 |
| Plus cash, less holding company debt | (150) | (150) |
| Less tax on gain in Company B at an assumed 25% | 0 | (100) |
| Less head office costs capitalized at 8x | 0 | (120) |
| Net asset value | 1,230 | 1,010 |
| Per share | $12.30 | $10.10 |
| Discount at $8.61 | 30% | about 15% |
The headline discount of 30% halves once tax and head office costs are counted. That remaining 15% is the part worth studying. It reflects complexity, capital allocation doubt and the time it may take to release value, and those are the pieces an event can change.
Two further checks belong in the measurement:
- Look through to the holdings' own debt. If a private subsidiary carries debt that the parent guarantees, that debt is effectively a parent claim. The parent-only financial statements, sometimes shown as a schedule in the 10-K, show what the holding company itself owes.
- Check the private valuations. Listed stakes have a market price. Private businesses are only as good as the multiple applied to them, and holding companies tend to value their own private assets generously. Use the same discipline you would in an enterprise value build.
Earned discount versus open discount
It helps to split the adjusted gap into two questions.
- Is the discount earned? If management has a record of overpaying for acquisitions, if cash from strong units keeps flowing to weak ones, or if the controlling holder extracts value through fees and related-party deals, the market is right to pay less than NAV. A wide discount on such a company can be fair value.
- Is the discount open to change? If the costs are modest, the record is reasonable and the structure could be simplified, the gap is a question of when, not whether. That depends on whether anyone with the power to act has a reason to do it.
Track the discount over time for the same company. A holding company that has traded between 20% and 35% below headline NAV for a decade is not unusually cheap at 30%. A move well outside its own range, or a change in the facts behind it, is what deserves attention.
What tends to close the gap
The discount narrows when value inside the structure becomes value shareholders can reach. The usual mechanisms:
- If the company announces a spin-off, the business being separated will register its shares, usually on Form 10, which shows standalone financials and the separation terms. See what a Form 10 is and spin-off investing.
- If the company sells a stake or a business, the price paid tests your valuation directly, and the cash can repay holding company debt or fund a return of capital.
- If the company buys back its own shares below NAV, each repurchase raises NAV per remaining share. A Dutch auction tender offer is one way to do it in size.
- If the company collapses a dual-class structure, merges with a listed subsidiary or removes cross-holdings, complexity falls and the investor base widens.
- If an activist builds a stake above 5%, a Schedule 13D is due within five business days after the date of acquisition, and Item 4 states its plans, often a break-up or a sale. See what a 13D filing is.
- If the company decides to wind down and distribute the holdings, the question becomes timing and cost, covered in liquidation plays.
Dombey's published research looks for this pairing of a measured gap and a dated event that could close it; see the research archive.
Where this goes wrong
The listed stakes move, and the discount moves with them. If most of the NAV is one listed stake, the discount can shrink simply because that stock fell. Recalculate NAV with current prices before concluding anything.
The private assets are worth less than the company says. Self-reported NAV often uses favorable multiples for unlisted businesses. If an asset sale comes in below the carried value, the discount was partly an illusion.
Separation costs more than expected. Spin-offs need new boards, systems and finance teams, and standalone companies can lose shared purchasing and borrowing terms. A sale may trigger the tax you counted, and sometimes more.
The controller does not care. A founder or family that values control, prestige or a long horizon may never act on the discount. Outside shareholders have little leverage without a vote that matters.
Time erodes the return. A discount that closes in seven years may be worth little today after the opportunity cost of waiting. It can also widen first, if markets fall and holding companies are sold off with everything else.
Use the adjusted discount as one input, alongside the record of management and a credible event, not as a valuation target on its own.
A short checklist
Before treating a holding company discount as an opportunity, confirm each of these:
- The headline and adjusted NAV, both recalculated from today's prices and the latest filings.
- The tax basis of each major stake and the tax that a sale would trigger.
- Head office costs, capitalized, and any fees paid to the controlling holder.
- Holding company debt, guarantees and any debt at subsidiaries that is effectively the parent's.
- The company's own range of discounts over several years.
- A specific mechanism that could close the gap and a rough date for it, recorded in a dated investment thesis.
The bottom line
Holding companies and conglomerates trade below their parts mainly because some of that value never reaches shareholders: head office costs, tax on gains and debt take a share, and management and control decide what happens to the rest. Measure the discount on headline NAV and again after those costs, because the adjusted gap is usually much smaller and is the part that matters. That remaining gap narrows through events such as spin-offs, sales, buybacks below NAV and simplification. Without a mechanism and a date, a cheap holding company can stay cheap for a long time.