

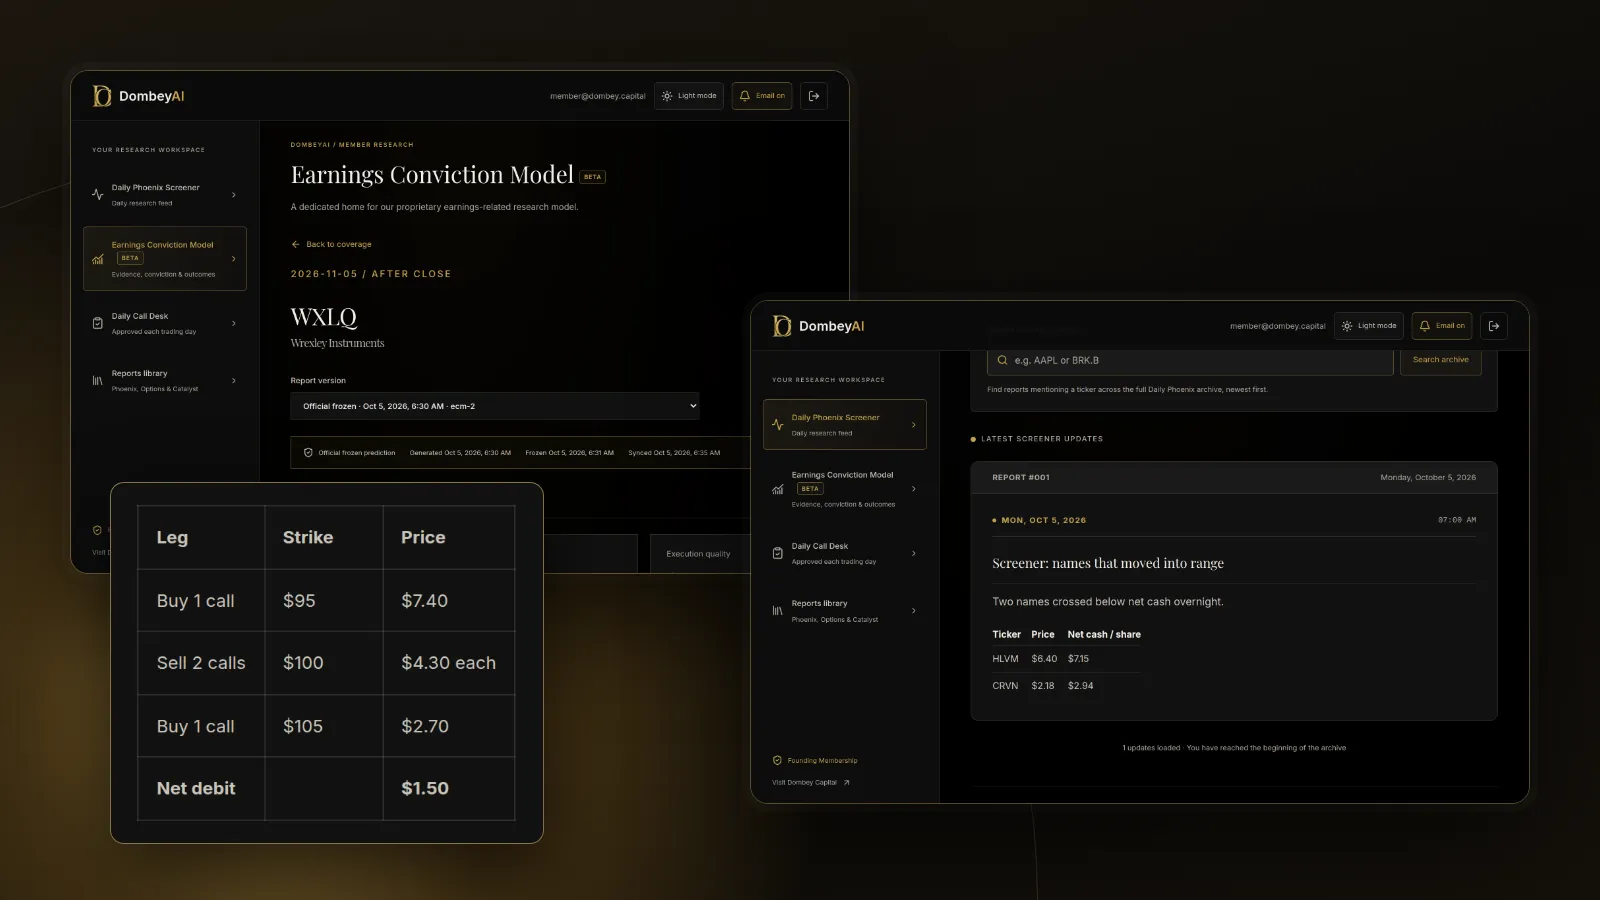
How a butterfly spread is built
The standard long call butterfly has three strikes and four options:
- Buy one call at the lower strike (the lower wing).
- Sell two calls at the middle strike (the body).
- Buy one call at the higher strike (the upper wing).
All four options share an expiration date, and the wings sit the same distance from the body. The two long calls cost more than the two short calls bring in, so the position is opened for a net debit. That debit is the most the position can lose.
The same shape can be built with puts, or as an iron butterfly, which sells an at-the-money put and call and buys a lower put and a higher call for a net credit. With the same strikes, the payoffs at expiration are almost the same.
The payoff at expiration
At expiration the butterfly behaves in three zones:
- Below the lower strike: every call expires worthless and you lose the debit.
- At the middle strike: the lower call is worth the full distance between strikes, the short and upper calls are worthless, and the position earns its maximum.
- Above the upper strike: gains and losses on the four calls cancel out, and you again lose the debit.
Between those points the value rises in a straight line toward the middle strike and falls away on the other side, which gives the payoff its tent shape.
| Stock at expiration | $95 call | Two short $100 calls | $105 call | Net after $1.50 debit |
|---|---|---|---|---|
| $90 | $0 | $0 | $0 | ($1.50) |
| $96.50 | $1.50 | $0 | $0 | $0.00 |
| $100 | $5.00 | $0 | $0 | $3.50 |
| $103.50 | $8.50 | ($7.00) | $0 | $0.00 |
| $110 | $15.00 | ($20.00) | $5.00 | ($1.50) |
The example shows the trade-off. The reward can be more than twice the risk, but only inside a range about $7 wide, and the full reward only at a single price.
Why traders use butterflies around events
A butterfly expresses a precise view at low cost. Three common uses:
Pinning to a deal price. When a company agrees to a cash takeover, its stock tends to trade just below the offer price until the deal closes. A trader who expects the deal to close on time might center a butterfly on the offer price at an expiration after the expected close. If the deal closes, the stock converges on the price; if it breaks, the loss is limited to the debit. Our explainer on what happens to options when a company is acquired covers how deals change option contracts.
Selling expensive volatility with a cap on risk. Before earnings, implied volatility often rises and then collapses after the report, the effect described in IV crush. A trader who thinks the options price too large a move can sell the body and buy the wings, which keeps the loss defined if the move is larger than expected. An iron condor does a similar job with a wider, flatter profit zone.
Targeting a level. A trader who expects a stock to drift toward a specific price, for example after a tender offer sets a floor, can center a butterfly there for much less than buying calls outright.
How the Greeks behave
A long butterfly is short volatility near the middle strike: if implied volatility falls, the position usually gains, and if it rises, the position usually loses. Time decay works in its favor when the stock sits near the body and against it when the stock is near or beyond the wings. Gamma is negative near the middle strike, so the position's delta changes quickly as expiration nears. Our guide to the option Greeks explains each measure.
The practical result is that a butterfly gains slowly. Most of the value arrives in the last days before expiration, and only if the stock is near the middle strike. Weeks before expiration, a stock sitting exactly at the body may show only a small gain.
Variations
| Variation | How it is built | Opened for | When it is used |
|---|---|---|---|
| Long call butterfly | Buy 1 low call, sell 2 middle calls, buy 1 high call | Debit | A view that the stock will be near the middle strike |
| Long put butterfly | Same with puts | Debit | Same view, sometimes better priced below the stock |
| Iron butterfly | Sell middle put and call, buy lower put and higher call | Credit | Collecting premium with a defined maximum loss |
| Broken wing butterfly | Wings at unequal distances | Smaller debit or a credit | Reducing cost while accepting more risk on one side |
Where this goes wrong
- The stock moves too far. The profit zone is narrow. A small surprise in either direction can turn a winning position into a full loss of the debit.
- Wide bid-ask spreads. Four options means four spreads to cross on the way in and again on the way out. In thinly traded names this can consume much of the potential gain. Our article on options liquidity explains how to judge it.
- Timing. A butterfly needs the stock near the body at expiration. If a deal closes later than expected or an event moves, the options may expire before the outcome.
- Pin risk. If the stock closes very near the middle strike on expiration day, you may not know whether the short options will be exercised, and you can wake up with an unwanted stock position.
- Deal breaks. A butterfly centered on a takeover price loses its full debit if the deal fails and the stock falls below the lower strike. See deal breaks for how far stocks can fall.
Options carry risks that can result in losing the whole premium. The OCC's options disclosure document, listed in the sources, is required reading before trading them. Dombey's market coverage follows the options pricing around dated events as they happen.
The bottom line
A butterfly spread is a limited-risk options position that pays the most if a stock closes at one price at expiration. Its cost and maximum loss are known at the start, and its reward can be several times the risk, but only within a narrow range. It suits events that set a price, such as a cash takeover or a tender offer, and periods when options look too expensive for the move you expect. Check liquidity, early assignment and timing before relying on one.