

A short definition
An option's delta is how much its price changes for a $1 move in the stock. A call with a delta of 0.50 gains about $0.50 per share, or $50 per contract, when the stock rises $1. A put's delta is negative: a put with a delta of -0.30 gains about $30 per contract when the stock falls $1.
A delta hedge takes the opposite exposure in shares:
- Long calls are hedged by shorting shares.
- Short calls are hedged by buying shares.
- Long puts are hedged by buying shares.
- Short puts are hedged by shorting shares.
The position is then "delta neutral": for a small move, the option and the shares offset. For a refresher on delta and the other sensitivities, see what the option Greeks measure.
Real examples
Delta hedging is routine, but a few episodes show what happens when many participants hedge in the same direction at once.
| Episode | What was hedged | What happened |
|---|---|---|
| October 1987 crash | Portfolio insurance programs replicated put options by selling index futures as prices fell | Selling to stay hedged added to the decline on October 19, 1987, and the strategy lost favor afterward |
| January 2021, GameStop | Many commentators blamed dealers hedging calls they had written | The SEC staff report on early 2021 said staff did not find evidence of a gamma squeeze in GME; options volume was driven mostly by put buying, and market makers were buying, not writing, calls |
| Single-stock earnings gaps | Dealers who are short options hedge with shares overnight | A gap at the open moves the stock past every level where the hedge would have been adjusted |
The GameStop case is a reminder to check the data before blaming hedging flows. The broader lesson holds: a delta hedge assumes the price moves in small steps and that shares can be traded at each step. When either fails, the hedge stops being neutral.
How a delta hedge works
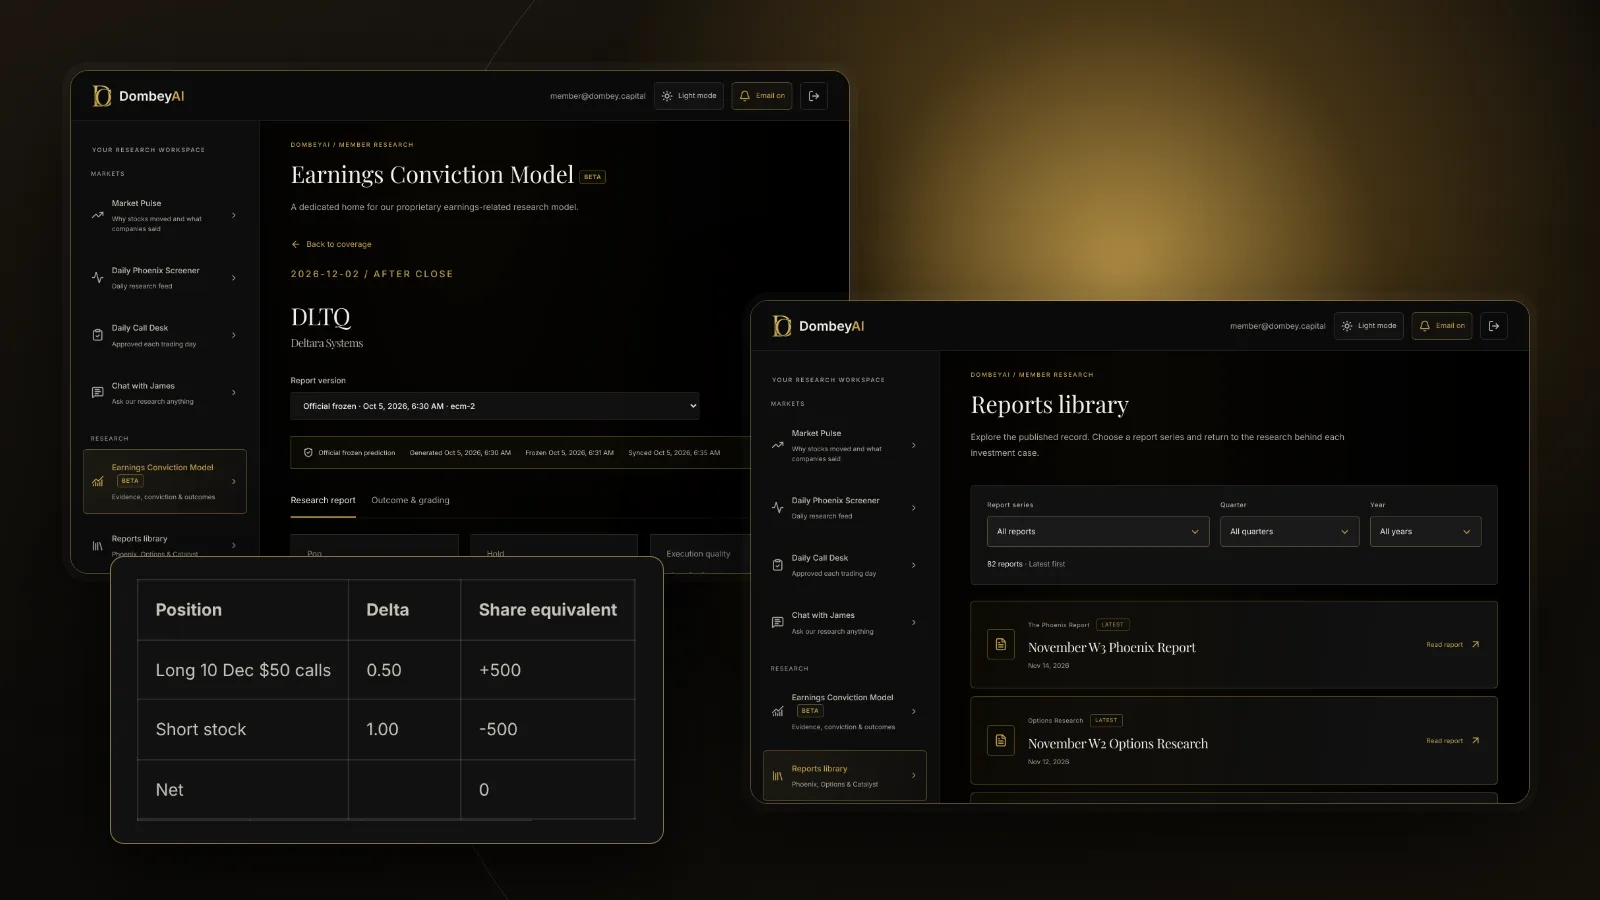
Your option position behaves like 10 x 100 x 0.50 = 500 shares. To be delta neutral, you short 500 shares.
| Stock moves to | Option gain or loss (approx.) | Short 500 shares | Net |
|---|---|---|---|
| $51 | +$500 plus a little | -$500 | Small gain |
| $49 | -$500 plus a little | +$500 | Small gain |
| $50, one week later | Time decay loss | $0 | Small loss |
The "plus a little" is gamma. As the stock rises, the call delta increases, so the calls gain a bit more than the first $500. As the stock falls, delta drops, so the calls lose a bit less. A long option position that is delta hedged earns money on movement and pays for it through time decay.
Gamma and rebalancing
Delta does not stay fixed. If Company A rises to $55, the call delta might climb to 0.70. Your calls now behave like 700 shares while you are short only 500, so you are net long again. To get back to neutral, you short another 200 shares.
This is rebalancing, and the direction depends on the gamma of the book:
- Long gamma (bought options): you sell into rallies and buy into dips. That tends to dampen moves, and each adjustment locks in a small gain from the movement.
- Short gamma (sold options): you buy into rallies and sell into dips. That tends to add to moves, and each adjustment locks in a small loss.
This is why the net positioning of dealers is followed closely, through measures such as gamma exposure. When dealers are short a lot of gamma near a strike, their hedging can make the stock move more.
How often to adjust
Every rebalance costs a spread and fees. Adjusting constantly keeps the hedge accurate but expensive. Adjusting rarely saves cost but lets the position drift. Common rules:
- Adjust when net delta moves outside a band, such as plus or minus 100 shares.
- Adjust at fixed times, such as the close each day.
- Adjust after any move larger than a set percentage.
Why market makers delta hedge
A market maker quotes bids and offers on options all day. Its business is the spread, not a view on direction. When a customer buys 50 calls, the market maker is short those calls and immediately buys shares against them. As the stock moves, it adjusts.
The result is a book that, in principle, makes money from the spread and from pricing implied volatility above the volatility the stock actually delivers. The relationship between those two is covered in realized versus implied volatility. If the stock moves more than the option price assumed, the hedging costs exceed the premium collected and the market maker loses.
Delta hedging around catalysts
Before an earnings report, a trial readout or a merger vote, the stock can sit still for weeks and then move 20% overnight. A delta-hedged position has no chance to adjust between the close and the open. The whole gap lands on the position at once.
For a short option position, that gap is the main risk. For a long option position, it is the payoff. Either way, the outcome around an event depends on the size of the move relative to what the option price implied, which an estimate of the earnings move from options helps frame. Outcomes are often bimodal, which is why option models struggle with binary events.
Dombey's published work on catalysts and their option pricing is collected on the market page.
Delta hedging for individual investors
Most individual investors do not run delta-neutral books, but the idea is useful in three ways.
- Sizing equivalent exposure. Ten calls with a delta of 0.30 behave like 300 shares for small moves. Knowing the share-equivalent helps compare an options position with a stock position of the same risk.
- Partial hedges on stock you hold. An investor who owns 1,000 shares and wants less exposure through an event can buy puts or sell calls whose combined delta offsets part of the holding. A protective put is the simplest version.
- Reading dealer flows. Knowing that dealers hedge helps explain why some stocks pin near large strikes into expiration and why moves can accelerate when dealers are short options.
Keep in mind that the delta shown in a broker's option chain comes from a model and moves with every tick in the stock and in implied volatility.
Where this goes wrong
- Gaps. The stock moves past every adjustment level at once, as described above.
- Transaction costs. On a stock with wide option and share spreads, rebalancing can cost more than the edge.
- Model error. Delta comes from a pricing model and an implied volatility input. If the volatility input is wrong, the hedge ratio is wrong.
- Borrow constraints. Hedging long calls or short puts requires shorting stock. Hard-to-borrow shares can be expensive or unavailable.
- Volatility changes. A delta-neutral position still carries vega. A fall in implied volatility after an event, the IV crush, can cost more than the delta hedge saved.
| Risk | Hedged by delta? | What covers it |
|---|---|---|
| Small price moves | Yes | Shares |
| Changes in delta | No | Rebalancing or other options |
| Implied volatility moves | No | Offsetting options |
| Time decay | No | Accepted as a cost or earned as income |
| Overnight gaps | No | Smaller size or defined-risk structures |
The bottom line
Delta hedging uses shares to cancel an option position's sensitivity to small moves, leaving exposure to volatility and time. It needs rebalancing as delta changes, and every adjustment has a cost. Market makers use it to stay neutral, and their hedging can add to moves when they are short gamma. Around binary catalysts, the hedge fails exactly when it matters most, because the stock gaps instead of stepping.