

Nov 20, 2026: Global Payments jumps 13% on a GTCR buyout report
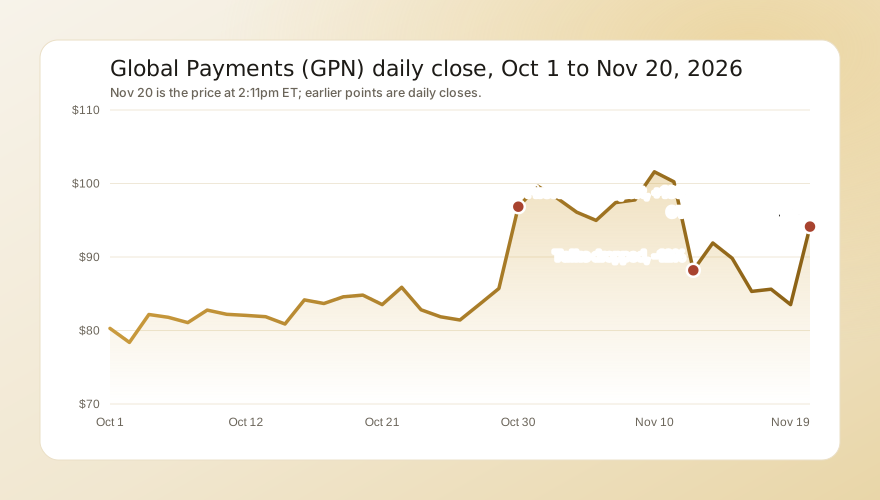
The stock spent most of the session flat. It opened at $83.55, touched its low of $83.33 in the first minutes and traded between about $84.50 and $85.80 through 1:20pm. In the five minutes to 1:30pm it jumped from $84.75 to $89.99 as the report crossed, TheFly noted the 8% move to $89.99, and it reached $95.50 at about 1:35pm, 14.3% above Thursday's close. Some of that faded within 20 minutes, to $91.17, before buyers took it back to $93.80 by 2:10pm. The stock had traded 4.8 million shares by 2:11pm, already above its 20-day average of 4.0 million, with most of the volume after 1:25pm.
The report, by Bloomberg's Liana Baker, Matt Monks and Ryan Gould, said:
- The buyer. GTCR is exploring a takeover and is working with other private equity firms to finance it. The other firms were not named.
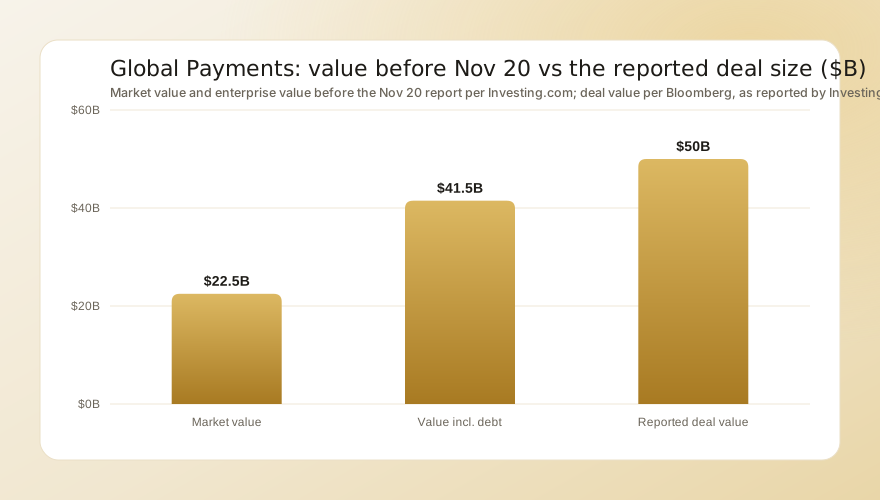
- The size. About $50 billion including debt and a premium. Before today Global Payments was worth about $22.5 billion in the market and about $41.5 billion including debt, Investing.com reported.
- The status. No final decision to pursue an acquisition has been made.
- The history. GTCR previously worked with Clayton, Dubilier & Rice on a joint approach and has dropped that effort.
The rest of the payments group did not follow. At about 2:11pm FIS was up 2.5%, Fiserv was up 0.2%, the iShares payments ETF was up 0.2%, PayPal was down 3.4% and Block was down 4.0%. A move that size in one name, with peers flat or lower, points to the deal report alone. More of the session's movers are in today's biggest stock moves.
After the jump, RSI(14) stood at 55, the shares sat 7.8% above their 50-day average and 19.4% above their 200-day average, volume ran 1.2 times its 20-day average, and the stock was 8.9% below its 52-week high of $102.91, set on Nov 10.
Three takeover headlines in three weeks
| Date | Report | Close | Move |
|---|---|---|---|
| Oct 30, 2026 | CD&R and GTCR exploring a take-private (FT, Reuters) | $96.84 | +13.0% |
| Nov 10, 2026 | Stock peaks after results | $101.59 | +3.9% |
| Nov 12, 2026 | CD&R and GTCR walk away (Reuters) | $88.19 | -12.0% |
| Nov 19, 2026 | Day before the new report | $83.52 | -2.5% |
| Nov 20, 2026 | GTCR weighs $50 billion takeover (Bloomberg) | $94.14 at 2:11pm | +12.7% |
The October reports said CD&R had teamed up with GTCR on a joint bid, Seeking Alpha reported, and a source told Reuters the talks were at an early stage and might not happen. William Blair called the approach credible, put GTCR's holding at roughly 15% and net debt at nearly $22 billion, The Paypers reported. On Nov 12, Reuters reported, citing two people familiar with the matter, that the two firms had walked away because of the complexity of arranging a take-private of this size, and that they could return or another buyer could come forward. The stock fell 11% to about $89 that afternoon, TipRanks reported, and closed at $88.19. Today's report is the second of those outcomes: GTCR is back, without CD&R and with a new group.
GTCR's position comes from Worldpay. Global Payments agreed in 2025 to buy Worldpay in a deal valued at more than $24 billion, paying GTCR partly in stock for its 55% stake, and sold its issuer solutions business to FIS. The deal closed in January 2026, and it is the main reason the company now carries about $22 billion of net debt. Our coverage of why FIS stock fell covers the buyer of that issuer business, which cut its guidance on Nov 4.
What $50 billion would mean per share
The reported figure is an enterprise value: it covers the debt as well as the shares. Subtracting debt of $19 billion (implied by Investing.com's market value and value including debt) to $22 billion (William Blair's net debt) leaves $28 billion to $31 billion for shareholders. On 264.6 million shares, that is about $106 to $117 a share, a premium of 27% to 40% over Thursday's close. This is our arithmetic on reported numbers. No price has been offered, and a final number would depend on the debt at closing and the financing terms. Our explainer on the takeover premium covers how buyers and boards arrive at that number.
The company's own results set the floor under the standalone case. In the third quarter, reported on Nov 5:
| Measure | Q3 2026 | Note |
|---|---|---|
| GAAP revenue | $3.31B | |
| Adjusted net revenue | $3.18B | up about 31%, over 4% normalized for Worldpay |
| Adjusted operating margin | 42.5% | up 220 bps normalized |
| Adjusted EPS | $3.58 | up 10%, in line with the $3.58 estimate |
| 2026 adjusted EPS guide | $13.60 to $13.80 | unchanged |
| Worldpay cost savings target | $650M | raised |
Chief financial officer Josh Whipple said the company expects to return more than $2 billion to shareholders in 2026, and it had returned more than $1.4 billion by the end of the third quarter. The board declared a $0.25 dividend for holders of record on Dec 10. Our guide on how to read an 8-K for catalysts shows what a formal approach would look like when it reaches a filing.
The bull case
A sponsor that already owns 16% of the company has the best view of the business of any outside buyer, and it chose to come back after the first effort failed rather than move on. That it is now lining up a group of firms suggests the problem in November was the size of the cheque, which a consortium is built to solve, not the price. The standalone numbers also support a higher price even without a deal: at about 6.9 times 2026 adjusted EPS guidance, a forward P/E near 5.8 and about 1.1 times book value, the market is pricing the company as if the Worldpay integration will not deliver. Management raised the cost savings target instead. The consensus analyst target is about $106.53, close to the low end of the per-share range a $50 billion deal implies, and 13% above today's price. Our guide to going-private transactions covers how a sponsor-led buyout of a listed company usually proceeds from here, through a special committee, a signed agreement and a shareholder vote.
The risks
- No offer. The report says GTCR is considering a bid. It is a soft catalyst until a proposal is made. Our explainer on hard and soft catalysts covers why the market discounts reports like this one.
- Financing. The first attempt failed on the complexity of a deal this size. The Paypers noted higher borrowing costs and tighter financing for deals of this scale.
- Debt. Net debt of about $22 billion limits how much new borrowing a buyer can add. Our explainer on net debt to EBITDA covers how lenders size that ceiling.
- A second round trip. The stock fell 12.0% in one session when the October talks ended. If this effort ends the same way, a fall back toward $84 is the obvious reference point. Our explainer on deal breaks covers how far a target typically falls when talks end.
- Conflicts. As the largest holder and the would-be buyer, GTCR sits on both sides. A board would likely need a special committee, which adds time.
What comes next
- Any company statement. Global Payments has not commented. A confirmation of talks, or a denial, would move the stock either way.
- Dec 10, 2026. Record date for the $0.25 quarterly dividend, payable Dec 24.
- A filing. A formal proposal from GTCR, or a signed agreement, would have to be disclosed in an SEC filing.
- February 17, 2027 (expected). The fourth-quarter report, the first update on 2026 results against the $13.60 to $13.80 guide and on the 2027 outlook. Our guide on how to build a catalyst calendar shows how to track dates like these.