

The five inputs
| Input | What it is | Effect on a call price when it rises | Effect on a put price when it rises |
|---|---|---|---|
| Stock price (S) | Current share price | Higher | Lower |
| Strike price (K) | Price at which the option can be exercised | Lower | Higher |
| Time to expiration (T) | In years | Usually higher | Usually higher |
| Interest rate (r) | Rate on a riskless asset, such as a Treasury bill, over the option's life | Higher | Lower |
| Volatility (sigma) | Annualized standard deviation of the stock's returns | Higher | Higher |
Four of these can be looked up. Volatility cannot: it is a forecast of how much the stock will move. That is why the model is most often used in reverse, as explained below.
Extensions add a dividend yield. A dividend paid during the option's life lowers the expected stock price at expiry, which lowers call values and raises put values.
The formula in plain words
For a call option, the model says:
Call value = S x N(d1) minus K x e^(-rT) x N(d2)
N() is the cumulative standard normal distribution: the probability that a normally distributed variable falls below a given value. The terms d1 and d2 combine the five inputs:
- d1 = [ln(S / K) + (r + sigma squared / 2) x T] / (sigma x square root of T)
- d2 = d1 minus sigma x square root of T
Read it as two pieces. The first, S x N(d1), is roughly the value of the stock you expect to receive if the option finishes in the money. The second, K x e^(-rT) x N(d2), is the present value of the strike you expect to pay, weighted by N(d2), which under the model's assumptions is the risk-neutral probability that the option finishes in the money. The call is worth the difference.
A put can be priced the same way, or from the call using put-call parity, which links calls, puts, the stock and the strike.
Worked example
The inputs give d1 of about 0.142 and d2 of about -0.008. N(d1) is about 0.556 and N(d2) about 0.497.
- Stock piece: $50 x 0.556 = about $27.82
- Strike piece: $50 x e^(-0.04 x 0.25) x 0.497 = about $24.59
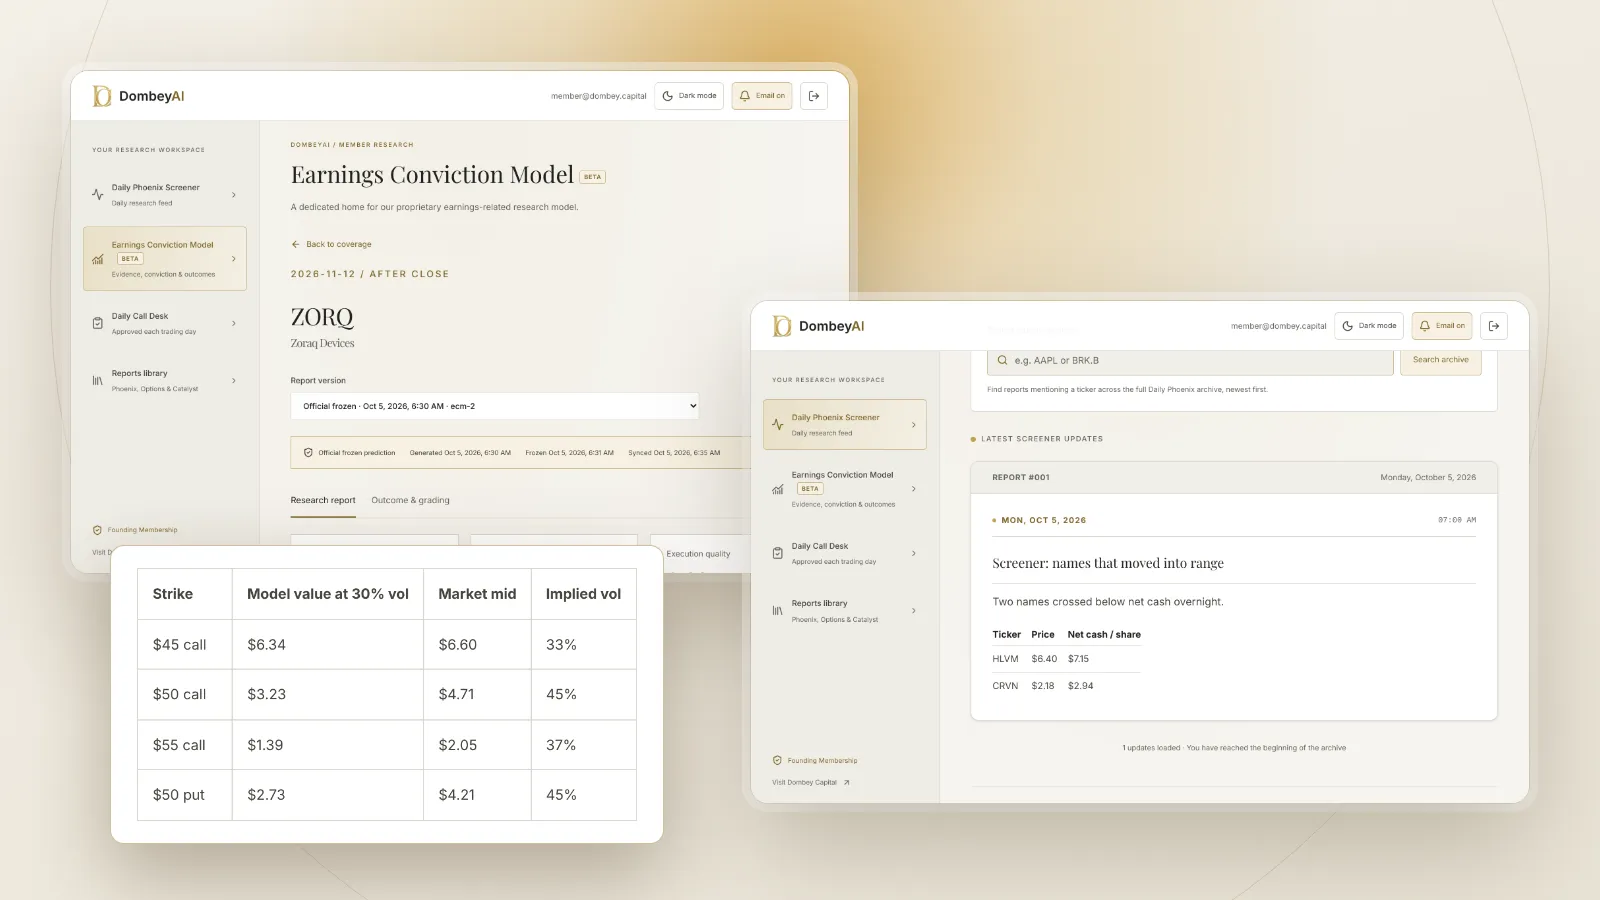
- Call value: about $3.23
The matching put, from the same inputs, is worth about $2.73. The call is worth more than the put at the same strike because the positive interest rate raises the forward price of the stock.
Now change one input at a time:
| Change | Call value |
|---|---|
| Base case: $50 strike, 30% volatility | About $3.23 |
| Volatility rises to 45% | About $4.71 |
| Strike rises to $55 (30% volatility) | About $1.39 |
A 15-point rise in volatility adds about 46% to the call's value. That sensitivity is vega, one of the option Greeks, and it is why volatility is the input that matters most in practice.
Using the model in reverse: implied volatility
Because the market already shows option prices, traders rarely use Black-Scholes to find a price. They take the price the market quotes, plug in the four observable inputs and solve for the volatility that makes the formula match. The answer is implied volatility.
Implied volatility turns option prices into a single comparable number. A $3 option on a $50 stock and a $12 option on a $200 stock can be compared on their implied volatilities. Measures such as IV rank and IV percentile and the volatility term structure are built on it.
The model is the translation layer. Using it does not mean the user believes its assumptions; it means everyone quotes options in the same units.
The assumptions
The model's result depends on a set of assumptions:
- Lognormal prices. Returns are normally distributed, so prices cannot go below zero and large moves are rare.
- Constant volatility. The stock's volatility does not change over the option's life.
- Constant interest rate. The riskless rate is known and fixed.
- Continuous trading. The stock can be traded at any moment, with no gaps.
- No transaction costs or taxes. Hedging is free.
- No arbitrage. There are no riskless profits to be made.
- European exercise. The option can be exercised only at expiration.
- No dividends in the original form, though extensions handle them.
Where this goes wrong
Each assumption fails in a way that matters for real positions.
Volatility is not constant. It rises in sell-offs and falls in calm markets. Options on the same stock trade at different implied volatilities across strikes and expiries, which the model says should not happen. That pattern, options skew, is the market correcting the model.
Returns have fat tails. Large moves happen far more often than a normal distribution predicts. Out-of-the-money options, especially puts, are priced higher than the model would suggest for that reason.
Prices jump. The model assumes a stock moves in small continuous steps. A stock reacting to an earnings report, a drug approval or a court ruling moves in one step, often overnight. For event-driven positions this is the most important failure. Options that span an event carry a separate event premium, which shows up as a spike in implied volatility for the expiry that includes the event and collapses afterward as IV crush.
Hedging is not free. Continuous hedging assumes zero costs. Real hedgers pay spreads, which are wide in illiquid options.
Early exercise. Listed US equity options are American-style. The model understates the value of puts that may be exercised early and calls on stocks about to pay a large dividend.
How event-driven investors use it
For a dated catalyst, the useful question is not the model price but what the market price implies. Traders back out the implied move for the event from the gap between the event expiry and the next one, compare it with how far the stock has moved after past events, and check whether a straddle is priced above or below that history. Our guide on estimating an earnings move from options walks through the steps.
Black-Scholes supplies the vocabulary for that comparison: implied volatility, delta and vega. The judgment about the event itself comes from outside the model. For current events moving options prices, see the market coverage.
The bottom line
The Black-Scholes model prices a European option from the stock price, strike, time, interest rate and volatility, and its most common use is backing out implied volatility from market prices. Its assumptions of constant volatility, lognormal returns and smooth price paths do not hold, and the failure is sharpest around events that make a stock jump. Use it as a common language for comparing options, not as a source of fair value. When the model and the market disagree, the market is telling you something about volatility.