

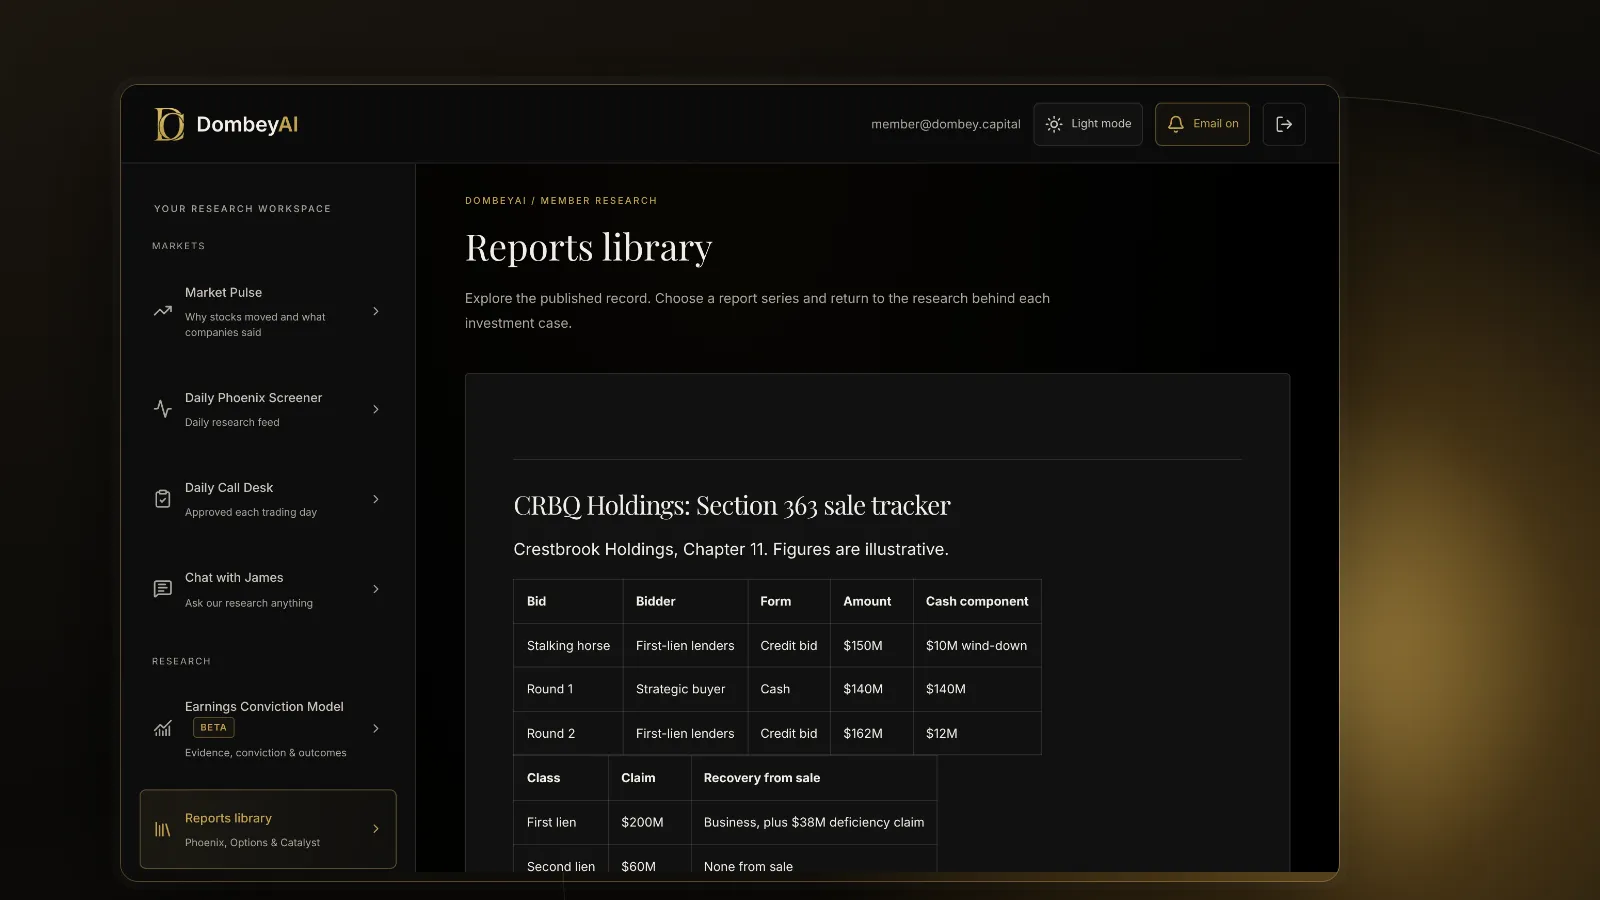
How a credit bid works
In a Chapter 11 sale, the debtor sells assets, often the whole business, to the highest or best bidder under Section 363. Our explainer on Section 363 sales covers the process in full. A secured lender whose loan is backed by those assets has a choice: it can let others bid and take the cash proceeds up to its claim, or it can bid itself.
If it bids, it does not need to bring new money for the amount covered by its claim. It offers to reduce the debt owed to it by the bid amount. Cash is still needed for anything the bid must cover beyond the secured claim, such as cure costs on assumed contracts, wind-down costs or payments to creditors ahead of the lender.
Why the face-value rule matters
A credit bid counts at the face amount of the allowed claim, not at the price the holder paid for it. This one feature shapes much of distressed investing:
- Discounted debt becomes bidding power. A fund that buys a secured loan at 60 cents on the dollar can credit bid at 100 cents. Its effective cost of acquiring the business is lower than any cash bidder's.
- Loan-to-own strategies rely on it. Investors seeking control buy the fulcrum secured debt, then use the credit bid or a plan to convert it into ownership. Our explainer on debt-for-equity swaps covers the plan route.
- It sets a high floor. Cash bidders must beat a bid that costs the lender little in new money. That can discourage outside bids.
| Feature | Cash bid | Credit bid |
|---|---|---|
| Paid with | New money | Reduction of the secured claim |
| Who can make it | Anyone qualified | Holder of an allowed secured claim on the assets sold |
| Measured at | Cash amount | Face amount of the claim bid |
| Effect on lender's claim | Paid from proceeds | Reduced by the bid amount |
| Cash still needed | Full price | Amounts senior to the lien, cure costs, wind-down |
| Can the court limit it | Bid procedures apply | Yes, for cause under 363(k) |
Where credit bids sit in the bankruptcy process
Credit bids most often appear in three places:
- As the stalking horse. The lenders' credit bid is the first offer, and the auction asks others to top it. Our piece on stalking horse bids explains the protections a stalking horse negotiates.
- In the auction itself. Lenders may raise their credit bid in response to cash offers, up to the face of their claim.
- In a plan sale. In RadLAX Gateway Hotel v. Amalgamated Bank (2012), the Supreme Court held that a plan proposing to sell collateral free of liens cannot be crammed down on the secured lender under that route without allowing it to credit bid.
Credit bids also tie into financing. A lender providing debtor-in-possession financing often gets the right to credit bid its DIP claim, and the DIP terms may set milestones that push the case toward a quick sale.
What a credit bid means for each class
- Secured lenders. They take the assets. Any part of their claim not covered by the bid becomes a deficiency claim, usually unsecured.
- Junior secured and unsecured creditors. If the winning bid does not exceed the senior secured claim, sale proceeds do not reach them. They may still negotiate for a settlement, often funded by the buyer, in exchange for not objecting.
- Equity. In most credit-bid cases the existing shares receive nothing. That is consistent with what usually happens to stock in Chapter 11.
- Claims traders. The size and terms of the credit bid change the value of claims across the structure. Our explainer on claims trading covers how those claims are bought and sold during a case.
When courts limit credit bids
Section 363(k) lets the court restrict credit bidding "for cause". Courts have used that power in specific circumstances:
- Disputed liens. If the validity, priority or extent of the lender's lien is under challenge, the court may cap the bid until the dispute is resolved.
- Partly unencumbered assets. If some assets being sold are not covered by the lender's lien, the lender cannot credit bid for those and must pay cash.
- Chilling the auction. A few courts have capped credit bids, sometimes at what the lender paid for the debt, where a full credit bid combined with a rushed timeline would have shut out competing bidders.
- Inequitable conduct. Misconduct by the lender in the case can be cause.
These decisions are fact-specific, and a cap is the exception. Most credit bids proceed at the face amount of the claim.
How to read a credit bid in a filing
The key documents are on the bankruptcy court docket, which is accessible through PACER, and often on the claims agent's free website:
- The sale motion and bid procedures. These state whether the lenders may credit bid, how much, and what cash component is required.
- The DIP order. It often confirms the credit bid right and sets sale milestones.
- The asset purchase agreement. It lists what is acquired, what liabilities are assumed and the cash paid.
- The disclosure statement. If the sale is followed by a plan, it sets out expected recoveries by class. Our guide on reading a Chapter 11 disclosure statement explains the recovery tables.
To place the credit bid in context, map the capital structure first: the size of each layer and its security determine whether anything is left beyond the bid.
Where this goes wrong
- Assuming the credit bid is the value. A credit bid at face may be well above what the business is worth. It reflects the lender's claim and incentives, not a market price.
- Ignoring the cash component. Required cash for cure costs, priority claims and wind-down can be large, and an underfunded bid can change the outcome.
- Missing lender disagreements. Lenders do not always act as one group. Disputes among lenders can change who controls the bid.
- Forgetting deficiency claims. A lender whose bid is below its claim still holds an unsecured claim for the rest, which dilutes recoveries for other unsecured creditors.
- Relying on outdated docket summaries. Bid procedures, deadlines and caps can change by court order. Check the latest filings.
Special situations newsletters that follow bankruptcies often track these filings closely; our list of the best investing newsletters for special situations notes which cover restructurings.
The bottom line
A credit bid lets a secured lender acquire its collateral by cancelling debt instead of paying cash, and it counts at the face amount of the claim. That rule gives lenders who bought debt at a discount a real advantage in bankruptcy auctions and often sets a floor others cannot beat. For shareholders and unsecured creditors, a large credit bid usually means little or nothing is left. Read the bid procedures, the cash component and any court-imposed cap before drawing conclusions from a case.